Research Article | | Peer-Reviewed

Monetary-Fiscal Policy Interdependence and Pricing Dynamics: Empirical Estimation of Fiscal Dominance in Kenya

Received: 23 March 2025     Accepted: 31 March 2025     Published: 9 May 2025
Views:       Downloads:
Abstract

This study examined the effectiveness of monetary and fiscal policies in establishing fiscal dominance in Kenya. This study employed monthly data from January 2010 to December 2022. Using Structural Vector Autoregressive (SVAR) model, this study captures price dynamics through three channels: foreign exchange, inflation, and lending rates. All the data were obtained from the Central Bank of Kenya Online Repository. The empirical assessment led to three broad and insightful conclusions. First, from the policy front, monetary policy is not fully effective in controlling and stabilizing prices. Second, expansionary fiscal policy is not only inflationary but also leads to higher interest rates. Third, there are traces of fiscal dominance, even though it’s not a very high form of fiscal dominance (which this study calls the slow intrusion of fiscal policy into the monetary policy space). Therefore, the study concludes that while fiscal dominance may not be very pronounced, there is a need to review the interplay between monetary and fiscal policies to fully gain from the interdependence of the two policies by stabilizing prices, enhancing growth as expected, and avoiding the macro-economic instability that comes with fiscal dominance. The study recommends reducing government borrowing, especially domestic borrowing, cutting unnecessary spending, directing spending towards development projects such as infrastructure and sectors that support growth, establishing the necessity of currency pegging to avoid unpleasant multiplier effects on fiscal dominance, reviewing the emergence and effects of dollarization in Kenya, and finally reviewing fiscal policy and establishing a Fiscal Policy Committee (FPC).

Published in Journal of World Economic Research (Volume 14, Issue 1)
DOI 10.11648/j.jwer.20251401.16
Page(s) 61-79
Creative Commons

This is an Open Access article, distributed under the terms of the Creative Commons Attribution 4.0 International License (http://creativecommons.org/licenses/by/4.0/), which permits unrestricted use, distribution and reproduction in any medium or format, provided the original work is properly cited.

Copyright

Copyright © The Author(s), 2025. Published by Science Publishing Group

Keywords

Monetary Policy, Fiscal Policy, Fiscal Dominance, Inflation, Interest Rates, Interest Rates, Dollarization, SVAR

1. Introduction
Periods of fiscal and monetary dominance have long been a topic of discussion. However, recent macroeconomic measures to stabilize the economy after the COVID-19 pandemic have elicited debate as to whether there is a return of fiscal dominance and whether it poses a threat to central bank independence . Monetary dominance is a situation in which price stability takes precedence over fiscal stability, whereas fiscal dominance is a situation in which fiscal stability has priority over price stability. Many economists argue that fiscal dominance is a recipe for macroeconomic instability, high inflation, debt, and deficits . In times of fiscal dominance, controlling inflation becomes very difficult because the measure of raising interest rates would be counterproductive as the government would be unable to repay its debts. On the other hand, a monetary dominance regime reduces the probability of having any room for fiscal adjustment and, hence, increases the probability of inflation .
Central Banks have always played an independent role in stabilizing inflation by setting interest rates without government interference. Many economists have described this as monetary dominance, as the central bank worked in isolation to control and stabilize the economy. Global economies employ fiscal and monetary policies as tools to achieve macroeconomic objectives, including ensuring attractive price levels and controlling inflation. While fiscal policies are managed by the central government through legislation with the main view of enhancing output, central banks manage monetary policies with the key aim of controlling inflation by controlling the money supply and interest rates. However, the overarching goal of both monetary and fiscal policies is to create an economic environment in which growth is stable and positive and inflation is stable and low. The high volatility of inflation over time increases price-level uncertainty and instability .
Debrun asserts that expansionary fiscal policy, especially increased government spending, could lead to increased aggregate demand and, hence, increased inflation. Similarly, expansionary monetary policies, such as reduced interest rates or increased money supply, could stimulate lending and investment, and hence, increase inflation A potential problem with expansionary fiscal policy is that it leads to an increase in the size of a government’s budget deficit and, therefore, quite often, increased government spending is financed through increased government borrowing and hence induces a debt multiplier effect . However, this borrowing affects the economy through crowding out, since most of these governments always borrow from the private sector, which reduces private sector investment.
Ordinarily, to keep inflation low, governments would expect them to reduce spending and increase taxes to reduce money entering the economy. However, this move would be unpopular and might not stimulate the economy; therefore, the way the government controls inflation is through central banks through monetary policy with the view of price stabilization. According to Keynesian models, an active monetary policy ensures macroeconomic stability by controlling inflation . However, inflation volatility has been increasing over the years, and there have been challenges in stabilization due to the high uncertainties surrounding the economic and inflation outlook .
While the two policies are meant to operate independently, the implementation of one always affects the performance of the other, and there is often tension between the government arms that implement them. However, there have been instances where a trade-off has occurred between the two policies. For example, fiscal policies during a recession tend to be more attractive than monetary policies, and vice versa. Patella et al., posits that the monetary-dominant regime is one in which we have an active monetary-passive fiscal policy combination in which the central bank controls inflation and the fiscal authority passively accommodates to stabilize debt .
In 1992, there was considerable money supply growth to finance the first multi-party elections, with broad money (M2) growing by about 1500 basis points from 21% percent in the 12-month period ending December 1991 to 36 percent in March 1993 . By 1993, market liquidity had grown considerably, KES slumped, and dollarization heightened. Later that year, a contractionary monetary policy was implemented to increase excess liquidity, stabilize KES, and address dollarization. By late 1993 and early 1994, the contractionary policy saw a tremendous increment in interest rates with the Treasury bill rate at some point rising beyond 55% .
While there have been successes in Kenya’s monetary policy since the 1990s and the introduction of the Central Bank Rate (CBR) and the operational challenges of anchoring the overnight interbank rate to the policy rate, with the overnight interbank rate experiencing large and persistent deviations from the CBR, there have been notable target misses even after the introduction of inflation targeting. This includes a disconnected CBR from money market rates, thereby undermining the credibility of the inflation target . However, during the 2020 Covid-19 pandemic demonstrated that monetary policy did not always control inflation on its own, and fiscal policy interplay was needed to stabilize inflation This is because increasing public debt has led to an increasing possibility of fiscal dominance in which public deficits do not respond to monetary policy.
Just before the 2022 elections, especially during the Covid-19 period, the Kenyan government had introduced subsidies with highly moderated inflation, but public debt rose to 64% of the Gross Domestic Product (GDP), and fiscal deficit narrowed to 6.3% of GDP due to increased revenue collection . However, after the 2022 elections, When Kenya’s current administration took office, price subsidies were removed, causing an increase in consumer prices (in ways that the typical monetary policy tool, interest rates, were not able to be immediately controlled), new/additional taxes were imposed (fiscal policy), and public sector borrowing increased (fiscal policy) when some previous debt (such as a tranche of the Eurobond 2018) matured, causing a drastic decrease in the value of the KES. According to Central Bank of Kenya reports, inflation has moved from 5.41% in December 2020 to 7.95 in December 2022 and about 8.68 in July 2023. Public debt, On the other hand, has increased to approximately 70% of the GDP .
While the main objective of the Central Bank of Kenya is to achieve and maintain price stability by formulating monetary policy and ensuring that inflationary pressures are reduced, the recent years inflation targets had been largely above 7.5%, against the preferred range of 2.5% to 7.5% set by CBK. This rate has only dropped from July 2023 to 7.3%, for instance, since May 2022. This high inflation could be attributed to high food prices due to increased petroleum products, leading to a multiplier effect on the electricity price, production, and distribution costs.
Despite the efforts by the Central Bank of Kenya to contain inflation, the removal of subsidies by the government, increased public debt and the fiscal consolation path initiated by the International Monetary Fund could have resulted in increased inflationary pressure. In recent years, the Kenyan government has made heightened efforts to collect revenue and increase taxes. In examining the effectiveness of monetary policy in Kenya, were et al., found that monetary policy is effective in controlling inflation . However, Nathan and Jagongo found that monetary policy tools are mixed in their effectiveness in controlling inflation . The authors found that the 91-day treasury bill is an effective price control tool as opposed to money supply. In addition, Nyakerario and Morekwa found no significant effect of monetary policy on asset prices .
Considering that Kenya is currently on a weekly sustainable fiscal path, where government revenue does not fully finance government expenditure, concerns have been raised about issues of public debt , and there is a need to establish whether fiscal policy affects monetary policy effectiveness in controlling prices. Recent studies on the effectiveness of monetary policy on price dynamics in Kenya have provided mixed results, with most focusing only on the effectiveness of monetary policy from the inflation channel .
Kenya pursues an inflation targeting (IT) regime similar to many other developing economies because of its proven resilience, and there has been developing evidence that IT regimes are no better than countries pursuing other non-inflation policies In fact, Thornton concluded that the less technically demanding monetary regime of currency pegging remains an attractive option for policymakers in developing countries . However, Davis et al. posits that when relatively closed (highly open) central banks become less credible in controlling prices, they can only adopt an inflation target pegged on the exchange rate, but this will depend on trade openness .
In addition, Ahmed et al. assert that most emerging economies under non-inflation-targeting regimes are exchange-rate targeters . These economies are thought to always fear floating exchange rates because exchange rate depreciation would lead to high costs of servicing their external debts; therefore, the fiscal authority ends us using the central banks to target real exchange rate stabilization over inflation, and this would in itself be a recipe for fiscal dominance. Strong & Yayi and Taiebnia et al. argued that fiscal dominance in Africa takes many forms, ranging from direct financing of government debt by central banks and commercial banks to interfering with monetary policy by putting pressure on central banks to keep interest rates low or to intervene in foreign exchange markets to limit currency depreciation and lower debt servicing costs . However, less attention has been paid to the effects of these policies on exchange rate channels .
Another concern that has been raised revolves around dollarization, both in terms of transaction dollarization (also known as currency substitution, which is the use of foreign currency for transaction purposes) and financial dollarization (also referred to as asset substitution), which consists of residents’ holdings of financial assets or liabilities in a foreign currency . The greater the dollarization of the economy, the lesser the scope of independent monetary policy. Dollarization or the use of foreign currencies might indicate a lack of confidence in the stability of the local currency while simultaneously increasing inflation at the same time .
Given the recent fiscal stimulus to the economy and the subsequent reversal thereof, uncontrolled government spending, rising public borrowing, and sentiments about dollarization of the Kenyan Economy, many concerns and questions have been raised regarding whether the central government is undermining the Central Bank of Kenya in influencing monetary policy to accommodate the cost of debt servicing or fiscal sustainability at the expense of stabilizing price rates through market activity. These concerns rotate around high inflation and foreign-exchange fluctuations. Considering that the debate surrounding the role of fiscal policy in the price determination process remains inconclusive and economy-specific, there is a need to further review the existing literature and conduct tests, especially in Africa, on the interdependence between monetary and fiscal policy to confirm or allay fears of fiscal dominance . Therefore, this study is centered on fiscal and monetary policy interconnections and their role in pricing dynamics, particularly inflation, lending rates, and exchange rates.
1.1. Research Objectives
1. To Determine the effect of Monetary Policy on Inflation, Lending rates and Exchange rate
2. To Examine the effect of Fiscal Policy on Inflation, Lending rates and Exchange rate
3. To Establish if fiscal dominance exists in Kenya through pricing.
1.2. Significance of the Study
All the objectives of this study will be geared towards contribute to the existing literature and inform market players and policymakers on the way forward with regard to market structure and policy formulation to support growth while controlling for pricing dynamics. First, the study addresses the debate around fiscal dominance in Kenya, and second, it will help readers and other researchers understand the interaction between the two policies. This study addresses the effectiveness of monetary policy in stabilizing pricing volatility and how fiscal policy interplay affects the transmission of monetary policy and vice versa. Third, bankers benefit from the study by understanding how policy implementation affects the pricing of loans, which in the bottom line affects their loan performance and profitability. Finally, the study further examines how other macroeconomic factors, such as exchange rates and international oil prices, affect financial pricing in Kenya. This will assist in foreign exchange targeting policy settings and in the financial interplay between foreign exchange and foreign currency credit product pricing. The remainder of this paper is organized as follows. Section 2-part reviews the previous literature, and Section 3 describes the methodology and data. Section 4 reviews the analysis and results of the study. Section 5 presents the conclusions and policy recommendations of the study.
1.3. Stylized Facts
While monetary policy decisions in Kenya are undertaken by the Central Bank of Kenya through the Monetary Policy Committee (MPC), Fiscal Policy is undertaken through the National Treasury. However, there is no specific committee that sets limits or targets for spending, fiscal deficits, or public debts. In addition, monetary policy is guided by a monetary program anchored on economic growth and inflation targets, which are also provided by the National Treasury. According to Mutuku, Kenya’s fiscal policy stance is geared towards macroeconomic stability, sustainable growth, and a conducive environment for investment and innovation .
In the late 1990s, Kenya pursued an inflation objective in the context of a managed float with a variety of instruments and reserve money functioning as the operational target. As of October 2011, CBK took steps to develop a more forward-looking monetary framework, moving gradually towards an inflation-targeting regime. The Central Bank Act stipulates that the National Treasury, in consultation with the CBK, set an inflation target at the beginning of every fiscal year.
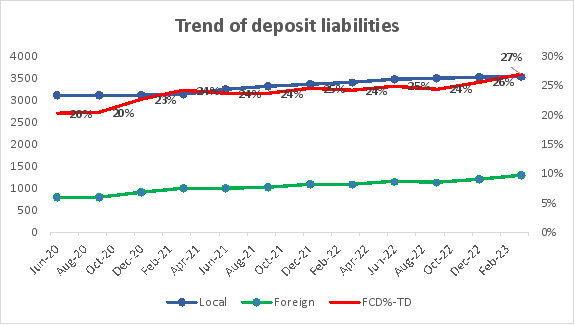
While there is no evidence of large dollarization in Kenya, The Figure 1 shows a large increase in the share of foreign currency deposit liabilities in the country from 20% in June 2020 to 27%. This is a significant increase over approximately three years.
Source: Central bank of Kenya

Download: Download full-size image

Figure 1. Trends of deposit liabilities as proxy for dollarization in Kenya.
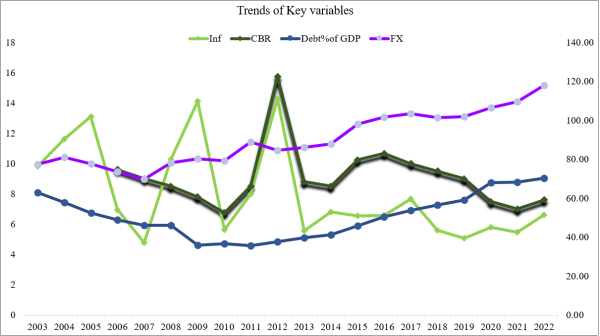
However, as indicated in Figure 2, public debt to GDP has increased from about 36.69% in 2009 to about 70% in 2022, with inflation seemingly moving in the same direction as the Central Bank Rate. In addition, analysis of expenditures for years, data from Central Bank of Kenya indicates that average, recurrent expenditures account for about 71% of the total expenditures. We also observe that the Foreign Exchange rate moves in the same direction as the public debt movement.
Kenya’s fiscal policy is mainly driven by taxes and government spending. However, taxes have been the main driver of revenue mobilization.
This is not sufficient to cover government expenditure. Therefore, government spending has necessitated a multiplier effect by enhancing fiscal deficits and public debt, which has led to more questions than answers regarding sustainability. However, questions have been asked about the inflationary inducement of public debt, especially in the domestic market. However, the government of Kenya still maintains its aim of fiscal consolidation to stabilize debt over the medium-term.
Source: Central bank of Kenya

Download: Download full-size image

Figure 2. Trends of Key Variables in Kenya (2003- 2022); FX is (KES-USD).
2. Review of the Literature
2.1. Theoretical Review
This study is anchored in the Fiscal Theory of Price Level (FTPL) as propagated by . However, the theory has its origins in the paper by Sargent & Wallace titled Some “Unpleasant Monetarist Arithmetic” in which they assert that since monetary authority affects the extent to which seignorage is exploited as a revenue source, monetary and fiscal policies simply have to be coordinated . However, they pose a big question as to which of the two policies moves first in determining price dynamics: monetary authority or fiscal authority. Essentially, the FTPL gives fiscal policy an upper hand or first priority in determining the price level, with monetary policy playing the second fiddle. This theory describes the interconnection between fiscal and monetary policies in the determination of price dynamics, especially through government debt .
The theory in effect contradicts the monetarist point of view that money supply growth is a factor of price level and inflation, hence defying the quantity theory of money (QTM) in explaining price dynamics in a given economy. The theory rests on the assessment of fiscal policy, in which government expenditure and revenue . The FTPL assumes that the government’s fiscal policy moves first, and has complete control over public debt. However, other factors, such as the availability of lenders, interest rates, and external factors such as foreign exchange, play a significant role. The theory also assumes that monetary policy will always accommodate fiscal policy when adjustment occurs, but in reality, this does not happen, as the central bank could decide to change to take a different policy direction from that of the government. Farmer & Zabczyk assert that price levels and interest rates are indeterminate even when both monetary and fiscal policies are active. The authors argue that a good combination of fiscal and monetary policies is required to determine the prices.
2.2. Empirical Review
Using a large sample of developing countries, Thornton appears to refute earlier suggestions in the literature that developing countries adopting inflation targeting (IT) regimes experienced greater drops in inflation and GDP growth volatility than non-IT developing countries . Indeed, the study finds that (i) inflation performance in inflation-targeting economies is no better than the average for countries with alternative monetary regimes, and (ii) Inflation Targeting does not reduce GDP growth volatility compared to other monetary policy regimes. (iii) There is no reason to favor Inflation Targeting over a hard currency peg or narrowband crawling peg in developing countries. Thornton concludes that the less technically demanding monetary regime of currency pegging remains an attractive option for policymakers in developing countries .
Since the Covid 19 pandemic the debate on the role of fiscal policy in controlling inflation has emerged again in view of the government’s response to spur economic growth. A number of studies that have supported this school of thought include Munir & Riaz, who investigated the relationship between fiscal policy and inflation using Johansen cointegration and the VECM and found fiscal dominance in Pakistan . The results reveal that fiscal imbalances do not affect inflation, but government borrowing intended to support budgetary deficits has a significant influence on inflation. The authors concluded that the Pakistani economy is largely affected by fiscal dominance, which is responsible for explaining price movements.
Were et al. examined the effectiveness of monetary policy in Kenya using structural macro-econometric models. This study used the central bank rate (CBR) and cash reserve ratio (CRR) with respect to the interest rate . The results reveal that CBR has a comparatively higher impact on inflation, while a change in CRR has a relatively larger impact on aggregate demand. By contrast, Ikikii examined the Effectiveness of Monetary Policy in Kenya using quarterly data from 2000(Q1) to 2014 (Q1). The author employed Impulse Responses and Variance Decomposition from Vector Autoregressive (VAR) model, and the results revealed that real money demand and reserves have a short-run but no long-run effects on inflation.
Using Granger causality and VAR approaches, Nyakerario & Jagongo examined the importance of the relationship between monetary policy variables and inflation . The results reveal the dominant role of fiscal policy on both price and output. Mathu et al. empirically analyzed the effects of fiscal deficits on inflation in Kenya using quarterly data for the period 1996(Q1)-2017(Q2). The results revealed that the money supply was statistically insignificant and had unexpected negative signs . This finding indicates that money supply is not an important determinant of inflation in Kenya in the short term. The results also did not show any evidence of a long-run relationship between fiscal deficit and inflation. However, with additional control variables, fiscal deficit portrayed the existence of a long-run relationship.
Munir & Riaz analyzed the short- and long-run effects of fiscal policy on inflation in Pakistan. The authors also incorporated fiscal policy volatility, discretionary fiscal policy, and volatility of discretionary fiscal policy following the IS-LM model and conducted the study using the autoregressive distributed lag (ARDL) model. Using data from 1976 to 2019, the study showed that the volatilities of imports, exchange rate, and output positively affected inflation volatility, but fiscal policy volatility, discretionary fiscal policy, and volatility negatively affected it. The study also reveals that the active and timely implementation of fiscal policy directly reduces inflationary pressure. Therefore, the authors conclude that there is a need for an active and efficient role for the government in maintaining stable prices.
Richard et al. analyzed the relative effectiveness of monetary and fiscal policies on output stabilization in developing countries, using Rwanda as a case study. The authors used quarterly data between 1996-2014 by employing a recursive VAR model with 12 variables (including five endogenous and 7 exogenous variables). The results obtained using impulse responses and variance decomposition reveal that monetary policy is more effective than fiscal policy in explaining changes in nominal output in Rwanda. On the other hand, Duodu et al. analyzed the effects of money supply and budget deficits on inflation and found that inflation responds more positively to budget deficit shocks but negatively to money supply (M2) shocks .
Jesus et al. examined the macroeconomic effects of monetary policy shocks under fiscal restrictions on government expenditures in Brazil using a DSGE model. The researcher’s variables of interest included real GDP, nominal interest rate, and household consumption, with a quarterly dataset from 2003 Q1 to 2018 Q4 . The results indicate that a restrictive fiscal rule provides more stability to public debt, whereas monetary policy shocks reduce household consumption.
While analyzing the interdependence of fiscal and monetary policies, Bucacos found that for inflation, Uruguay is not exclusively a monetary policy affair, but elements of fiscal policy, such as fiscal debts, also induce inflation, thus pointing to the possibility of fiscal dominance . However, the level of dominance was limited to fiscal deficits affecting consumer prices by only about 6 percent only. While applying the Markov regime-switching model to estimate monetary and fiscal policy rules in India, Arora asserted that, for the period under study (1951-2018), India had a fiscal-dominated regime with a few periods of monetary restraint . The author further argues that while monetary policy in India achieved independence post-1990s, it largely accommodated fiscal policy. Therefore, whenever monetary policy was active, fiscal policy undermined its effectiveness by not accommodating it. Interestingly, Canzoneri et al. posed the question of whether the price level is determined by fiscal solvency needs . In this study, the results reveal that the data are inconsistent with the fiscal dominance hypothesis; hence, the results support a monetary dominance regime. They conclude that in the US, the price level is not controlled by fiscal solvency but still follows the traditional monetary policy approach, where prices are pegged to interest rates set by the central bank.
Sanusi estimated the impact of fiscal dominance and inflation in Nigeria and South Africa by analyzing the interdependence between fiscal and monetary policies to determine whether fiscal dominance gags monetary action . The study results showed no evidence of fiscal dominance, with Nigeria an interdependence of 84% between the two policies, while South Africa had interdependence rate of 67%. Similarly, Sanya investigated the presence of fiscal dominance and the effectiveness of monetary policy in sub-Saharan African countries between 1995 and 2018, using a Panel Vector Error correction model . The author finds an absence of fiscal dominance in the selected sub-Saharan African countries during the study period. The study agreed with the study by Kamila who found no evidence of fiscal dominance in India .
Mangani conducted a study to determine whether fiscal dominance existed in Malawi. The author employed an autoregressive distributed lag (ARDL) model to test the effects of inflation shock transmission from fiscal deficit and its financing after controlling growth in agricultural output monetary policy (growth in money supply) and other macroeconomic factors, such as growth in real per capita income, exchange rate, and trade openness . Annual data for all variables were used for the period 1970-2016. The study results revealed that there is a lack of fiscal dominance and concluded that external factors such as volatile donor aid and foreign exchange reserves play a more key role in price stability in Malawi than fiscal policy operations; therefore, to address economic stability, there is a need to address external factors through monetary policy.
However, some studies have called for a coordinated fiscal and monetary approach . These studies employed the Autoregressive Distributed Lag Model (ARDL) and the Granger causality approach to examine the impact of fiscal deficits on inflation in Namibia using data from 2002-2017 to. The results indicate a positive long-run relationship between the fiscal deficit and inflation. The results also indicate unidirectional causality emanating from fiscal deficit to inflation in Namibia. To bring fiscal deficits within acceptable levels, the authors conclude that fiscal and monetary policies should be well-coordinated.
Yasmin examined the Dynamic Impact of Fiscal Policy on Inflation in Pakistan using a dataset from 1976 to 2019 . The study employed the ARDL model, and the results indicated that in an open economy, the government plays an important and dominant role in determining price levels. The study concludes that while fiscal policy is key to maintaining inflation in control in Pakistan, there is a need for a coordinated approach between fiscal policy measures and monetary policy interventions.
In their study on the management of fiscal and monetary policy interdependence in the South African economy, Sanusi et al. employed a Bayesian VAR model using monthly data from 2009 to 2019 on inflation rate, interest rate, money supply, tax revenue, government spending, and government debt . The results showed that shocks to the money supply led monetary policy authorities to raise interest rates. The study also reveals that government spending tends to fluctuate in response to money-supply shocks. Interestingly, Inflation did not respond to a shock in government spending; hence, they concluded that inflation in South Africa could be driven from the supply side instead of the demand side. While analyzing the effects of inflation measured by the consumer price index (CPI), which is affected by the exchange rate, interest rate, taxation, imports, current account, unemployment, gross domestic product (GDP), and money supply in Kuwait, Ahmed et al. found that changes in the CPI are positively and significantly influenced by changes in interest rate spreads, imports of goods and services, and money supply .
Mishchenko examined the interdependence between monetary and fiscal policies in Ukraine for the period 2000-2007. This study aims to evaluate how the coordination of these two policies stimulates economic growth. This study examines the influence of the monetary aggregate M3, inflation rate, and weighted average base interest rate on the growth rates of real GDP in Ukraine. The results reveal that money supply M3, inflation, and the weighted average key interest rate negatively influence the growth rates of real GDP because of the close relationship between the money supply growth rates and the inflation rate, as well as the monetary restriction due to the growth of the discount rate. This study also reveals that increased government debt influences currency stability. Finally, the study revealed that the absence of coordination between monetary and fiscal policies in Ukraine during 2009- 2017 led to an increase in inflation and slower economic growth; therefore, to address inflation and spur economic growth, there is a need to have a consistent decrease in the interest rate with simultaneous improvement of central bank deposit operations while simultaneously reducing external public debt. This study agreed with similar study by Borio & Disyatat and Bartsch et al.
Chibi et al. examined the interaction between monetary and fiscal policies in the Algerian context using data from 1963 to 2017 and found evidence of non-Ricardian fiscal policy dominance when the vector autoregression (VAR) model was used, with fiscal balances having a negative correlation with government liabilities. The results also reveal that consumer prices in Algeria are largely driven by fiscal policies when applying the ARDL model. The authors also found that fiscal policy does not respond to monetary policy shocks, but monetary policy is responsive to fiscal policy shocks, which is another indication of fiscal policy dominance. When the Markov-switching model was applied, the results showed that monetary and fiscal policies in Algeria interacted counteractively for the period under study, with fiscal policy being active and monetary policy playing a second fiddle passively. Similarly, Osei & Ogunkola employed the (MSRDM) to investigate the regime effects of fiscal deficit financing on inflation and found fiscal dominance in Ghana by having a stronger effect on inflation in the higher regime of fiscal deficit financing and a low impact on inflation in the lower regime of fiscal deficit.
Park & Son investigated the effects of dollarization on exchange rates and inflation across foreign exchange regimes. The authors employed fixed-effects models in 28 countries for the period 1995-2016. The results reveal that high dollarization, or a high depreciation rate of the domestic currency tends to increase inflation, and these effects are found to be more significant in dollarized economies. Other authors who studied dollarization effects include Kessy and Mohamoud .
3. Methodology
3.1. Model Specification
Various authors have used the structural vector autoregressive (SVAR) methodology to examine how an economy responds to different shocks. These include monetary policy shocks, for which Sims, Christiano et al. and Wolf have been used, while under fiscal policy shocks, Blanchard & Perotti, Mountford & Uhlig and Romer & Romer also employ SVAR in their empirical studies.
SVAR analysis starts by estimating a reduced simple VAR model of order p
yt=μ+A1yt-1+A2yt-2++Apyt-p+ϵt(1)
where yt is a K*1 vector of variables, A is a K*K coefficient matrix, μ denotes a K*1 vector of intercept terms and ϵt is a K*1 dimension vector of white noise that are serially uncorrelated but may be mutually correlated.
Equation 1 can be reduced to
AUt=BVt(2)
Using the simple reduced-form equation 2 above, we can rewrite the equation to fit our dynamic variables in the study by applying the identification strategy proposed by Blanchard & Perotti where the reduced equation 2 from residuals can be written as linear combinations of the underlying "structural" shocks Vt .
AYt=ALYt-1+AUt=ALYt-1+BVt(3)
where A(L ) is an (n*k) matrix polynomial of the lag operator and Yt is an (n*1) vector of endogenous variables of interest that can be divided into policies ( Monetary and Fiscal Policies). Ut is a vector of the reduced form of the residuals. Vt is an (n*1) structural disturbance with a zero mean of 0 and Var(Vt)=Ψ (where Ψ denotes a diagonal Matrix) The elements of the diagonal matrix represent variances of structural disturbances; therefore, we assume that the structural disturbances are mutually uncorrelated.
We then express the reduced form of the residuals as Ut= uts utfutd utp. where uts is government spending, utf is the fiscal deficit, utd is public debt, and utp is price dynamics (inflation and lending rates). The residuals are also repeated for monetary policy shocks.
After estimating the VAR model, impulse responses are computed to evaluate the dynamic effects of structural shocks on fiscal and monetary policies. This study aims to identify structural shocks and the response of inflation and lending rates to these shocks.
3.2. Data
Monthly data for all the variables from January 2010 to December 2022 were used in this study. The inflation and interest rates are used as response variables to represent pricing dynamics. The consumer price index (CPI), average bank lending rates, and Foreign Exchange rates (USD-KES) were used as proxies for pricing dynamics. The Central Bank Rate (CBR) represents the monetary policy stance, while government spending and public debt represent the fiscal policy stance. When government expenditure exceeds government tax revenues in a given year, the government runs a budget deficit for that year. Budget deficit, which is the difference between government expenditure and tax revenue, is financed by government borrowing. This is the main reason for including public debt as an additional proxy for fiscal policies. The 91-day treasury bill rate was used as a double-edged sword. This is because Treasury bill rates reflect two factors: market liquidity conditions and the extent of borrowing by the government. While the latter partly reflects the fiscal policy stance (not the monetary policy), one cannot fully discount the effect of market liquidity on Treasury bill rates. It is also reasonable to argue that the government may use treasury bills to control the money supply, which would reflect the monetary policy stance. Thus, whether the Treasury bills rates represent monetary policy, or fiscal policy depends on their purpose, but importantly, the interest rate on those bills are not a “pure” reflection of the policy position of the government since they are market determined.
4. Empirical Findings and Discussion
4.1. Descriptive and Stationarity Test
Considering that all variables save for the central bank rate, Lending Rates, and T-bill are natural logs, we could consider the values presented as growth rates of those specific variables. Therefore, descriptive statistics presented in Table 1 indicate that foreign exchange rate has been growing at a rate of about 4% on monthly basis, while lending rates have been on monthly average of 14.7% the 90-day treasury bill rate has been on monthly average of 8.3% from January 2010-December 2022. On the other hand, inflation has been growing at around four basis points, on average. Government spending and public debt have been growing at an average of 6.4% and 1.3%, respectively.
Table 1. Summary of Descriptive Statistics.

lnFX

lnCPI

LR

CBR

Tbill

Debt

lnGS

count

156

156

156

156

156

156

156

Mean

4.573

4.448

14.707

9.143

8.269

1.334

6.421

Median

4.616

4.486

13.875

8.500

8.035

1.047

6.615

Maximum

4.812

4.860

20.340

18.000

21.650

8.234

8.014

Minimum

4.328

3.981

11.750

5.750

1.630

-6.084

3.582

Std. Dev.

0.116

0.244

2.476

2.719

3.126

1.693

0.986

Skewness

-0.180

-0.244

0.686

1.790

1.459

0.101

-0.846

Kurtosis

2.051

2.054

2.308

6.508

7.951

7.415

3.240

Jarque-bera

6.698

7.372

15.354

163.289

214.711

126.971

18.993

p-value

0.035

0.025

0.000

0.000

0.000

0.005

0.000

The stationary test presented in Table 2 shows that, apart from the 90-day Treasury bill, all other variables are nonstationary at level. However, upon differencing, all the variables become stationary or integrated in order I (1). All tests were performed using augmented Dickey-Fuller (ADF) tests.
Table 2. Stationarity Test Results.

ADF T-test at Level and 1st Difference

Critical Values

Decision

Test Statistic

p-value

1%

5%

10%

LnFX

Level

-1.0704

0.7267

-3.4731

-2.8802

-2.5768

Non-Stationary

1st Diff

-7.8174

0.0000

-3.4731

-2.8802

-2.5768

Stationary

lnCPI

Level

-1.1024

0.7143

-3.4731

-2.8802

-2.5768

Non-Stationary

1st Diff

-6.8860

0.0000

-3.4731

-2.8802

-2.5768

Stationary

LR

Level

-1.4252

0.5686

-3.4731

-2.8802

-2.5768

Non-Stationary

1st Diff

-10.0804

0.0000

-3.4731

-2.8802

-2.5768

Stationary

Tbill

Level

-3.4965

0.0093

-3.4737

-2.8805

-2.5769

Stationary

1st Diff

-6.2899

0.0000

-3.4737

-2.8805

-2.5769

Stationary

CBR

Level

-3.5196

0.0087

-3.4740

-2.8806

-2.5770

Stationary

1st Diff

-4.4124

0.0000

-3.4740

-2.8806

-2.5770

Stationary

LnGS

Level

-1.2519

0.6507

-3.4765

-2.8817

-2.5776

Non-Stationary

1st Diff

-4.5952

0.0000

-3.4765

-2.8817

-2.5776

Stationary

lnDebt

Level

0.9273

0.9957

-3.4765

-2.8817

-2.5776

Non-Stationary

1st Diff

-3.4114

0.0121

-3.4765

-2.8817

-2.5776

Stationary

4.2. Johansen Cointegration Test
The Johansen test was used to test the long-run relationships between several nonstationary time-series datasets. Given that all our variables are nonstationary at level, the Johansen test is applied to check for the existence of a long-run relationship. Johansen’s test has two main forms: trace and maximum eigenvalue. Table 3 in Appendix shows the trace and maximum eigne value test results, revealing the presence of long run relationship at 5% significance level.
Table 3. Cointegration Test Results.

Unrestricted Cointegration Rank (Test Trace)

Maximum Eigen Value

Hypothesized No of CE(s)

Eigen Value

Trace Statistics

0.05 Critical value

Prob.**

Max-Eigen Statistic

0.05 Critical value

Prob.**

None

0.446418

357.0602

125.6154

0.0000

88.7019

46.2314

0.0000

AT Most 1*

0.376038

268.3584

95.7537

0.0000

70.7499

40.0776

0.0000

AT Most 2*

0.344965

197.6085

69.8189

0.0000

63.4600

33.8769

0.0000

AT Most 3*

0.272773

134.1484

47.8561

0.0000

47.7776

27.5843

0.0000

AT Most 4*

0.202726

86.3709

29.7971

0.0000

33.9835

21.1316

0.0000

AT Most 5*

0.169100

52.3874

15.4947

0.0000

27.7868

14.2646

0.0000

AT Most 6*

0.151261

24.6006

3.8415

0.0000

24.6006

3.8415

0.0000

4.3. Granger Causality Tests
This study begins by analyzing Granger causality tests for the variables under study to establish the relationship between fiscal and monetary policies. The Granger Causality Results are reported based on the F-statistic and p-value. The Granger causality results, as indicated in Table 4, reveal bidirectional causality between foreign exchange and the central bank rate, while unidirectional causality exists between public debt from foreign exchange. This indicates that debt does not have causality in the forex. We also find no causality between the central bank rate, T-bill rate, and inflation. The lending rate results indicate unidirectional causality running from the central bank rate to the lending rates. Similarly, we find unidirectional causality running from the CBR rate to debt. This indicates that monetary policy is directed towards fiscal sustainability through debt. In addition, unidirectional causality runs from government spending towards the 91-day treasury bill. Considering that the 91-Treasury bill provides the direction of expected inflation, this could be an indication of government spending causing inflation. While we did not find evidence of government spending anger causing lending rates at 5% significance level, there exists unidirectional causality between government spending and lending rates at 10% significance level. This result differs from that of Uwilingiye & Gupta, who found unidirectional causality between the budget deficit Granger causes and interest rate .
4.4. Lag Order Selection
Owing to the limitations of Granger causality tests, the results of this method may not provide a true and complete picture of the relationship between variables. Granger causality accounts for only direct causality and indirect causality is not completely captured. Therefore, to account for indirect causality between the study variables, we consider a Structural Vector Autoregressive (SVAR) model and interpret our results using impulse responses.
Table 4. Granger Causality Test Results.

Null Hypothesis:

Obs

F-Statistic

Prob.

D(INF) does not Granger Cause D(LNFX)

152

1.80178

0.14950

D(LNFX) does not Granger Cause D(INF)

0.23293

0.87330

D(LR) does not Granger Cause D(LNFX)

152

2.68049

0.04910

D(LNFX) does not Granger Cause D(LR)

4.93997

0.00270

D(CBR) does not Granger Cause D(LNFX)

152

9.49789

0.00001

D(LNFX) does not Granger Cause D(CBR)

13.82110

0.00000

D(TBILL) does not Granger Cause D(LNFX)

152

1.68767

0.17230

D(LNFX) does not Granger Cause D(TBILL)

10.27280

0.00000

D(LNDEBT) does not Granger Cause D(LNFX)

152

1.47697

0.22330

D(LNFX) does not Granger Cause D(LNDEBT)

3.08426

0.02930

D(LNGS) does not Granger Cause D(LNFX)

152

0.94464

0.42080

D(LNFX) does not Granger Cause D(LNGS)

1.51737

0.21250

D(LR) does not Granger Cause D(INF)

152

0.41413

0.74310

D(INF) does not Granger Cause D(LR)

1.44593

0.23190

D(CBR) does not Granger Cause D(INF)

152

0.38782

0.76190

D(INF) does not Granger Cause D(CBR)

2.37438

0.07260

D(TBILL) does not Granger Cause D(INF)

152

1.95775

0.12300

D(INF) does not Granger Cause D(TBILL)

1.55676

0.20250

D(LNDEBT) does not Granger Cause D(INF)

152

1.72635

0.16420

D(INF) does not Granger Cause D(LNDEBT)

0.14922

0.93000

D(LNDEBT) does not Granger Cause D(INF)

152

1.72635

0.16420

D(INF) does not Granger Cause D(LNDEBT)

0.14922

0.93000

D(LNGS) does not Granger Cause D(INF)

152

1.06683

0.36520

D(INF) does not Granger Cause D(LNGS)

13.87780

0.00000

D(CBR) does not Granger Cause D(LR)

152

10.42710

0.00000

D(LR) does not Granger Cause D(CBR)

1.26867

0.28740

D(TBILL) does not Granger Cause D(LR)

152

4.87838

0.00290

D(LR) does not Granger Cause D(TBILL)

3.53640

0.01640

D(LNDEBT) does not Granger Cause D(LR)

152

2.37373

0.07270

D(LR) does not Granger Cause D(LNDEBT)

0.35092

0.78850

D(LNGS) does not Granger Cause D(LR)

152

2.14346

0.09730

D(LR) does not Granger Cause D(LNGS)

0.04058

0.98910

D(TBILL) does not Granger Cause D(CBR)

152

1.45393

0.22970

D(CBR) does not Granger Cause D(TBILL)

2.84073

0.04000

D(LNDEBT) does not Granger Cause D(CBR)

152

0.48993

0.68980

D(CBR) does not Granger Cause D(LNDEBT)

5.63882

0.00110

D(LNGS) does not Granger Cause D(CBR)

152

1.36522

0.25580

D(CBR) does not Granger Cause D(LNGS)

0.26713

0.84900

D(LNDEBT) does not Granger Cause D(TBILL)

152

1.88625

0.13450

D(TBILL) does not Granger Cause D(LNDEBT)

0.54622

0.65150

D(LNGS) does not Granger Cause D(TBILL)

152

3.19083

0.02550

D(TBILL) does not Granger Cause D(LNGS)

0.83750

0.47540

D(LNGS) does not Granger Cause D(LNDEBT)

152

2.35531

0.07440

D(LNDEBT) does not Granger Cause D(LNGS)

2.37795

0.07230

However, the lag order was determined before performing the SVAR test. The Likelihood Ratio (LR) test statistic, Akaike Information (AIC), Schwarz Bayesian (SC), Hannan-Quin (HQ), and Final Prediction Error (FPE) information criteria were used to determine the lag order. Table 5 indicates VAR models with one lag (SC: 1.14), two lags (HQ: 0.4757), and three lags (LR: 133.11, FPE: 1.14e-09, and AIC: -7.430). Therefore, we can choose lags 1, 2, and 3 as the best lag for the SVAR model. Usually, the Schwarz Information Criterion or Bayesian Information Criterion is relatively consistent compared with other models; however, when the stability tests were performed, only three lags were found to be stable. Therefore, we chose lag 3 as the appropriate lag.
Table 5. Lag Order Selection Test Results.

Lag

LogL

LR

FPE

AIC

SC

HQ

0

-68.8226

N/A

6.44e-09

1.00427

1.14415

1.0611

1

54.4075

233.4027

2.41e-09

0.02109

1.140084*

0.475685*

2

132.1918

140.1148

1.69e-09

-0.03602

1.73795

0.4922

3

210.1001

133.1149*

1.14e-09*

-0.074305*

2.33418

0.5071

4

247.0052

59.6348

0.0000

-0.5828

3.47349

1.0650

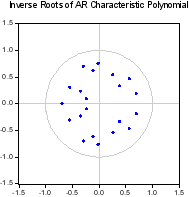
Figure 3. VAR stability test polynomial.
4.5. Stability Test
The stability test results, presented using the Inverse Roots of AR Characteristic Polynomial in Figure 3, indicate that all roots have moduli of less than one and lie inside the unit circle. Therefore, our SVAR model with three lags is stable, and further analysis can be conducted.
4.6. Serial Correlation Test
An autocorrelation test was performed using multivariate LM test statistics for the residual serial correlations of up to 12 lags. The LM test results shown in Table 6 indicate the absence of autocorrelation for the model with any of the lags saved at 11 and 12 lags.
Table 6. VAR serial correlation LM Test Results.

Null Hypothesi: No Serial Correlation at lag h

Lag

LRE*stat

df

Prob.

Rao F-stat

df

Prob.

1

53.2770

49

0.3131

1.09342

49,476.6

0.3146

2

63.0182

49

0.0860

1.30623

49,476.6

0.0868

2

45.8078

49

0.6033

0.93300

49,476.6

0.6047

4

41.4741

49

0.7688

0.84103

49,476.6

0.7698

5

37.3613

49

0.8879

0.75448

49,476.6

0.8885

6

54.5248

49

0.2725

1.12043

49,476.6

0.2739

7

38.5372

49

0.8587

0.77915

49,476.6

0.8594

8

55.8320

49

0.2336

1.14882

49,476.6

0.0235

9

51.4682

49

0.3774

1.05434

49,476.6

0.3789

10

51.8183

49

0.3645

1.06189

49,476.6

0.3660

11

86.3420

49

0.0008

1.83296

49,476.6

0.0008

12

106.8133

49

0.0000

2.3160

49,476.6

0.0000

4.7. Effect of Monetary Policy on Prices
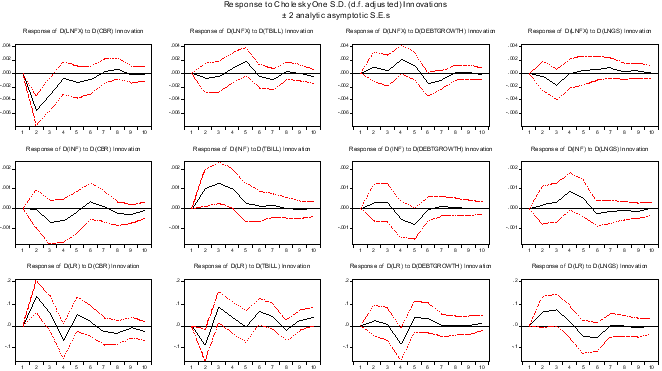
The effects of the fiscal policy variables are shown in Figure 4 columns 1 and 2 below show the impulse response. The results reveal that the Foreign Exchange rate is negatively affected after one standard deviation of innovation is applied to the Central bank rate (CBR) in the first period, before declining almost immediately in the second month. This implies that monetary policy tightening appreciated the Kenyan shillings. Graphically, there was a contraction in the forex rate as it gradually declined in the negative zone for almost four months before stabilizing in the sixth month when it approached zero. This would be a pointer in the direction of monetary policy towards stabilizing Kenyan currency. Similarly, CBR innovations reduce inflation, but after three months, they remain subdued for almost six months before stabilizing. However, lending rates have a positive effect on this situation. A one-standard-deviation shock on CBR induces a positive effect on lending rates in the second month before moving up and down between the fourth and sixth months when they stabilize. However, the impulse response function indicates that a shock to the 91-day treasury bill rate does not generate any inflation response. However, the response instantaneously moves upward positively to the second month before beginning to decline smoothly but remains positive until the sixth month when it fades out. This indicates the direction of expected inflation and does not directly affect T-bill-inducing inflation. This result is in agreement with Ahmed et al. who find that interest rates positively influence inflation.
4.8. Effect of Fiscal Policies on Prices
The effect of fiscal policy variables is shown in Figure 4 through impulse responses in columns three and four. The results reveal that one standard deviation of the expansionary fiscal policy significantly increases the price level for a period of about 3-4 months. The impulse response indicates that 1% shock to public debt impacts positively the foreign exchange rate, inflation, and lending rate. Similar results can be seen in the lending rate channel, where debt shocks induce positive effects, leading to higher interest rates. This indicates that public debt transmits not only inflationary pressure but also currency depreciation. This result agrees with those of Chemnyongoi & Kiriga and Osei & Ogunkola who posit that fiscal deficits are not only inflationary in nature but could lead to higher interest rates and, in the long run, could also lead to crowding out.
Impulse responses from government spending indicate that 1% standard deviation shock induces inflation from the second month and remains significantly high up to six months before it fades out. This could point to the fact that increased government spending induces more money into the economy; hence, consumers and businesses have more money, leading to more purchases, and businesses end up increasing prices.
Similarly, we see a 1% standard deviation innovation in government spending leads generates a positive response from the lending rate in the immediate period and remains positively high for a period of about four months before reducing drastically into the negative zone, moving up again, and decaying to zero from the sixth month. These results agree with those of eight other studies captured in literature which revealed that one standard deviation tightening in fiscal policy significantly reduces price levels, and thus, expansionary fiscal policy significantly increases prices By contrast, we find that increased government spending leads to Kenyan shilling appreciating significantly, albeit for only three months before beginning to depreciate and stabilize after month five. These results agree with those of Kim and Miyamoto et al. who reveal currency depreciation in response to increased government spending . This result is expected under the IS curve since the Kenyan economy is debt-financed, and therefore, increased government spending (fiscal policy) may act on the exchange rate through higher interest rates and expected high output. Therefore, this study makes a preliminary inference that fiscal policy dominates monetary policy because interest rates are determined by government borrowing rather than the declared monetary policy stance. However, these results are contrary to the study results by Murphy & Walsh who found no evidence of government spending causing interest rate rise.
Figure 4. Effect of Monetary and Fiscal policies to pricing dynamics.
4.9. Variance Decomposition Test
The forecast error variance Decomposition (FEVD) of a state-space model measures the volatility or movement proportionality that occurs due to its own shocks versus the shocks of other variables in that model. This study used periods 3 and 10 to represent short- and long-term periods, respectively.
The variance decompositions of the Foreign Exchange (lnFX) inflation rate (INF) and lending rate (LR) for SVAR estimation are presented in Tables 7, 8 and 9 respectively. The test results show that own shocks constituted the greatest source of fluctuation in the model, followed by shocks from central bank rate (CBR) and lending rates in the case of currency depreciation, while inflation own shocks constituted almost 92% in the short run, followed by 91-day treasury bill rate. A clear indication that the treasury bill rate can be used to provide direction for the expected inflation in the country. However, growth in public debt contributed a significant number of shocks to inflation, amounting to approximately 1.5% in the short run and almost 2% in the long run.
Table 7. Variance Decomposition: Monetary policy and fiscal effects on pricing dynamics (Foreign Exchange).

Variance Decomposition of D(LNFX):

Period

S.E.

D(LNFX)

D(INF)

D(LR)

D(CBR)

D(TBILL)

D(DEBT)

D(LNGS)

1

0.012504

100.0000

0.0000

0.0000

0.0000

0.0000

0.0000

0.0000

2

0.014415

80.98824

2.493298

2.081423

13.54122

0.39748

0.001216

0.497124

3

0.015256

72.42249

2.545559

3.692067

17.75489

1.281215

0.002963

2.300812

4

0.015733

68.2247

3.57398

5.949684

17.07473

1.329269

1.620658

2.226977

5

0.015867

67.67628

3.681618

6.103454

17.35377

1.339981

1.600205

2.244692

6

0.016031

67.14355

3.870116

6.214253

17.32973

1.483359

1.673191

2.285802

7

0.016081

67.02239

3.972126

6.192805

17.39221

1.483355

1.664624

2.272492

8

0.016099

66.93203

4.026245

6.187817

17.38002

1.514622

1.689735

2.269525

9

0.016126

66.75963

4.218568

6.206628

17.32325

1.5107

1.690574

2.290649

10

0.016135

66.70181

4.255382

6.208955

17.30374

1.521216

1.72084

2.288056

Table 8. Variance Decomposition: Monetary policy and fiscal effects on pricing dynamics (Inflation).

Variance Decomposition of D(INF):

Period

S.E.

D(LNFX)

D(INF)

D(LR)

D(CBR)

D(TBILL)

D(DEBT)

D(LNGS)

1

0.00533

1.00182

98.99818

0.00000

0.00000

0.00000

0.00000

0.00000

2

0.00628

1.35855

96.48416

0.00003

0.03485

1.39376

0.59461

0.13405

3

0.00650

1.38385

91.85972

0.27733

1.12945

3.69050

1.42484

0.23430

4

0.00663

1.50118

89.01266

0.29645

2.02386

4.40130

1.47004

1.29451

5

0.00669

1.97835

87.97067

0.53375

2.15463

4.33236

1.73005

1.30020

6

0.00674

2.52087

86.72390

0.92795

2.22002

4.32134

1.76792

1.51801

7

0.00676

2.84244

86.27624

1.03504

2.21029

4.29055

1.77580

1.56965

8

0.00678

2.88523

85.99447

1.09811

2.39297

4.28280

1.77184

1.57458

9

0.00679

2.88001

85.83130

1.14851

2.49298

4.30098

1.76514

1.58108

10

0.00680

2.89220

85.76011

1.19238

2.49733

4.28900

1.77976

1.58922

Table 9. Variance Decomposition: Monetary policy and fiscal effects on pricing dynamics.

Variance Decomposition of D(LR):

Period

S.E.

D(LNFX)

D(INF)

D(LR)

D(CBR)

D(TBILL)

D(DEBT)

D(LNGS)

1

0.40554

2.17165

0.09318

97.73517

0.00000

0.00000

0.00000

0.00000

2

0.45081

8.42214

1.33792

79.47168

8.27417

0.77846

0.53941

1.17622

3

0.49728

12.75509

1.42082

66.27567

10.36125

5.31019

0.45487

3.42210

4

0.51404

13.40856

1.36538

63.56868

10.05046

5.42110

2.79769

3.38814

5

0.52383

14.48724

1.64139

61.67754

9.73601

5.46997

3.18563

3.80223

6

0.53088

15.64995

1.61945

60.17883

9.56328

5.66001

3.18695

4.14154

7

0.53461

16.12349

1.66633

59.39255

9.92863

5.65328

3.14327

4.08775

8

0.53727

16.04370

1.85292

59.00016

10.07001

5.87303

3.11244

4.04768

9

0.54076

15.86600

2.65060

58.49392

9.96510

5.79824

3.09157

4.13457

10

0.54180

15.80503

2.81644

58.30571

9.94867

5.86659

3.13870

4.11887

With regard to lending rates, the variance decomposition indicates that own shock contributes about 66% in the short run, followed by foreign exchange fluctuation shocks of about 13% and CBR at 10%. The same trend occurs in the long run; only its own stock reduces to 58%, with foreign exchange rate shocks contributing about 15%, and CBR shocks remaining the same. Interestingly, we see a large contribution of almost 4% shock contribution from the fiscal space through to lending rates in the short run and 7% in the long run. These results reveal that fiscal policy shocks tend to manifest largely through inflation and lending rates in large portions in both the short and long run, whereas monetary policy shocks are largely transmitted through foreign exchange fluctuations.
5. Conclusion and Policy Recommendation
In conclusion, this study reveals significant interactions between monetary and fiscal policies and their effects on pricing dynamics in Kenya from January 2010 to December 2022. This study employs the Structural Vector Autoregressive (SVAR) model to investigate the existence of fiscal dominance in Kenya through pricing dynamics lens. The fiscal policy stance is proxied by public debt and government spending, whereas the monetary policy stance is proxied by the Central Bank rate (CBR). The 91-day Treasury bill rate was used as an element of both the fiscal and monetary policies. The empirical assessment in this study led to three broad and insightful conclusions as follows.
Monetary policy has a more limited and focused impact: Monetary policy, primarily through the central bank rate (CBR), affects the foreign exchange rate and, to a less extent, inflation. Specifically, monetary policy tightening appreciates the Kenyan Shilling. However, the 91-day treasury bill rate does not directly impact inflation movement. Results from the results reveal that monetary policy shocks affected foreign exchange (17%), more than inflation (2.5%) and lending rates (10%), a clear indication that monetary policy is largely manifested through foreign exchange. This result implies that the real target of the Central Bank of Kenya is to stabilize the exchange rate over inflation but with debt servicing costs in the hindsight.
Fiscal policy significantly influences pricing dynamics: The study reveals that expansionary fiscal policy, such as increased government spending and public debt, leads to higher inflation and lending rates. For instance, a 1% shock to public debt impacts positively the foreign exchange rate, inflation, and lending rate. This suggests that fiscal measures can exert pressure on monetary policy.
Fiscal dominance evidence: The findings indicate that fiscal policy plays a dominant role in shaping inflation and lending rates, suggesting the presence of fiscal dominance in Kenya, even though it does not appear to be a very high form of high fiscal dominance. Specifically, a 1% shock to public debt positively impacts inflation and lending rates. Government spending also induces inflation. Impulse responses from government spending indicate that 1% standard deviation shock induces inflation from the second month and remains significantly high up to six months before it fades out. These study results suggest that fiscal actions have a strong influence on inflation, a key indicator of price stability. This is further supported by the variance decomposition analysis, which shows that fiscal policy shocks have a substantial impact on inflation and lending rates in both the short and long run. Although CBK explicitly commits to a market-determined forex rate based on market activity, the results of this study reveal otherwise. Although this is not primarily a monetary policy concern, it stems from the desire to seek fiscal sustainability; hence, this would be a pointer of the monetary policy direction towards stabilizing Kenyan currency. This indicates a certain level of fiscal dominance.
Based on the results of this study, if fiscal policy becomes dominant and monetary policy plays a second fiddle to fiscal authority, then the multiplier effect may not be pleasant because this could be a “slow intrusion of fiscal policy into the monetary policy space.” A positive interplay between monetary policy and fiscal policy has many benefits for economic growth and price stability compared with fathom. Therefore, the findings of this study have several policy implications.
First, government spending must be re-examined to effectively reduce the deficit by reducing unnecessary expenditures while increasing revenue collection from all available channels. The economy can benefit from reduced interest rates by reducing spending. Direct spending on development projects, such as infrastructure, or socio-economic projects, such as education and health, have a higher impact on human capital. In addition, government spending should be directed toward productive sectors that support or influence growth. Second, the government should reduce domestic borrowing through the central bank or directly from commercial banks, as this not only crowds out investments but also leads to increased taxes and pushes up interest rates because markets are nervous about governments’ ability to repay, and most importantly, could interfere with monetary policy. Specifically, since public debt to inflation increases from the short run (1.5%) to the long run (2%) while contribution of fiscal space" (which is influenced by debt) to lending rates (4% in the short run, 7% in the long run), this study proposes a minimum of 7% of debt to GDP ratio reduction in order to bring down the cost of borrowing as well as stabilize prices. Third, there is a need to review the emergence of both transactional and financial dollarization in Kenya, which could be a recipe for inflation and local currency instability.
Fourth, there is also a need to review the monetary regime to establish whether there is a necessity for a regime change towards currency pegging, which remains an attractive option for policymakers in developing and emerging economies. Finally, the study suggests a review of fiscal policy and establishes whether there is a need for a Fiscal Policy Committee (FPC) within the National Treasury to mimic the Monetary Policy Committee. The Fiscal Policy Committee can have general oversight over existing directorates within the Treasury. Among other roles, the FPC should manage economic and fiscal policies, provide advice and guidance on government spending, and manage public debt, with an anchoring focus on fiscal sustainability. In addition, the FPC could collaborate with the MPC on various interconnected issues of economic growth and inflation to avoid intrusion by either policy while maintaining target levels.
Abbreviations

ADF

Augmented Dickey-Fuller tests

AFDB

African Development Bank

AIC

Akaike Information

ARDL

Autoregressive Distributed Lag

BIC

Bayesian Information Criterion

CBR

Central Bank Rate

CPI

Consumer Price Index

CRR

Cash Reserve Ratio

DSGE

Dynamic Stochastic General Equilibrium Models

FEVD

Forecast Error Variance Decomposition

FPC

Fiscal Policy Committee

FPE

Final Prediction Error

FTPL

Fiscal Theory of Price Level

GDP

Gross Domestic Product

GS

Government Spending

HQ

Hannan-Quin

IMF

International Monetary Fund

IT

Inflation Targeting

KES

Kenya Shilling

LM

Lagrange Multiplier

LR

Lending Rate

M2

Broad Money

MPC

Monetary Policy Committee

MSRDM

Multistage Risk Decision-Making

QTM

Quantity Theory of Money

SC

Schwarz Bayesian

SVAR

Structural Vector Autoregressive

Tbill

Treasury Bill

VAR

Vector Autoregressive Model

VECM

Vector Autoregressive Correction Model

Author Contributions
Caspah Lidiema is the sole author. The author read and approved the final manuscript.
Funding
The authors did not obtain any funding for this research.
Data Availability Statement
All data are included in the content of the paper.
Conflicts of Interest
The author declares no conflicts of interest.
References
[1] Ahmed, Rashad, Joshua Aizenman, and Yothin Jinjarak. "Inflation and exchange rate targeting challenges under fiscal dominance." Journal of Macroeconomics 67 (2021): 103281.
[2] AFDB (2023)
[3] Arora, S. (2018). Regime-switching monetary and fiscal policy rules and their interaction: an Indian case study. Empirical Economics, 54, 1573-1607.
[4] Bassetto, M. (2008). Fiscal theory of the price level. The New Palgrave Dictionary of Economics, 1-5.
[5] Bartsch, E., Bénassy-Quéré, A., Corsetti, G., & Debrun, X. (2020). It's All in the Mix: How Monetary and Fiscal Policies Can Work or Fail Together. Geneva ICMB International Center for Monetary and Banking Studies.
[6] Bordo, M. D., & Levy, M. D. (2021). Do enlarged fiscal deficits cause inflation? The historical record. Economic Affairs, 41(1), 59-83.
[7] Borio, C., & Disyatat, P. (2021). Monetary and Fiscal Policy: Privileged powers, entwined responsibilities. SUERF Policy Note, (238).
[8] Bucacos, E. (2022). The interdependence of Fiscal and Monetary Policies in an Emerging economy: The case of Uruguay. International Journal of Finance & Banking Studies (2147-4486), 11(1), 19-33.
[9] Canzoneri, M. B., Cumby, R. E., & Diba, B. T. (2001). Is the price level determined by the needs of fiscal solvency?. American Economic Review, 91(5), 1221-1238.
[10] Chemnyongoi, H., & Kiriga, B. (2020). Assessing the Sustainability of Fiscal Policy in Kenya. Kenya Institute for Public Policy Research and Analysis.
[11] Chibi, A., Benbouziane, M., & Chekouri, S. M. (2019, March). Interaction between monetary and fiscal policy: Empirical evidence from Algeria. In Economic Research Forum 25th Annual Conference. Kuwait, March, 10th-12th.
[12] Sims, C. A. (1980). Macroeconomics and reality. Econometrica: journal of the Econometric Society, 1-48.
[13] Davis, J. S., Fujiwara, I., & Wang, J. (2018). Dealing with time inconsistency: Inflation targeting versus exchange rate targeting. Journal of Money, Credit and Banking, 50(7), 1369-1399.
[14] Debrun, X., Masuch, K., Vansteenkiste, I., Ferdinandusse, M., von Thadden, L., Hauptmeier, S.,... & Penciu, A. (2021). Monetary-fiscal policy interactions in the euro area.
[15] Duodu, E., Baidoo, S. T., Yusif, H., & Frimpong, P. B. (2022). Money supply, budget deficit and inflation dynamics in Ghana: An empirical investigation. Cogent Business & Management, 9(1), 2043810.
[16] Eita, J. H., Manuel, V., Naimhwaka, E., & Nakusera, F. (2021). The impact of fiscal deficit on inflation in Namibia. Journal of central banking theory and practice, 10(1), 141-164.
[17] El-Khishin, S., & Kassab, D. (2021). Monetary-Fiscal Policy Interactions During Uncertainty Shocks: Evidence from Egypt. Economic Research Forum (ERF).
[18] Fakher, H. A. (2016). The empirical relationship between fiscal deficits and inflation (Case study: Selected Asian economies). Iranian Economic Review, 20(4), 551-579.
[19] Farmer, M. R., & Zabczyk, P. (2019). A requiem for the fiscal theory of the price level. International Monetary Fund.
[20] Gamber, E., & Seliski, J. (2019). The effect of government debt on interest rates. Congressional Budget Office.
[21] Christiano, L. J., Eichenbaum, M., & Evans, C. L. (1999). Monetary policy shocks: What have we learned and to what end?. Handbook of macroeconomics, 1, 65-148.
[22] Hirose, Y., Kurozumi, T., & Van Zandweghe, W. (2020). Monetary policy and macroeconomic stability revisited. Review of Economic Dynamics, 37, 255-274.
[23] Hooley, J., Nguyen, L., Saito, M., & Nikaein Towfighian, S. (2021). Fiscal Dominance in Sub-Saharan Africa Revisited.
[24] Ikikii, S. M. (2017) Effectiveness of Monetary Policy in Kenya. Public Policy and Administration Research ISSN 2224-5731(Paper) ISSN 2225-0972(Online) Vol. 7, No. 7.
[25] IMF. (2015). Evolving Monetary Policy Frameworks in Low-Income and Other Developing Countries. IMF Staff Report.
[26] Jacobson, M. M., Leeper, E. M., & Preston, B. (2019). Recovery of 1933 (No. w25629). National Bureau of Economic Research.
[27] Jeanne, O. (2012). Fiscal Challenges to Monetary Dominance in the Euro Area: A Theoretical Perspective". mimeo.
[28] Wolf, C. K. (2020). Svar (mis) identification and the real effects of monetary policy shocks. American Economic Journal: Macroeconomics, 12(4), 1-32.
[29] Jesus, D. P. D., Besarria, C. D. N., & Maia, S. F. (2020). The macroeconomic effects of monetary policy shocks under fiscal constrained: An analysis using a DSGE model. Journal of Economic Studies, 47(4), 805-825.
[30] Kamila, A. (2022). Fiscal dominance in India: an empirical estimation. Indian Economic Review, 57(1), 113-132.
[31] Kessy, P. (2011). Dollarization in Tanzania: empirical evidence and cross-country experience.
[32] Kim, S. (2015). Country characteristics and the effects of government consumption shocks on the current account and real exchange rate. Journal of International Economics, 97(2), 436-447.
[33] Leeper, E. M. (1991). Equilibria under ‘active’and ‘passive’monetary and fiscal policies. Journal of monetary Economics, 27(1), 129-147.
[34] Kumar, M. M. S., & Baldacci, M. E. (2010). Fiscal deficits, public debt, and sovereign bond yields. International Monetary Fund.
[35] Lubik, T. A. (2022). Analyzing Fiscal Policy Matters More Than Ever: The Fiscal Theory of the Price Level and Inflation. Richmond Fed Economic Brief, 22(39).
[36] Mangani, R. (2021). On fiscal dominance in Malawi. African Review of Economics and Finance, 13(1), 29-53.
[37] Mathu, M., Osoro, N., & Luvanda, E. (2018). An empirical analysis of the effects of fiscal deficit on Inflation Kenya. Journal of Economics and Sustainable Development, 9, 20.
[38] Mishchenko, S., Naumenkova, S., Mishchenko, V., Ivanov, V., & Lysenko, R. (2019). Growing discoordination between monetary and fiscal policies in Ukraine. Banks and Bank Systems, 14(2), 40.
[39] Miyamoto, W., Nguyen, T. L., & Sheremirov, V. (2019). The effects of government spending on real exchange rates: Evidence from military spending panel data. Journal of International Economics, 116, 144-157.
[40] Munir, K., & Riaz, N. (2019). Macroeconomic effects of fiscal policy in Pakistan: a disaggregate analysis. Applied Economics, 51(52), 5652-5662.
[41] Munir, K., & Riaz, N. (2020). Fiscal Policy, Macroeconomic Flux and Inflation Volatility in Pakistan. Journal of Applied Economics and Business Research, 10(4), 194-206.
[42] Murphy, D., & Walsh, K. J. (2022). Government spending and interest rates. Journal of International Money and Finance, 123, 102598.
[43] Mutuku, C. (2015 a). A Fiscal Reaction Function for Kenya. Kenya Institute for Public Policy Research and Analysis.
[44] Mutuku, C. (2015b). Assessing fiscal policy cyclicality and sustainability: A fiscal reaction function for Kenya. Journal of Economics Library, 2(3), 173-191.
[45] Nathan, M. M., & Jagongo, A. (2017). Monetary policy tools and inflation in Kenya. money, 7(1), 86-97.
[46] Nyakerario Misati, R., & Morekwa Nyamongo, E. (2012). Asset prices and monetary policy in Kenya. Journal of Economic studies, 39(4), 451-468.
[47] Ndung'u, N. S. (1999). Monetary and exchange rate policy in Kenya.
[48] Osei, V., & Ogunkola, E. O. (2022). Regime Effects of Fiscal Deficit Financing and Inflation Dynamics in Ghana. Theoretical Economics Letters, 12(1), 258-286.
[49] Sims, C. A. (1994). A simple model for study of the determination of the price level and the interaction of monetary and fiscal policy. Economic theory, 4, 381-399.
[50] Woodford, M. (1994). Monetary policy and price level determinacy in a cash-in-advance economy. Economic theory, 4(3), 345-380.
[51] Park, H., & Son, J. C. (2022). Dollarization, inflation and foreign exchange markets: A cross‐country analysis. International Journal of Finance & Economics, 27(3), 2724-2736.
[52] Patella, V., Bouabdallah, O., & Jacquinot, P. (2022). Euro Area Monetary and Fiscal Dominance: The Cases of France and Italy. Available at SSRN 4290234.
[53] Richard, K., Muriu, P., & Maturu, B. (2018). Relative effectiveness of monetary and fiscal policies on output stabilization in developing countries: evidence from Rwanda. Int J Econ Financ, 10(1), 220-232.
[54] Rother, P. (2004). Fiscal policy and inflation volatility. Available at SSRN 515081.
[55] Sanusi, K. A. (2020). Fiscal dominance and inflation: Evidence from Nigerian and South African’s experiences. Cogent Economics & Finance, 8(1), 1814508.
[56] Sanusi, K. A., Eita, J. H., & Meyer, D. F. (2021). Management of fiscal and monetary policies interdependence in South African economy: A Bayesian VAR approach. Journal of Contemporary Management, 18(2), 86-113.
[57] Sanya, O. (2021). “Fiscal Dominance and Monetary Policy Effectiveness in Sub-Saharan Africa.” IOSR Journal of Economics and Finance (IOSR-JEF), 12(1).
[58] Sargent, T. J., & Wallace, N. (1981). Some unpleasant monetarist arithmetic. Federal reserve bank of minneapolis quarterly review, 5(3), 1-17.
[59] Strong, C., & Yayi, C. (2021). Central bank independence, fiscal deficits and currency union: Lessons from Africa. Journal of Macroeconomics, 68, 103313.
[60] Stupak, J. M. (2019). Fiscal policy: economic effects. Congressional Research Service, 1-8.
[61] Taiebnia, A., Mehrara, M., & Pourmohammad Gelsefidi, S. H. (2020). The Fiscal Dominance through Banking System: A Case Study on the Relationship between Government and Banking System in Iran’s Economy. Iranian Economic Review, 24(3), 853-883.
[62] Thornton, J., 2016. Inflation targeting in developing countries revisited. Finance Research Letters, 16, 145-153.
[63] Uwilingiye, J., & Gupta, R. (2009). Temporal causality between budget deficit and interest rate: the case of South Africa. The Indian Economic Journal, 57(2), 79-96.
[64] Visco, I. (2022). Monetary policy and inflation: recent developments.
[65] Yasmin, F., Urooge, S., Umair, M., & Ali, S. (2021). Revisiting the dynamic impact of fiscal policy on inflation in Pakistan. Journal of Accounting and Finance in Emerging Economies, 7(2), 349-356.
[66] Were, M., Nyamongo, E., Kamau, A. W., Sichei, M. M., & Wambua, J. (2014). Assessing the effectiveness of monetary policy in Kenya: Evidence from a macroeconomic model. Economic modelling, 37, 193-201.
[67] Brunnermeier, M. K. (2023). Policy in a changing world. Finance and Development, 60(1), 4-9.
[68] Altunbaş, Y., & Thornton, J. (2022). Does inflation targeting increase income inequality?. Journal of Post Keynesian Economics, 45(4), 558-580.
[69] Mohamoud, A. M. (2023). The Effects of Dollarization on Local Currency in Somalia. Multidisciplinary Journal of Horseed International University (MJHIU), 1(2), 24-34.
[70] Blanchard, O., & Perotti, R. (2002). An empirical characterization of the dynamic effects of changes in government spending and taxes on output. the Quarterly Journal of economics, 117(4), 1329-1368.
[71] Mountford, A., & Uhlig, H. (2009). What are the effects of fiscal policy shocks?. Journal of applied econometrics, 24(6), 960-992.
[72] Romer, C. D., & Romer, D. H. (2010). The macroeconomic effects of tax changes: estimates based on a new measure of fiscal shocks. American economic review, 100(3), 763-801.
[73] Mertens, K. R., & Ravn, M. O. (2014). Fiscal policy in an expectations-driven liquidity trap. The Review of Economic Studies, 1637-1667.
Cite This Article
  • APA Style

    Lidiema, C. (2025). Monetary-Fiscal Policy Interdependence and Pricing Dynamics: Empirical Estimation of Fiscal Dominance in Kenya. Journal of World Economic Research, 14(1), 61-79. https://doi.org/10.11648/j.jwer.20251401.16

    Copy | Download

    ACS Style

    Lidiema, C. Monetary-Fiscal Policy Interdependence and Pricing Dynamics: Empirical Estimation of Fiscal Dominance in Kenya. J. World Econ. Res. 2025, 14(1), 61-79. doi: 10.11648/j.jwer.20251401.16

    Copy | Download

    AMA Style

    Lidiema C. Monetary-Fiscal Policy Interdependence and Pricing Dynamics: Empirical Estimation of Fiscal Dominance in Kenya. J World Econ Res. 2025;14(1):61-79. doi: 10.11648/j.jwer.20251401.16

    Copy | Download

  • @article{10.11648/j.jwer.20251401.16,
      author = {Caspah Lidiema},
      title = {Monetary-Fiscal Policy Interdependence and Pricing Dynamics: Empirical Estimation of Fiscal Dominance in Kenya
    },
      journal = {Journal of World Economic Research},
      volume = {14},
      number = {1},
      pages = {61-79},
      doi = {10.11648/j.jwer.20251401.16},
      url = {https://doi.org/10.11648/j.jwer.20251401.16},
      eprint = {https://article.sciencepublishinggroup.com/pdf/10.11648.j.jwer.20251401.16},
      abstract = {This study examined the effectiveness of monetary and fiscal policies in establishing fiscal dominance in Kenya. This study employed monthly data from January 2010 to December 2022. Using Structural Vector Autoregressive (SVAR) model, this study captures price dynamics through three channels: foreign exchange, inflation, and lending rates. All the data were obtained from the Central Bank of Kenya Online Repository. The empirical assessment led to three broad and insightful conclusions. First, from the policy front, monetary policy is not fully effective in controlling and stabilizing prices. Second, expansionary fiscal policy is not only inflationary but also leads to higher interest rates. Third, there are traces of fiscal dominance, even though it’s not a very high form of fiscal dominance (which this study calls the slow intrusion of fiscal policy into the monetary policy space). Therefore, the study concludes that while fiscal dominance may not be very pronounced, there is a need to review the interplay between monetary and fiscal policies to fully gain from the interdependence of the two policies by stabilizing prices, enhancing growth as expected, and avoiding the macro-economic instability that comes with fiscal dominance. The study recommends reducing government borrowing, especially domestic borrowing, cutting unnecessary spending, directing spending towards development projects such as infrastructure and sectors that support growth, establishing the necessity of currency pegging to avoid unpleasant multiplier effects on fiscal dominance, reviewing the emergence and effects of dollarization in Kenya, and finally reviewing fiscal policy and establishing a Fiscal Policy Committee (FPC).
    },
     year = {2025}
    }
    

    Copy | Download

  • TY  - JOUR
    T1  - Monetary-Fiscal Policy Interdependence and Pricing Dynamics: Empirical Estimation of Fiscal Dominance in Kenya
    
    AU  - Caspah Lidiema
    Y1  - 2025/05/09
    PY  - 2025
    N1  - https://doi.org/10.11648/j.jwer.20251401.16
    DO  - 10.11648/j.jwer.20251401.16
    T2  - Journal of World Economic Research
    JF  - Journal of World Economic Research
    JO  - Journal of World Economic Research
    SP  - 61
    EP  - 79
    PB  - Science Publishing Group
    SN  - 2328-7748
    UR  - https://doi.org/10.11648/j.jwer.20251401.16
    AB  - This study examined the effectiveness of monetary and fiscal policies in establishing fiscal dominance in Kenya. This study employed monthly data from January 2010 to December 2022. Using Structural Vector Autoregressive (SVAR) model, this study captures price dynamics through three channels: foreign exchange, inflation, and lending rates. All the data were obtained from the Central Bank of Kenya Online Repository. The empirical assessment led to three broad and insightful conclusions. First, from the policy front, monetary policy is not fully effective in controlling and stabilizing prices. Second, expansionary fiscal policy is not only inflationary but also leads to higher interest rates. Third, there are traces of fiscal dominance, even though it’s not a very high form of fiscal dominance (which this study calls the slow intrusion of fiscal policy into the monetary policy space). Therefore, the study concludes that while fiscal dominance may not be very pronounced, there is a need to review the interplay between monetary and fiscal policies to fully gain from the interdependence of the two policies by stabilizing prices, enhancing growth as expected, and avoiding the macro-economic instability that comes with fiscal dominance. The study recommends reducing government borrowing, especially domestic borrowing, cutting unnecessary spending, directing spending towards development projects such as infrastructure and sectors that support growth, establishing the necessity of currency pegging to avoid unpleasant multiplier effects on fiscal dominance, reviewing the emergence and effects of dollarization in Kenya, and finally reviewing fiscal policy and establishing a Fiscal Policy Committee (FPC).
    
    VL  - 14
    IS  - 1
    ER  - 

    Copy | Download

Author Information
  • Abstract
  • Keywords
  • Document Sections

    1. 1. Introduction
    2. 2. Review of the Literature
    3. 3. Methodology
    4. 4. Empirical Findings and Discussion
    5. 5. Conclusion and Policy Recommendation
    Show Full Outline
  • Abbreviations
  • Author Contributions
  • Funding
  • Data Availability Statement
  • Conflicts of Interest
  • References
  • Cite This Article
  • Author Information