Abstract
The objective of this work is to study the effects of public investments on the inclusiveness of growth in Sub-Saharan Africa. The question of the inclusiveness of growth is rekindling the debate around economic policies aimed at reducing inequalities, combating poverty and promoting sustainable development. To lift the majority of Africans out of poverty, growth must be more inclusive. Job opportunities must be created by improving the business environment and the investment climate that will allow the private sector to flourish. Most importantly, landlocked areas must be linked to growth poles through better infrastructure and greater regional integration, both within countries and across national borders. Inclusive growth will also require the effective transformation of the continent's natural wealth into created wealth, in particular by strengthening human capital. Wise, efficient and sustainable management of natural resources that benefits all Africans. The data used in this research are from secondary sources and cover 21 SSA countries over the period 2000-2020. With reference to the existing literature, three indicators have been used to capture inclusive growth. We used an indicator called the inclusive growth index, which has two dimensions: income growth and income distribution. The other two indicators are poverty and productive employment. Public investment is measured by general government gross fixed capital formation as a percentage of GDP. The econometric approach is based on panel regressions. The results of the various estimates show that public investments have a significant and negative impact on the inclusive growth index and on productive employment. Furthermore, no significant effect of public investments was found on poverty. This research thus shows that public investments have a negative impact on inclusive growth in SSA.
Keywords
Inclusive Growth, Public Investments, Poverty, Inequalities, Productive Employment
1. Introduction
Africa has seen a resurgence in economic growth over the last two decades. According to the IMF, the growth rate has risen from around 2% in the 1980s and 1990s to an annual average of around 5% between 2000 and 2020. This rate is higher than that of Latin America and the Caribbean (2.8%) but remains lower than the average for Asia (7.2%) (OECD, 2018)
| [45] | Organisation for Economic Co-operation and Development (2018), ‘Effective public investment for inclusive and sustainable territorial development’ in Morocco-OECD dialogue on territorial development policies: Issues and Recommendations for Coordinated Public Action, OECD Publishing, Paris. |
[45]
. At regional level, economic performance has been remarkable in Sub-Saharan Africa (SSA) with an average annual growth rate of 5% according to World Bank statistics. Such progress is encouraging if it is accompanied by an improvement in people's living conditions, an increase in productivity, protection for the most vulnerable populations, the provision of productive employment and a reduction in inequalities. However, trends in poverty and inequality have not kept pace with this strong economic growth, as the rates of these socio-economic variables remain worryingly high, and insecure employment also persists. More than half the population of SSA is affected by extreme poverty and this sub-region concentrates 56% of extremely poor people in the world (World Bank, 2018)
| [61] | World Bank (2018). ‘Poverty and shared prosperity report 2018: completing the poverty puzzle’. |
[61]
.
In addition to poverty, the region is also one of the most unequal in the world, with the highest levels of inequality. According to a study by the International Monetary Fund (2015)
| [28] | International Monetary Fund (2007). «Globalization and inequality». World Economic Outlook, Chapter 4, October, washington DC. |
[28]
, income distribution is more unequal in Sub-Saharan Africa than in any other region in the world, with the exception of Latin America and the Caribbean. Inequality is increasing, with a small minority becoming richer while the proportion of poor people continues to rise, depriving the poor of the benefits of growth. This disparity in distribution certainly has consequences and is therefore a cause for concern. The literature has shown that high levels of inequality are detrimental to socio-economic and political development.
High levels of inequality also limit the impact of growth on poverty (Datt and Ravallion, 1992
| [19] | Datt, G. & Ravallion, M. (1992), Growth and Redistribution Components of Changes in Poverty Measures: A decomposition with applications to Brasil and India in 1980s. Journal of Development Economics, 38 (1992) 275-295. |
[19]
; Dollar and Kraay, 2002
| [20] | Dollar, D. & Kraay, A. (2002), «Growth is good for the poor». Journal of Economic Growth 7(3), 195-225. |
[20]
; Adams, 2004
). According to Arjan de Haan, Social Development Adviser at the UK's Department for International Development, ‘inequalities, particularly in income and between the sexes, are even likely to slow down growth, thereby indirectly compromising the fight against poverty in the world’. Income inequalities are said to deprive the poorest sections of society of access to health services and, above all, to quality education (Galor and Zeira, 1993
| [23] | Galor, O. & Zeira, J. (1993), «Income Distribution and Macroeconomics». Review of Economic Study, 60(1), 35-52. |
[23]
; Perotti, 1993
| [50] | Perotti, R. (1993), «Political Equilibrium, Icome Distribution and Growth». Review of Economic Studies, 60 (4), 755-776. |
[50]
). In terms of job quality, economic growth in SSA is driven by the dynamism of a formal production sector that employs less than half the workforce. Almost 70% of the workforce in SSA is concentrated in the informal sector (ILO, 2019)
, where jobs are precarious and vulnerable.
SSA also suffers from the problem of in-work poverty, with 38.1% of working poor. In view of the above statistics, it is worth asking about the quality of growth in SSA. This concern was initially addressed in the triangular relationship between Bourguignon (2004)
| [13] | Bourguignon, F. 2004), «The Social Consequences of economic Growth» Forthcoming in the Handbook of Economic Growth, Aghion and Durlauf, editors, Amsterdam. Elsevier. |
[13]
and pro-poor growth theories. Pro-poor growth theory translates the triangular relationship's assessment of growth quality algebraically. In the broadest sense, pro-poor growth is defined as growth leading to poverty reduction (United Nations, 2000)
| [60] | UN (2000). United Nations Millennium Declaration. 55/2 (PDF). United Nations General Assembly. |
[60]
. The United Nations (UN), through the Sustainable Development Goals (SDGs), has already emphasised the importance of achieving inclusive growth. In addition to the interest shown by the international community, inclusive growth has given rise to a great deal of reflection among researchers. Aoyagi and Ganelli (2015)
| [10] | Aoyagi, C. & Ganneli, G. (2015), «Asia’s quest for inclusive growth revisited». Journal of Asian Economics, 40, 29-46. |
[10]
analyse the determinants of inclusive growth in Asia and show that redistributive tax policies play a positive role in promoting inclusive growth.
In the context of Sub-Saharan Africa, Cha'ngom and Tamokwe (2019)
| [17] | Cha’Ngom, N. & Tamokwe, P. G. B. (2019), «Do migrant remittances contribute to inclusive growth in Sub-Saharan Africa?’ Munich Personal RePEc Archive, No. 91321. |
[17]
show that Migrant Remittances (MTRs) contribute to growth inclusiveness. According to them, a 10% increase in MFTs would lead, all other things being equal, to a 1.4% improvement in growth quality. Raheem et al. (2018)
| [52] | Raheem, I. D., Isah, K. O. & Adedeji, A. A. (2018), « Inclusive growth, human capital development and natural resource rent in SSA». Econ Change Restruct 51, 29-48. |
[52]
examined the possibility of achieving inclusive growth by increasing public spending on health and education. They found that human capital development through education and healthcare spending positively and significantly promotes inclusive growth. In the same context, Oyinlola et al. (2019)
| [48] | Oyinlola, M. A., Adedeji, A., Bolarinwa, M. O., Olabisi, N. (2019). «Governance, domestic resource mobilization, and inclusive growth in Sub-saharan Africa». Economic Analysis and Policy. 65. https://doi.org/10.1016/j.eap.2019.11.006 |
[48]
showed a positive and significant impact of governance on inclusive growth and suggest that the role of governance is essential for meaningful growth in SSA.
Calderon and Chang (2004)
| [15] | Calderón, C. and Chong, A. (2004), "Volume and Quality of Infrastructure and the Distribution of Income: An Empirical Investigation." Review of Income and Wealth. 50, 87-105. |
[15]
show a negative relationship between the level of infrastructure development and income inequality in a sample of 101 countries over the period 1960-1995. Improved access to infrastructure encourages the establishment of small non-agricultural businesses selling food products, transport and trade (Fan, 2004)
| [22] | Fan, S. (2004), ‘Public investment and poverty: initial evidence from East Africa and policy implications for West Africa’. Institut d'Economie Rurale (IER), Bamoko. |
[22]
. With this in mind, the study focuses on the following main question: what are the effects of public investment on inclusive growth in SSA? The rest of the work is divided into four parts, plus the conclusion. The first part summarises the empirical work. The second part deals with the methodology and the third presents the results and interpretations.
2. Literature Review
2.1. The Theoretical Framework of the Study
Pro-poor growth and inclusive growth share the same objective, which is to reduce poverty. Some authors even tend to confuse the two concepts, even though they are different. While pro-poor growth is limited to income outcomes, inclusive growth is concerned with the process of growth, i.e. the way in which growth takes place. Ali and Son's measure (2007)
| [5] | Ali, I. (2007), «Pro-Poor to Inclusive Growth: Asian Prescriptions». ERD Policy Briefs, Manila: Asian Development Bank, No. 48. |
[5]
. They introduce the idea of a social opportunity function, which is similar to a social welfare function, to measure inclusive growth. This function depends on two factors: i) the average opportunities available to the population and ii) how opportunities are shared within the population. Inclusive growth leads to the maximisation of the social opportunity function, and this function gives greater weight to the opportunities enjoyed by the poor: the poorer a person is, the greater the weight given to them. Such a weighting system will ensure that the opportunities created for the poor are greater than those created for the non-poor, i.e. if the opportunity of a less poor person is transferred to a poorer person in society, then social opportunities should increase, making growth more inclusive.
Over the last few decades, many studies have prioritised strong economic performance as a means of reducing poverty and inequality. The Kuznets model (1955)
| [36] | Kuznets, S. (1955), «Economic growth and income inequality». American Economic Review, 65(1): 1-28. |
[36]
and the trickle-down theory are part of this approach.
The Kuznets model establishes a relationship between income inequality and the level of development. It states that at the first stage of development, growth produces inequality, after which there is a turning point after which inequality decreases as the level of GDP per capita increases.
The trickle-down theory puts forward the idea that the benefits of growth flow from the richest to the poorest. In fact, the incidence of poverty can decrease with growth, so we need to create the conditions for the strongest possible growth. This theory is supported by Dollar and Kraay (2002)
| [20] | Dollar, D. & Kraay, A. (2002), «Growth is good for the poor». Journal of Economic Growth 7(3), 195-225. |
[20]
, who demonstrate that growth is good for the poor whatever the nature of that growth.
2.2. The Theory of Pro-Poor Growth
The early 1990s saw the emergence of a strand of literature concerned with ensuring that the poor actually benefit from growth: the theory of pro-poor growth. It is based on the idea that growth is not intrinsically pro-poor, so growth processes need to be calibrated towards the poor. The OECD (2007)
| [44] | Organisation for Economic Co-operation and Development (2007), «Vers une croissance pro-pauvre: orientation à l’intention des donneurs» ISBN 978-92-64-02479-3. |
[44]
states that ‘to be rapid and sustained, poverty reduction must be based on pro-poor growth, i.e. growth whose pace and terms improve the ability of poor men and women to participate in and benefit from economic activity’. Kakwani and Pernia (2000)
| [30] | Kakwani, N., & Pernia, E. (2000), «What is Pro-poor Growth?». Asian Development Review, 18(1), 1–16. |
[30]
argue that pro-poor growth strategies need to be promoted so that the poor benefit more than the rich.
According to the relative approach, growth is said to be pro-poor when the income of the poor grows more, relative to that of the non-poor (Kakwani and Pernia, 2000)
| [30] | Kakwani, N., & Pernia, E. (2000), «What is Pro-poor Growth?». Asian Development Review, 18(1), 1–16. |
[30]
, and according to the absolute approach, growth is said to be pro-poor if it results in a reduction in poverty (Ravallion and Chen, 2003)
| [54] | Ravallion, M. & Chen, S. (2003). «Measuring pro-poor growth». Economics Letters, 78(1), 93–99. |
[54]
. Osmani (2005)
| [46] | Osmani, C. (2005), «Defening pro-poor growth». Washington One pager 9, january, International Poverty Center, UNDP. |
[46]
combines the two approaches and argues that growth is pro-poor if it reduces both poverty and inequality. There are several measures of pro-poor growth and each measure depends on the choice of definition. Following the absolute approach, we have the measure of pro-poor growth using the growth impact curve proposed by Ravallion and Chen (2003)
| [54] | Ravallion, M. & Chen, S. (2003). «Measuring pro-poor growth». Economics Letters, 78(1), 93–99. |
[54]
. Following the relative approach, McCulloch and Bauleh (1999)
| [38] | Mc Culloch, N. and Baulch, B. (1999). «Assessing the poverty bias of economic growth: Methodology and an application to andhra pradesh and uttar pradesh». Institute of development studies working paper, University of sussex, United Kingdom draft. |
[38]
establish a measure they call the poverty bias of growth. The pro-poor growth index (PPGI) established by Kakwani and Pernia (2000)
| [30] | Kakwani, N., & Pernia, E. (2000), «What is Pro-poor Growth?». Asian Development Review, 18(1), 1–16. |
[30]
also makes it possible to assess the quality of growth using this approach. Despite the interest in the theory, a number of limitations have been raised. It has been criticised for focusing solely on the impact of growth on poverty, independently of inequalities Ali (2007)
| [5] | Ali, I. (2007), «Pro-Poor to Inclusive Growth: Asian Prescriptions». ERD Policy Briefs, Manila: Asian Development Bank, No. 48. |
[5]
, and for failing to answer the question of whether or not the poor have participated in the growth process in order to reap the benefits (Ningaye, 2017)
| [42] | Ningaye, P. (2017), «Role of microfinance in financing inclusive growth in Africa- case of Cameroon». Proceedings of the Fifth Congress of African Economists, Vol. 2, 166-181. |
[42]
. Inclusive growth theory complements this theory.
2.3. The Theory of Inclusive Growth
The concept of inclusive growth emerged in the midst of debates on pro-poor growth. The use of the term inclusive to characterise episodes of growth dates back to the turn of the century when Kakwani and Pernia (2000)
| [30] | Kakwani, N., & Pernia, E. (2000), «What is Pro-poor Growth?». Asian Development Review, 18(1), 1–16. |
[30]
used it to highlight the nature of what they considered to be pro-poor growth. The basic idea behind the theory is that economic growth alone cannot reduce poverty and inequality or create jobs if it is not sustainable and does not benefit everyone. With this in mind, the concept of inclusive growth has become the ideal framework for national and international policy-making. Some authors focus on the idea that for growth to be sustainable and effective in reducing poverty, it must be inclusive in nature (Berg and Ostry, 2011
| [11] | Berg, A. & Ostry, D. J. (2011), «Equality and efficiency». Finance et Développement, International Monetary Fund, 48(3). |
[11]
; Kraay, 2004
| [35] | Kraay, A. (2004), «When is growth pro-poor?». Cross-Country Evidence. IMF working paper No. 04/47. |
[35]
). Adeosun et al. (2020)
| [2] | Adeosun, O. A., Olomola, P. A., Adedokun, A., Ayodele, O. S. (2020), Public investment and inclusive growth in Africa. International Journal of Social Economics, 47(12), 1669-1691. |
[2]
acknowledge that these concepts of pro-poor and inclusive growth overlap. However, inclusive growth was the better concept as it was more broad-based, covering a broader swathe of the population while seeking to reduce poverty and inequality through expanding economic opportunities. The Commission on Growth and Development (2008)
| [18] | Commission on Growth and Development (2008), «Rapport sur la croissance: stratégie pour une croissance durable et un développement inclusif». Washington, DC, Banque mondiale. |
[18]
notes that inclusiveness - a concept that encompasses fairness, equality of opportunity and protection in market and employment transitions - is a key ingredient in any successful growth strategy. There are several definitions and ways of measuring inclusive growth that are not unanimously accepted in the literature (Ali and Son, 2007a
| [6] | Ali, I., & Son, H. H. (2007a), «Measuring inclusive growth». Asian Development Review, 24(1), 11-31. |
[6]
; Anand et al., 2013
| [9] | Anand, R., Mishra, S., & Peiris, S. J. (2013), «Inclusive Growth: measurements and determinants. International Monetary Fund, Washington, DC, Vol. 13. |
[9]
; McKinley, 2010
| [39] | McKinley, T. (2010), «Inclusive growth criteria and indicators: an inclusive growth index for diagnosis of country progress». ADB Sustainable Development Working Paper, No. 14, Banque asiatique de développement, Mandaluyong City (Philippines). |
[39]
; Ramos et al., 2013
| [53] | Ramos, R. A., Ranieri, R., Lammens, J. W. (2013), «Mapping Inclusive Growth». IPC-IG Working Paper, N°105. International Policy Centre for Inclusive Growth, Brasília. |
[53]
). However, the concept generally refers to growth that offers all sections of society the opportunity to participate in the achievement of economic performance while guaranteeing equal access to the opportunities created. It has the power to reduce poverty and inequality and create productive jobs.
2.4. Review of Empirical Work
Zulfiqar (2018)
| [62] | Zulfiqar, k. (2018). «Fiscal policy for inclusive growth: A case study of Pakistan». Pakistan Economic and Social Review, 56(1), 21-4. |
[62]
analyses the role of fiscal policy in promoting inclusive growth in Pakistan over the period from 1980 to 2010. Using a VAR approach, the results suggest a positive link between fiscal policy and inclusive growth but this link turns out to be weak. Jalles and de Mello (2019)
| [29] | Jalles, J. T., de Mello, L. (2019), «Cross-country evidence of the determinants of inclusive growth episodes ». Review of Development Economics 23(4) 1818-1839. |
[29]
find over the period 1980 to 2013 for a sample of 78 countries using probit and multinomial logit estimates that the redistributive potential of tax benefit systems and human capital accumulation are important determinants of inclusive growth.
Kolawole (2016)
| [34] | Kolawole, B., O. (2016), «Government spending and inclusive growth relationship in Nigeria: An empirical investigation». Zagreb International Review of Economics and Business, 19 (2), 33-56. |
[34]
examines the relationship between public expenditure especially public expenditure on education and health on inclusive growth in Nigeria over the period 1995 to 2014. Using the ARDL (Auto-Regressive Distributed Lag) method, the study reveals that public spending on health in the long term has a significant influence on inclusive growth. Indeed, a variation of 100% in health spending improves the inclusiveness of growth by 1.5%. He concludes that public spending in the form of redistributive spending on health propels inclusive growth in Nigeria.
Sanjaya and Nursechafia (2016)
| [55] | Sanjaya, I. M. & Nursechafia (2016), «Financial inclusion and inclusive growth: A cross- province analysis in Indonesia ». Buletin of Monetary, Economics Banking, vol 18, No. 3. |
[55]
in the context of Indonesia calculate and analyse the degree of financial inclusion and inclusive growth and seek to establish a correlation between financial inclusion and inclusive growth for a sample of 33 provinces. To calculate the degree of financial inclusion, they use the financial inclusion index proposed by Sarma (2012)
| [56] | Sarma, M. (2012), Index of financial inclusion: A measure of financial sector inclusiveness, Working Paper No. 07/2012. Berlin Working Papers on Money, Finance, Trade and Development, Berlin. |
[56]
which takes into account three dimensions (accessibility, availability and use) and to measure inclusive growth they use the inclusive growth index developed by Ali and Son (2007b)
| [7] | Ali, I., & Son, H. H. (2007b), «Defining and measuring Inclusive Growth: application to the philippines». ERD working paper series, No. 98 Asian Development Bank ADB. |
[7]
. To establish the relationship between financial inclusion and inclusive growth, the study plots financial inclusion and inclusive growth indices across the economy over time. The results show a positive slope for both indices, implying that there is a positive correlation between the two indices. They conclude that improving financial inclusion could positively encourage inclusive growth.
Oyinlola et al. (2021)
| [49] | Oyinlola, M. A., Adedeji, A. A., & Onitekun, O. (2021). Human capital, innovation, and inclusive growth in Sub-Saharan African Region. Economic Analysis and Policy, 72, 609-625. |
[49]
investigated the nexus of human capital, innovation, and inclusive growth in sub-Saharan Africa, employing a fixed-effects model across 17 countries from 1998 to 2014. Their findings highlighted a positive correlation between human capital, innovation, and inclusive growth. However, they also identified a negative indirect impact of human capital through innovation, suggesting constraints in promoting technological advancement. In a similar vein, Khan et al. (2020)
| [32] | Khan, M. S., Senhadji, A. S. (2000), Threshold effects in the relationship between inflation and growth, IMF Working Paper, WP/00/110. |
[32]
delved into the impact of human capital development on inclusive growth in developing countries using panel data from 2000 to 2014. Their study unveiled that augmenting human capital positively affected economic growth, employment, while concurrently reducing income inequality and poverty. This underscores the imperative of bolstering human capital development to foster inclusive growth in developing nations.
Similarly, Raheem et al. (2018)
| [52] | Raheem, I. D., Isah, K. O. & Adedeji, A. A. (2018), « Inclusive growth, human capital development and natural resource rent in SSA». Econ Change Restruct 51, 29-48. |
[52]
explored the impact of government expenditure on education and health on inclusive growth in sub-Saharan Africa. Their research advocated for increased investment in health, especially when coupled with natural resources, to significantly contribute to inclusive growth. This underscores the significance of directing resources towards health and education to realize inclusive growth objectives in the region. Raheem et al (2018)
| [52] | Raheem, I. D., Isah, K. O. & Adedeji, A. A. (2018), « Inclusive growth, human capital development and natural resource rent in SSA». Econ Change Restruct 51, 29-48. |
[52]
also find in the same study, using a fixed effect model on a panel of 18 SSA countries that FDI has a positive impact on inclusive growth such that a 100% change in FDI leads to a 29.3% change in inclusiveness. Zulfikar (2018)
| [62] | Zulfiqar, k. (2018). «Fiscal policy for inclusive growth: A case study of Pakistan». Pakistan Economic and Social Review, 56(1), 21-4. |
[62]
notes in the context of Pakistan that GFCF has a positive impact on inclusive growth such that a 100% increase in GFCF increases the inclusiveness of growth by 3% but direct and indirect taxes lead to a reduction in inclusiveness so they are deemed not conducive to the inclusion process.
Hussein et al. (2018)
| [25] | Hussein, K., Mukungu, A., & Awel, Y. (2018), Drivers of inclusive growth in Africa: project United Nations. Economic Commission for Africa; Addis Ababa. © NAKED CEA. |
[25]
find that there is a positive link between investment and inclusive growth. The results of their estimations show that a 100% increase in investment in Africa improves inclusive growth by 40%, which is statistically significant. Oyinlola and Adedeji (2015)
| [47] | Oyinlola, M. A., Adedeji, A. (2015), «Human capital, financial sector development and inclusive growth in sub-saharan Africa». Econ Change Restruct 52, 43-66. |
[47]
, on the other hand, find that investment worsens inclusive growth in the Asian context. This same result was also found by Muhammad (2017)
| [40] | Muhammad, L. (2017), «Health care spending and inclusive growth in India: An empirical investigation». Advances in Economics and Business Management, 4 (3), 160-163. |
[40]
in the context of India.
Oyinlola et al (2019)
| [48] | Oyinlola, M. A., Adedeji, A., Bolarinwa, M. O., Olabisi, N. (2019). «Governance, domestic resource mobilization, and inclusive growth in Sub-saharan Africa». Economic Analysis and Policy. 65. https://doi.org/10.1016/j.eap.2019.11.006 |
[48]
use the method of generalised moments in difference to study the impact of governance and resource mobilisation on inclusive growth in 27 Sub-Saharan African countries between 1999 and 2015. They find that there is a positive and significant impact of governance on inclusive growth. A strong governance structure promotes productivity and the mobilisation of labour in the production process, thus making growth more inclusive; they also find that resource mobilisation has not promoted inclusive growth in SSA. However, resource mobilisation does stimulate inclusive growth to the extent that it is facilitated by a strong governance structure.
Kamanzi (2006)
| [31] | Kamanzi, P. C. (2006), ‘Influence of human capital and social capital on employment characteristics among postsecondary graduates in Canada’. |
[31]
in Canada examines the relative influence of human capital and social capital (social relationships) on employment characteristics (full-time or part-time employment, permanent or temporary employment, wages, employment below or equivalent to education level). It uses data from Statistics Canada's 1995 National Graduates Survey. The results of the multiple regressions confirm the idea that job characteristics are significantly associated with both human capital and social capital, although the influence of the individual's human capital is relatively higher than that of his or her social capital. In society, educated people are more inclined to invest in the future education and training of their children and to contribute to society as a whole (Suhrcke et al., 2005)
| [57] | Suhrcke, M., McKee, M., Stuckler, D., Sauto Arce, R., Tsolova, S., & Mortensen, J. (2005), «The contribution of health to the economy in the European Union». Office for Official Publications of the European Communities. |
[57]
. Education not only increases the likelihood of employment. Once in employment, better-educated people earn much more than less-educated people. From an economic point of view, this result has been supported by numerous studies.
Njong (2010)
| [43] | Njong, A. M. (2010), «The effects of educational attainment on poverty reduction in Cameroon». Journal of Education Administration and Policy Studies, 2(1), 1–8. |
[43]
works on the impact of different levels of education on poverty in Cameroon. The results show that the level of education has a negative impact on poverty. Another interesting result is that individuals tend to move away from poverty as levels of education increase. This means that the higher the level of education, the lower the likelihood of a person becoming poor. Researchers have also observed that good health reduces poverty and has a positive impact on the income of economic agents and inclusive growth. Good health increases the ability of individuals to earn income and build up reserves by reducing medical costs.
Muhammad (2017)
| [40] | Muhammad, L. (2017), «Health care spending and inclusive growth in India: An empirical investigation». Advances in Economics and Business Management, 4 (3), 160-163. |
[40]
evaluates the impact of health spending on inclusive growth in India between 1980 and 2014. Using the Augmented Dickey-Fuller test for stationarity and the Johansen co-integration test and OLS to test for the existence of a long-run relationship between the variables used, the results show that there is a positive long-run relationship between health expenditure and inclusive growth. More specifically, this shows that public spending on health makes growth more inclusive in the long term.
In the context of Africa, Tella and Alimi (2016)
| [58] | Tella, S. A. & Alimi, O. Y. (2016), «Determinants of inclusive growth in Africa: Role of health and demographic changes». African Journal of Economic, Review 4(2), 138-146. |
[58]
examine the role of health on inclusive growth in 14 selected countries between 1955 and 2012. The results reveal that health sector finance has a greater impact on growth inclusiveness in Africa, which is essential for achieving universal health coverage. In addition, they suggest greater government involvement in financing the health sector by providing resources.
In his seminal paper, Lopez (2004)
| [37] | Lopez, H. (2004), «Macroeconomics and Inequality». The World Bank Research Workshop, Macroeconomic Challenges in Low Income Countries, Washington, DC. |
[37]
uses telephone density as an indicator of infrastructure, while Calderon and Servén (2008)
| [16] | Calderón, C., & Servén, L. (2008), «Infrastructure and Economic Development in Sub-Saharan Africa». Policy Research Working Paper (4712). |
[16]
use the synthetic index of the quantity and quality of infrastructure. In both cases, the result shows that infrastructure reduces income inequality. This result, combined with the idea that infrastructure has a positive impact on economic growth, can be an effective tool for reducing poverty and improving individual well-being.
Seeking to determine whether infrastructure development promotes poverty reduction in the context of Bangladesh, Khandker et al (2006)
| [33] | Khandker, S., Bakht, Z., & Koolwal, G. (2006), «The Poverty Impact of Rural Roads: The Poverty Impact of Rural Roads: Evidence from Bangladesh». World Bank Policy Research Working Paper3875, 1–34. |
[33]
use a household analysis using quantile regression techniques, and find that income growth did indeed lead to a significant reduction in poverty and had a significantly higher impact on households at the poorest end of the distribution.
3. Methodology
3.1. Data Sources
To carry out our study, we mobilised data from secondary sources. These data come from several databases on SSA countries, namely: WDI, PWT, WEO, PovcalNet and the ILO. The study covers the period from 2000 to 2020 for 21 countries. The choice of period is justified by the fact that for most of the countries in the region, data on some of the variables essential to our work are limited to this period. To constitute our sample, we opted for all the countries with observations for all the variables over the whole of the period considered.
3.2. Model Specification
Achieving such an objective requires analyses covering several countries and several years, which brings out two dimensions: the individual dimension (countries) where the observation units are represented by the index i, i = 1, 2,..., N for N observation units, and the temporal dimension (years) represented by the index t, t = 1,2,..., T. The econometric methods appropriate for analyses combining these two dimensions are panel methods. These methods have certain main advantages: they reduce bias (missing/unobservable variables), they lead to ‘asymptotic’ results and more accurate estimates because the data are more numerous and more variable, and they also provide greater robustness for certain estimates (Dormont, 1989)
| [21] | Dormont, B. (1989), Introduction à l’économétrie des données de panel. Thérie et applications à des échantillons d’entreprises, Paris: CNRS Editions, 125 P. |
[21]
.
With reference to the studies by Hussein et al. (2018)
| [25] | Hussein, K., Mukungu, A., & Awel, Y. (2018), Drivers of inclusive growth in Africa: project United Nations. Economic Commission for Africa; Addis Ababa. © NAKED CEA. |
[25]
on the drivers of inclusive growth in Africa to the studies by Ullah and Munir (2018)
| [59] | Ullah and Munir (2018). «Inclusive Growth in Pakistan: Measurement and Determinants» The Pakistan Journal Of Social Issues, Special Issue (June 2018) 24 September 2018, 150-162. |
[59]
on the measurement and determinants of inclusive growth in Pakistan, the econometric model formulated in this work is as follows:
𝐼𝐶𝐼𝑖𝑡=𝛼0+𝛼1𝐼𝑁𝑉𝑃𝑖𝑡+𝛼2𝐶𝐻𝑖𝑡+𝛼3𝐼𝑁𝐹𝑖𝑡+𝛼4𝐴𝐺𝑅𝑖𝑡+𝛼5𝑁𝑇𝐼𝐶𝑖𝑡+𝛼6𝐼𝑁𝐹𝐿𝑖𝑡+𝛼7𝐼𝐷𝐸𝑖𝑡+𝛼8𝑂𝑈𝑉𝑖𝑡+𝛼9𝑇_𝐶𝐻𝑂𝑀𝐺𝑖𝑡+𝜀𝑖𝑡
𝐼𝐶𝐼
𝑖𝑡 is the inclusive growth indicator of country i in year t. This indicator is captured in this research using the unified measure of inclusive growth based on a utilitarian social welfare function as proposed by Anand et al. (2013)
| [9] | Anand, R., Mishra, S., & Peiris, S. J. (2013), «Inclusive Growth: measurements and determinants. International Monetary Fund, Washington, DC, Vol. 13. |
[9]
. The indicator depends on two factors which are: income growth and income distribution. It is calculated using the formula above:
with
the inclusive growth index;
: revenue growth;
equity growth.
However, according to some authors (McKinley, 2010
| [39] | McKinley, T. (2010), «Inclusive growth criteria and indicators: an inclusive growth index for diagnosis of country progress». ADB Sustainable Development Working Paper, No. 14, Banque asiatique de développement, Mandaluyong City (Philippines). |
[39]
; Ramos et al., 2013
| [53] | Ramos, R. A., Ranieri, R., Lammens, J. W. (2013), «Mapping Inclusive Growth». IPC-IG Working Paper, N°105. International Policy Centre for Inclusive Growth, Brasília. |
[53]
), in order to be inclusive, growth must combine not only the growth dimension and the inequality dimension, but also the poverty dimension and the productive employment dimension. The Anand et al. (2013)
| [9] | Anand, R., Mishra, S., & Peiris, S. J. (2013), «Inclusive Growth: measurements and determinants. International Monetary Fund, Washington, DC, Vol. 13. |
[9]
indicator takes into account the growth dimension and the inequality dimension. In addition to these dimensions, we include two other dimensions: poverty and employment. As a result, the other models formulated are as follows:
𝑃𝐴𝑈𝑉𝑖𝑡=𝛼0+𝛼1𝐼𝑁𝑉𝑃𝑖𝑡+𝛼2𝐶𝐻𝑖𝑡+𝛼3𝐼𝑁𝐹𝑖𝑡+𝛼4𝐴𝐺𝑅𝑖𝑡+𝛼5𝑁𝑇𝐼𝐶𝑖𝑡+𝛼6𝐼𝑁𝐹𝐿𝑖𝑡+𝛼7𝐼𝐷𝐸𝑖𝑡+𝛼8𝑂𝑈𝑉𝑖𝑡+𝛼9𝑇𝐶𝐻𝑂𝑀𝐺𝑖𝑡+𝜀𝑖𝑡
𝐸𝑀𝑃𝐿𝑖𝑡=𝛼0+𝛼1𝐼𝑁𝑉𝑃𝑖𝑡+𝛼2𝐶𝐻𝑖𝑡+𝛼3𝐼𝑁𝐹𝑖𝑡+𝛼4𝐴𝐺𝑅𝑖𝑡+𝛼5𝑁𝑇𝐼𝐶𝑖𝑡+𝛼6𝐼𝑁𝐹𝐿𝑖𝑡+𝛼7𝐼𝐷𝐸𝑖𝑡+𝛼8𝑂𝑈𝑉𝑖𝑡+𝛼9𝑇_𝐶𝐻𝑂𝑀𝐺𝑖𝑡+𝜀𝑖𝑡
𝐼𝐶𝐼, 𝑃𝐴𝑈𝑉 and 𝐸𝑀𝑃𝐿 are the explanatory or dependent variables and the other variables namely: 𝐼𝑁𝑉𝑃, 𝐶𝐻,, 𝐴𝐺𝑅, 𝑁𝑇𝐼𝐶, INFL, IDE, OUV, T_CHOMG are the explanatory or independent variables. 𝐼𝑁𝑉𝑃𝑖𝑡 represents the public investment of country i in year t.
3.3. Presentation of the Variables
The dependent variables in this study are 𝐼𝐶𝐼, 𝑃𝐴𝑈𝑉 and 𝐸𝑀𝑃𝐿.
𝐸𝑀𝑃𝐿
𝑖𝑡 represents productive employment for country i in year t. The ILO (2012)
| [27] | ILO (2012), World of Work Report. Geneva: International Labour Office. |
[27]
has defined productive employment ‘as employment in which the returns to work are sufficient to enable workers and their dependents to have a level of consumption above the poverty line’. In the empirical literature, various indicators of productive employment are proposed but in our study we use the share of employees in industry as a percentage of total employment following McKinley (2010)
| [39] | McKinley, T. (2010), «Inclusive growth criteria and indicators: an inclusive growth index for diagnosis of country progress». ADB Sustainable Development Working Paper, No. 14, Banque asiatique de développement, Mandaluyong City (Philippines). |
[39]
and Zulfikar (2018)
| [62] | Zulfiqar, k. (2018). «Fiscal policy for inclusive growth: A case study of Pakistan». Pakistan Economic and Social Review, 56(1), 21-4. |
[62]
.
𝑃𝐴𝑈𝑉𝑖𝑡 is poverty in country i for year t. It is measured as the percentage of the population living below the poverty line i.e. 1.90 dollars per day in purchasing power parity.
𝜀𝑖𝑡 is the error term. It takes into account three components: the individual component (𝜇𝑖), the time component (𝛽𝑡) and white noise (𝑤𝑖𝑡). Thus 𝜀𝑖𝑡 = 𝜇𝑖 + 𝛽𝑡 + 𝑤𝑖𝑡
The third dependent variable is mentioned above. As for the exogenous variables, they are as follows:
𝐶𝐻
𝑖𝑡 symbolises the human capital of country i in year t. Gleizes (2000)
| [24] | Gleizes, J. (2000), «human capital». Multitudes, 111-112. |
[24]
defines human capital as all the productive capacities that an individual acquires through the accumulation of general or specific knowledge, know-how, etc. It takes into account the health and education dimension. This concept has been used by several researchers (Altinok, 2007
| [8] | Altinok, N. (2007), ‘Human capital and growth: the contribution of international surveys of student achievement’. Public economic, 18-19/ 2006/1-2. |
[8]
; Boccanfuso et al., 2009
| [12] | Boccanfuso, D., Savard, L., Savy, B. (2009), ‘Human capital and growth: evidence from African countries’. Groupe de recherche en Economie et Développement International. Working paper, 09-15. |
[12]
). It is measured by the human capital index, based on years of schooling and returns to education.
𝐼𝑁𝐹
𝑖𝑡 Symbolises the infrastructure of country i in year t. The concept of infrastructure is defined as a complex set of capital goods that provide services combined with other elements (Prud'Homme, 2004)
| [51] | Prud’Homme, R. (2004), «Infrastructure et développement ». Washington, DC: banque mondiale. |
[51]
. According to Africa's pulse (2017), the concept of infrastructure is a multidimensional concept as it involves measuring quantity, quality and access.
𝐴𝐺𝑅𝑖𝑡 symbolises agriculture in country i in year t. In developing economies, the agriculture sector forms the core of the economy. It is therefore important for economic growth on the one hand and poverty reduction on the other. Agriculture is measured as a percentage of GDP.
𝑁𝑇𝐼𝐶
𝑖𝑡 represents the new information and communication technologies of country i in year t. Several authors have focused on the notion of NICT (Adepetun, 2016)
. NICT is measured by the number of mobile phone subscribers per 100 people.
𝐼𝑁𝐹𝐿
𝑖𝑡 symbolises inflation in country i in year t. this variable captures the effects of economic instability and uncertainty (Khan and Senhadji, 2000)
| [32] | Khan, M. S., Senhadji, A. S. (2000), Threshold effects in the relationship between inflation and growth, IMF Working Paper, WP/00/110. |
[32]
. It is measured by the consumer price index.
𝐼𝐷𝐸
𝑖𝑡 symbolises foreign direct investment in country i in year t. It takes into account the net inflow of foreign investment, which can improve growth or lag it depending on which sector suffers the net inflow (see Alfaro et al., 2001)
| [4] | Alfaro, S. C. and Gomes, L. (2001), «Modelling Mineral Aerosol Production by Wind Erosion: Emission Intensities and Aerosol Distributions in Source Areas». Journal of Geophysical Research, 106, 18075-18084. https://doi.org/10.1029/2000JD900339 |
[4]
. It is measured by net inflows as a percentage of GDP.
𝑂𝑈𝑉
𝑖𝑡 represents the trade openness of country i in year t. its inclusion is justified on its ability to capture the level of openness and breadth of the national economy, the country's receptivity to foreign firms (see Oyinlola and Adedeji, 2015)
| [47] | Oyinlola, M. A., Adedeji, A. (2015), «Human capital, financial sector development and inclusive growth in sub-saharan Africa». Econ Change Restruct 52, 43-66. |
[47]
. It is measured by trade openness as a percentage of GDP.
𝑇_𝐶𝐻𝑂𝑀𝐴𝐺
𝑖𝑡 represents unemployment in country i for year t. It is used in our study with reference to studies by Aoyagi and Ganelli (2015)
| [10] | Aoyagi, C. & Ganneli, G. (2015), «Asia’s quest for inclusive growth revisited». Journal of Asian Economics, 40, 29-46. |
[10]
. We measured it by the unemployment rate of populations aged 15 and over.
3.4. Summary Table of Variables and Their Sources
This table presents a summary of the variables, their codes, definitions and sources.
Table 1. Summary of variables and sources.
Variables | Abbreviations | Measurements | Sources |
Inclusive growthCI | CI | Inclusive growth index | Constructed by the author using data from WDI and PovcalNET |
Public investment | INVP | General government GFCF measured as a % of GDP | WEO, IMF |
Human capital | CH | human capital index based on years of schooling and returns to education | PWT version 9.1 |
Infrastructure | INF | electricity consumption in KWh per capita | WDI, WB |
Agriculture | AGR | Agriculture, value added (% of GDP) | WDI, WB |
New information and communication technologies | NTIC | Number of mobile phone subscribers per 100 people | WDI, WB |
Poverty (independent variable) | PAUV | Poverty rate at $1.90 per day (% of population) | PovcalNet |
Foreign direct investment | IDE | Foreign direct investment, net inflows (% of GDP) | WDI, WB |
Inflation | INFL | Inflation, consumer prices (annual %) annuel) | WDI, WB |
Trade openness | OUV | Total trade (% of GDP) | WDI, WB |
Unemployment | T_CHOMAG | Unemployment rate of the population aged 15 and over | ILO |
Productive employment (dependent variable) | EMPL | share of employees in industry (% total employment) total) | WDI, BM |
Source: Authors
4. Results and Interpretation
4.1. Presentation of Results
We present the results of the descriptive statistics on the one hand, and the results of the various regressions on the other. These results were obtained using STATA software and concern data collected from various sources and compiled in an Excel file.
Descriptive results for inclusive growth
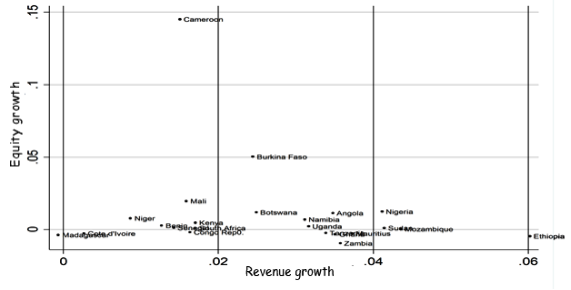
This sub-section examines the degree of inclusiveness in SSA on the basis of available data for the period 2000-2020 for 21 countries. The results show that SSA is not very inclusive, with an average inclusiveness index of 2.95%, partly as a result of GDP growth. This result is consistent with the observation that Africa, and SSA in particular, has experienced renewed growth, but this has not led to a reduction in inequality, poverty reduction or job creation. We use an inclusiveness matrix to represent the inclusiveness of growth in our sample of countries (
Figure 1). Analysis of this matrix shows that the countries in the first quadrant (top right) are those that have experienced inclusive growth due to an increase in GDP and an improvement in equity, for example Nigeria, Burkina Faso and Cameroon. Box two (bottom right) contains countries that have seen an increase in income at the expense of equity, such as Tanzania. Growth is said to be inclusive for the countries in this quadrant if the increase in income is greater than the absolute value of equity. Quadrant three (bottom right) contains countries that have experienced unambiguously non-inclusive growth because both income and equity growth are negative (Madagascar).
Figure 1. Inclusiveness matrix for a sample of SSA countries.
4.2. Descriptive Results for other Variables
The study used time-series data for the period 2000-2020 for 21 SSA countries selected on the basis of available data. The infrastructure variable was removed from the model because the rate of missing data was very high. The inclusive growth index is multiplied by 100 to balance the scales. The analysis includes mean values, standard deviations, minimum values and maximum values. Descriptive statistics are given in
Table 3 below.
Table 2. Descriptive statistics.
Variables | Obs | Mean | Std. Dev. | Min | Max |
Inclusive growth index | 336 | 2,953 | 8,002 | -32,078 | 70,582 |
Public investment | 336 | 4,132 | 5,503 | 0,4761 | 28,788 |
Human capital | 336 | 1,774 | 0,461 | 1,069 | 2,834 |
Agriculture | 336 | 19,490 | 11,463 | 1,828 | 43,399 |
NICT | 336 | 41,623 | 39,454 | 0,0181 | 163,875 |
Inflation | 325 | 7,147 | 9,240 | -60,496 | 98,224 |
Foreign direct investment | 336 | 4,192 | 5,627 | -5,208 | 50,018 |
Trade openness | 336 | 70,136 | 29,643 | 19,101 | 165,646 |
Unemployment rate | 336 | 8,586 | 7,133 | 0,32 | 33,47 |
Poverty | 336 | 39,552 | 20,824 | 0,19 | 86 |
Employment | 336 | 12,965 | 7,285 | 2,817 | 39,249 |
Source: Author's calculations
In this table, the variables inclusive growth index, poverty and employment are the dependent variables of our study, while the variables public investment, human capital, agriculture, new information and communication technologies, inflation, foreign direct investment, trade openness and unemployment are the independent variables of the study.
The table shows that, on average, the countries achieved inclusive growth of 2.953%, with a minimum value of -32.078% and a maximum value of 70.582%. The average value of public investment is 4.132%, which confirms the idea that public investment is low in SSA, and the standard deviation is 5.618%, which is higher than the average, so public investment varies greatly from one country to another. PWT statistics show an average value of 1.774 for human capital, a minimum value of 1.069 and a maximum value of 2.834 with a standard deviation of 0.461, suggesting that SSA has low human capital. In terms of poverty, 39.551% of the population lives in extreme poverty, i.e. on less than $1.90 a day, a rate that is still very high despite the region's strong economic performance. In terms of employment, an average of 12.965% of the population is in productive employment, with the majority of the workforce concentrated in precarious jobs, confirming ILO estimates that over 70% of the population in SSA is concentrated in the informal sector.
The table also shows that all the variables have positive mean values. Among these variables, the most volatile is NICT with a standard deviation of 39.454% and the least volatile is human capital with a standard deviation of 0.461%, representing the most stable variable.
4.3. Correlation Between Variables
The table below shows the various correlations between the variables.
Table 3. Correlation matrix.
| ICI1 | pauv | empl | invp | ch | agr | ntic | infl | ide ouv t_chomag |
ICI1 | 1.0000 | | | | | | | | |
pauv | 0.0325 | 1.0000 | | | | | | | |
empl | 0.0293 | -0.6460 | 1.0000 | | | | | | |
invp | 0.0146 | -0.1343 | 0.1041 | 1.0000 | | | | | |
ch | -0.0282 | -0.4610 | 0.5109 | 0.1249 | 1.0000 | | | | |
agr | 0.0323 | 0.4239 | -0.5620 | -0.2324 | -0.6657 | 1.0000 | | | |
ntic | 0.0151 | -0.4723 | 0.3850 | 0.2613 | 0.4843 | -0.4038 | 1.0000 | | |
infl | 0.0304 | -0.0384 | -0.0965 | 0.0480 | 0.1100 | 0.0472 | -0.1018 | 1.0000 | |
ide | -0.0244 | 0.1637 | -0.0381 | -0.1073 | -0.0340 | -0.0171 | 0.0822 | 0.0995 | 1.0000 |
ouv | -0.0364 | -0.3171 | 0.4916 | -0.1101 | 0.4136 | -0.5973 | 0.2972 | -0.0317 | 0.3142 1.0000 |
t_chomag | -0.0177 | -0.3822 | 0.5788 | 0.2118 | 0.5106 | -0.5884 | 0.2874 | 0.0061 | -0.0104 0.2978 1.0000 |
Source: Author using Stata
This table shows the various correlations between the variables. It shows that public investment, agriculture and new technologies are positively correlated with the inclusive growth index, which means that these variables contribute to reducing inequality. On the other hand, human capital, foreign direct investment and openness are negatively correlated with the inclusive growth index, meaning that these variables worsen equity. In terms of poverty, the table shows that the variables public investment, human capital, new technologies, inflation, openness and unemployment are negatively correlated with poverty, while the variables agriculture and foreign direct investment are positively correlated. With regard to employment, we find that the variables public investment, human capital, new technologies, openness and unemployment are positively correlated with it, while the variables agriculture, inflation and foreign direct investment are negatively correlated with employment.
4.4. Results of the Various Regressions
Before presenting the results of the regressions, we will present the results of the various basic tests carried out, namely the stationarity test (IPS test), the heteroscedasticity test (Breusch-Pagan) and the autocorrelation test (Wooldridge).
Results of the stationarity test for the different variables
In time series models such as panel models, it is important to study stationarity in order to avoid spurious regressions. To check the stationarity of the variables, we performed the Im, Pesaran and Shin or IPS test. Once the series is stationary at level, we no longer check stationarity in difference. The various results are presented in Appendix I.
Table 4. Results of the stationarity test.
Variables | Level stationary | Difference stationary | Order of integration |
Inclusive growth index | yes | // | I (0) |
Public investment | Yes | // | I (0) |
Human capital | Yes | // | I (0) |
Agriculture | Yes | // | I (0) |
New information and communication technologies | Yes | | I (0) |
Employment | Yes | // | I (0) |
Inflation | Yes | // | I (0) |
Foreign direct investment | Yes | // | I (0) |
Unemployment rate | Yes | // | I (0) |
Poverty | Yes | // | I (0) |
Openness | Yes | // | I (0) |
Source: Author
The results presented in the table above indicate that all the variables are stationary at level.
For the other tests, we will present our results in the form of a summary table for the three models. Before doing so, it is worth recalling the different models.
-Model 1: regression of public investment on growth and its distribution;
𝐼𝐶𝐼𝑖𝑡=𝛼0+𝛼1𝐼𝑁𝑉𝑃𝑖𝑡+𝛼2𝐶𝐻𝑖𝑡+𝛼3𝐼𝑁𝐹𝑖𝑡+𝛼4𝐴𝐺𝑅𝑖𝑡+𝛼5𝑁𝑇𝐼𝐶𝑖𝑡+𝛼6𝐼𝑁𝐹𝐿𝑖𝑡+𝛼7𝐼𝐷𝐸𝑖𝑡+𝛼8𝑂𝑈𝑉𝑖𝑡+𝛼9𝑇_𝐶𝐻𝑂𝑀𝐺𝑖𝑡+𝜀𝑖𝑡
- Model 2: regression of public investment on poverty;
𝑃𝐴𝑈𝑉𝑖𝑡=𝛼0+𝛼1𝐼𝑁𝑉𝑃𝑖𝑡+𝛼2𝐶𝐻𝑖𝑡+𝛼3𝐼𝑁𝐹𝑖𝑡+𝛼4𝐴𝐺𝑅𝑖𝑡+𝛼5𝑁𝑇𝐼𝐶𝑖𝑡+𝛼6𝐼𝑁𝐹𝐿𝑖𝑡+𝛼7𝐼𝐷𝐸𝑖𝑡+𝛼8𝑂𝑈𝑉𝑖𝑡+𝛼9𝑇𝐶𝐻𝑂𝑀𝐺𝑖𝑡+𝜀𝑖𝑡
- Model 3: regression of public investment on productive employment.
𝐸𝑀𝑃𝐿𝑖𝑡=𝛼0+𝛼1𝐼𝑁𝑉𝑃𝑖𝑡+𝛼2𝐶𝐻𝑖𝑡+𝛼3𝐼𝑁𝐹𝑖𝑡+𝛼4𝐴𝐺𝑅𝑖𝑡+𝛼5𝑁𝑇𝐼𝐶𝑖𝑡+𝛼6𝐼𝑁𝐹𝐿𝑖𝑡+𝛼7𝐼𝐷𝐸𝑖𝑡+𝛼8𝑂𝑈𝑉𝑖𝑡+𝛼9𝑇_𝐶𝐻𝑂𝑀𝐺𝑖𝑡+𝜀𝑖𝑡
Results of the heteroskedasticity test
The heteroscedasticity test allows us to determine whether the variance of the residual term is constant over time. If the residuals are not homoscedastic, we can no longer apply the OLS estimator to estimate our models. See Appendix 2 for different tests.
The Breusch-Pagan test gives us the following results for the three models:
Table 5. Results of the Breusch-Pagan heteroscedasticity test.
models | Chi-square | p-value |
Model 1 | 14712.65 | 0.0000 |
Model 2 | 1262.14 | 0.0000 |
Model 3 | 17285.31 | 0.0000 |
On the basis of these results, we conclude that the errors are heteroskedastic because all the p-values are less than 1%.
Results of the autocorrelation test
Using the Wooldridge autocorrelation test (see Appendix 3), we obtain the following results:
Table 6. Results of the Wooldridge autocorrelation test.
models | F statistic | p-value |
Model 1 | 3.190 | 0.0893 |
Model 2 | 1.672 | 0.2107 |
Model 3 | 84.719 | 0.0000 |
Source: Author
The results of model 1 indicate that there is serial autocorrelation of the residuals, as the p-value 0.0893 is less than 10%, which leads us to reject H0. For model 2, the results indicate an absence of first-order autocorrelation (p-value 0.2107 greater than 10%). However, for model 3, the test indicates the presence of autocorrelation because the p-value 0.000 is less than 1%, so H0 is rejected.
4.5. Estimation Results for the Various Models
At the end of the previous tests, we find that in model 2, there is heteroscedasticity and no autocorrelation, and in model 1 and model 3, there is both heteroscedasticity and autocorrelation. We therefore first need to correct the heteroscedasticity in model 2 using White's approach, which consists of using the Robust option when estimating the results. We simultaneously corrected for heteroscedasticity and autocorrelation in models 1 and 3 by regressing with Driscoll-Kraay standard errors.
Table 7. Summary of estimation results.
Variables | Model 1 | Model 2 | Model 3 |
Fixed effects | Random effects | Random effects | Fixed effects | Random effects |
Public investment | -0,330** (0,135) | 0,003 (0,063) | -0,250 (,283) | -0,032 (0,028) | -0,0569** (0,026) |
Human capital | 0,674 (4,585) | -0,798 (0.629) | -8,112 (13,184) | -5,184*** (0,887) | -1,906 (3,552) |
Agriculture | 0,0239 (0,056) | 0.009 (0,018) | 0,0250 (0,193) | -0,126** (0,052) | -0,129*** (,041) |
New information and communication technologies | 0,009 (0,007) | 0,011* (0,006) | -0,086*** (0,034) | 0,018*** (0.006) | 0,013 (0,012) |
Inflation | -0,020 (0,043) | 0,037** (0,016) | -0,125 (0,093) | 0,006 (0,009) | 0,004 (0,015) |
Foreign direct investment | -0,047 (0,033) | -0,042 (0,034) | -0,162 (0,122) | 0,009 (0,013) | 0,009 (0,016) |
Openness | 0,003 (0,031) | -0,004 (0,005) | -0,120* (0,072) | 0,041*** (0,012) | 0,044** (0,018) |
Unemployment rate | -0,322* (0,161) | 0,002 (0,04) | -0,163 (,362) | 0,361*** (0,105) | 0,384*** (0,078) |
Constant | 5,101 (9,581) | 3,849** (1.421) | 69,317*** (24,606) | 18,231*** (1,758) | 12,202 (7,318) |
Number of observations | 325 | 325 | 325 | 325 | 325 |
Ficher/Wald test | 30,29 (0,0000) | 233,77 (0,0000) | 30,22 (0,0002) | 154,40 (0.0000) | 782,41 (0.0000) |
Source: Author
*,**, *** signify significance at 10%, 5% and 1% respectively. Values in brackets represent standard deviations.
For model 1, the fixed effects estimator (Within) gives an R² equal to 0.013 and the random effects estimator (GCM) gives an R² value of 0.005. We therefore opt for the fixed effects estimator (Within) (see appendix 5).
For model 2, the fixed effects estimator (Within) gives an R² equal to 0.261 and the random effects estimator (GCM) gives an R² value of 0.280. In this case, we lean towards the random effects estimator (GCM) (see appendix 4).
For model 3, the Within R² is 0.132 and the GCM R² is 0.437. We therefore choose the random effects estimator (GCM) to estimate this model (see Appendix 5).
4.6. Interpretation
Interpretation of the results of the individual significance tests for the first regression (model 1)
The objective of this first regression is to assess the effect of public investment on growth and its distribution in SSA. The results obtained from the fixed effects estimator (within) indicate that the public investment and unemployment rate variables are significant at 5% and 10% respectively. The variables human capital, agriculture, new information and communication technologies, inflation, foreign direct investment and trade openness are not significant.
More specifically, the public investment variable, with a coefficient of -0.33, has a negative and significant impact on the inclusive growth index variable, meaning that a 1 percentage point increase in public investment would lead to a 0.33 percentage point reduction in growth inclusiveness. Public investment does not therefore appear to reduce inequality in SSA. Brennenman and kerf (2002)
| [14] | Brenneman, A., and M, Kerf, (2002), “Infrastructure and Poverty Linkages: A Literature Review”. The World Bank, Mimeo. |
[14]
have suggested that, ideally, public investment should reduce income inequality, as it improves access to employment, health and education opportunities. Similarly, the unemployment rate variable with a coefficient of -0.32 is negatively correlated with the inclusive growth index. On the basis of the above results, we cannot validate the hypothesis that public investment contributes to economic growth and its distribution.
Interpretation of the results of individual significance tests for the second regression (model 2)
The objective here is to study the effect of public investment on poverty. To materialise this effect, we used the random effects estimator (GCM). At the end of this regression, we find that new technologies and trade openness are significant at the 5% and 10% thresholds, with p-values of 0.011 and 0.094 respectively, so they explain our model. These two variables have respective coefficients of -0.086 and -0.120, which implies that a 100% increase in new technologies leads to an 8% reduction in poverty and a 100% increase in trade openness reduces poverty by 12%. On the other hand, public investment, human capital, agriculture, inflation, foreign direct investment and unemployment are not significant in our model and therefore cannot be considered as determinants of poverty. In view of the various results, we reject the hypothesis that public investment contributes to poverty reduction.
Interpretation of the results of the individual significance tests for the third regression (model 3)
This regression uses the random effects estimator (GCM) to highlight the effect of public investment on productive employment. The estimation results show that of the eight independent variables in the model, four have a significant effect on productive employment. These are public investment and trade openness, which are significant at the 5% level, and agriculture and unemployment, which are significant at the 1% level.
More precisely, with a coefficient of -0.056, public investment evolves in the opposite direction to employment. A 100% increase in investment has a negative impact of 5% on the employment rate. With a coefficient of -0.12, a 100% increase in the share of agriculture in GDP reduces employment by 12%. On the basis of the results obtained, we cannot validate the hypothesis that public investment contributes to job creation in SSA.
4.7. Discussion of the Results
The results presented above indicate that public investment has a negative and significant impact on growth and equity. This implies that the more public investment is increased, the more growth and equity rates will deteriorate, thus increasing inequality in the SSA sub-region. This result can be explained by the fact that the majority of public investment takes place in urban areas, with people in rural areas generally being left out. These results do not corroborate those of Brennenman and kerf (2002)
| [14] | Brenneman, A., and M, Kerf, (2002), “Infrastructure and Poverty Linkages: A Literature Review”. The World Bank, Mimeo. |
[14]
who suggested that, ideally, public investment should reduce income inequality, as it improves access to employment, health and education opportunities. Similarly, unemployment has negative effects on inequality, i.e. it increases inequality. These results are in line with those of Aoyagi and Ganelli (2015)
| [47] | Oyinlola, M. A., Adedeji, A. (2015), «Human capital, financial sector development and inclusive growth in sub-saharan Africa». Econ Change Restruct 52, 43-66. |
[47]
, who find a negative impact of unemployment on inclusive growth in the Asian context. Labour reforms aimed at reducing unemployment by increasing productivity are therefore important for inclusive growth. As far as poverty is concerned, no statistically significant effect of public investment was found on poverty. On the other hand, new information and communication technologies and trade openness reduce poverty in such a way that a 100% increase in new information and communication technologies or openness reduces poverty by 8% or 12% respectively. This implies that new information and communication technologies and openness are determinants of poverty. By running regressions on employment, the results show once again that public investment has a significant and negative impact on employment, and therefore worsens employment. Indeed, the crowding-out theory shows that the more the State increases public investment, the less the private sector invests, and it is the private sector that creates jobs in an economy, so there will be many job losses. Based solely on public investment, we can say that a positive variation in public investment has a negative impact on equity, growth and productive employment. If we consider inclusive growth as growth that reduces poverty and inequality and creates productive employment within society, the results show that, overall, public investment has a negative and significant impact on inclusive growth in SSA for our sample of countries. A logical explanation for these results may be that public sector investments are low and inequitably distributed. In this case, they cannot act as a lever for inclusive growth in SSA. Our results run counter to those found by Ndiaye et al (2020)
in Senegal. They found that public investment contributes to improving the inclusiveness of growth. In fact, an increase in public investment, particularly in the agricultural, industrial and market services sectors, makes it possible to move towards inclusive growth, according to the results obtained by the authors.
5. Conclusion
Our task was to validate or invalidate the hypotheses that we put forward at the outset in order to answer the central question that revolved around these hypotheses, which was to study the effect of public investment on inclusive growth in SSA. We concluded that public investment has a negative and significant impact on the inclusive growth index, which takes into account income growth and its distribution, and also has a negative and significant effect on employment. No significant effect on poverty was found. Overall, they have negative and significant effects on inclusive growth in SSA. This result could be explained by their weakness and uneven distribution. Several studies have shown the positive impact of public investment in transport, health and education on growth, yet the majority of major projects in SSA are focused on other sectors that do not have a high employment potential (energy, for example).
In the light of these results, this study puts forward a number of recommendations:
1) Increasing public investment in sectors that directly target vulnerable populations (education, health, sanitation, roads, etc.) should be a priority for them, as this requires a major mobilisation of both public and private funds and so they would gain a great deal by stimulating private investment as well.
2) The implementation of policies that encourage the efficiency of public investments, for example, the improvement of institutions and procedures that apply to the evaluation, selection and monitoring of projects that can have a direct impact on the well-being of populations.
3) Increased investment in new information and communication technologies is needed to reduce poverty.
Abbreviations
MTRs | Migrant Remittances |
OECD | Organisation for Economic Co-operation and Development |
SSA | Sub Saharan Africa |
UN | United Nations |
SDGs | Sustainable Development Goals |
Author Contributions
Gildas Boris Dudjo Yen: Methodology, Supervision, Visualization, Writing – review & editing
Armel Ndolembaye: Methodology, Supervision, Visualization, Writing – review & editing
Conflicts of Interest
The authors declare no conflicts of interest.
Appendix
The basic econometric tests for panel regressions are: the stationarity test, the heteroskedasticity test and the autocorrelation test.
The stationarity test
The unit root test is a test of the stationarity of variables. There are four tests in the literature (Dormont, 1989)
| [21] | Dormont, B. (1989), Introduction à l’économétrie des données de panel. Thérie et applications à des échantillons d’entreprises, Paris: CNRS Editions, 125 P. |
[21]
, known as first generation unit root tests on panel data: the Levin and Lin (1992) test, the Im, Pesaran and Shin or IPS (1997) test, the Maddala and Wu (1999) test and the Hadri (2000) test. In our study, we will use the Im, Pesaran and Shin or IPS (1997) test. These authors were the first to develop a test allowing, under the alternative hypothesis, not only heterogeneity in the autoregressive root (𝜌𝑖 ≠ 𝜌𝑗), but also heterogeneity in the presence of a unit root in the panel.
We follow Hurlin and Mignon (2006) to briefly introduce the Im, Pesaran and Shin (IPS) test.
The IPS model is written as follows: ∆𝑦𝑖, = 𝛼𝑖 + 𝜌𝑖𝑦𝑖,−1 + 𝜀𝑖,𝑡
Where the individual effect 𝛼𝑖 is defined by 𝛼𝑖= 𝜌𝑖𝛾𝑖 with 𝛾𝑖 𝜖 ℝ. The IPS test is a joint test of the null hypothesis of unit ra-cine (𝜌𝑖 = 0, which implies that the variable is non-stationary) and the absence of individual effects because under the null hypothesis 𝛼𝑖 = 0. Under the alternative hypothesis, two types of individuals can coexist: indi-viduals indexed i = 1,2,..., 𝑁1 for which the variable 𝑦𝑖, is stationary and individuals indexed i = 𝑁1+ 1,..., N for which the dynamics of the variable 𝑦𝑖,𝑡 admits a unit root The hypotheses of the test are as follows:
H0: 𝜌𝑖 = 0, ∀𝑖 = 1,2,..., N
H1: 𝜌𝑖 < 0, ∀𝑖 =1,2,..., 𝑁1
𝜌𝑖 = 0, ∀𝑖 = 𝑁1+ 1, 𝑁1 + 2,..., N
The heteroskedasticity test
In our study, we opt for the Breusch-Pagan test to test heteroscedasticity. The test seeks to determine the nature of the variance of the error term: if the variance is constant, then we have homoscedasticity; on the other hand, if it varies, we have heteroscedasticity. The hypotheses of the test are as follows:
H0: homoscedasticity
H1: heteroscedasticity
In our study we use the Wooldridge (2002) test for first-order autocorrelation. The hypotheses are as follows:
H0: 𝑎bsence of first-order autocorrelation
H1: presence of first-order autocorrelation
Decision rule: this is the same as in the case of heteroscedasticity, i.e. if p value < 𝛼, then we reject 𝐻0 and conclude that there is error autocorrelation.
Next, we proceed in two steps to analyse the significance of the model: overall significance of the coefficients and individual significance of the coefficients (see Dormont, 1989)
| [21] | Dormont, B. (1989), Introduction à l’économétrie des données de panel. Thérie et applications à des échantillons d’entreprises, Paris: CNRS Editions, 125 P. |
[21].
Appendix I: Stationarity Tests for Different Variables
. xtunitroot ips ICI1
Im-Pesaran-Shin unit-root test for ICI1
Ho: All panels contain unit roots Number of panels = 21
Ha: Some panels are stationary Number of periods = 16
AR parameter: Panel-specific Asymptotics: T,N -> Infinity Panel means: Included sequentially
Time trend: Not included
ADF regressions: No lags included
Fixed-N exact critical values Statistic p-value 1% 5% 10%
t-bar -3.1903 -1.950 -1.820 -1.750
t-tilde-bar -2.4011
Z-t-tilde-bar -6.3279 0.0000
. xtunitroot ips invp, trend
Im-Pesaran-Shin unit-root test for invp
Ho: All panels contain unit roots | Number of panels | = | 21 |
Ha: Some panels are stationary | Number of periods | = | 16 |
AR parameter: Panel-specific Asymptotics: T,N -> Infinity |
Panel means: Time trend: | Included Included | sequentially |
ADF regressions: No lags included
Fixed-N exact critical values
Statistic | p-value | 1% | 5% | 10% |
t-bar | -1.9577 | | -2.580 -2.460 -2.390 |
t-tilde-bar | -1.6423 | | |
Z-t-tilde-bar | -1.7240 | 0.0424 | |
Appendix II: Heteroscedasticity Test
Model 1
. xtreg ICI1 invp ch agr ntic infl ide ouv t_chomag, fe
Fixed-effects (within) regression Number of obs = 325
Group variable: code_pays Number of groups = 21
R-sq: | Obs | per | group: | |
within = 0.0129 | | | min = | 11 |
between = 0.0187 | | | avg = | 15.5 |
overall = 0.0000 | | | max = | 16 |
| F(8,296) | = | 0.48 |
corr(u_i, Xb) = -0.8383 | Prob > F | = | 0.8668 |
ICI1 | Coef. | Std. Err. | t | P>|t| | | [95% Conf. | Interval] |
invp | -.3303691 | .2166556 | -1.52 | 0.128 | | -.7567497 | .0960115 |
ch | .6741914 | 9.465318 | 0.07 | 0.943 | -17.95366 | 19.30204 |
agr | .0239239 | .1614193 | 0.15 | 0.882 | -.293751 | .3415989 |
ntic | .0090873 | .0242058 | 0.38 | 0.708 | -.0385499 | .0567245 |
infl | -.0200584 | .0600243 | -0.33 | 0.738 | -.138187 | .0980701 |
ide | -.0469072 | .1114828 | -0.42 | 0.674 | -.2663066 | .1724922 |
ouv | .0033041 | .0485536 | 0.07 | 0.946 | -.0922499 | .0988581 |
t_chomag | -.3220458 | .2790152 | -1.15 | 0.249 | -.8711507 | .2270591 |
_cons | 5.101697 | 17.13388 | 0.30 | 0.766 | -28.61796 | 38.82135 |
sigma_u | 3.7739137 | | | | | |
sigma_e | 8.197656 | | | | |
rho | .17487386 | (fraction of | variance due | to | u_i) |
F test that all u_i=0: F(20, 296) = 0.90 Prob > F = 0.5877
. xttest3
Modified Wald test for groupwise heteroskedasticity in fixed effect regression model
H0: sigma(i)^2 = sigma^2 for all i
chi2 (21) = 14712.65
Prob>chi2 = 0.0000
Model 2
. xtreg pauv invp ch agr ntic infl ide ouv t_chomag, fe
Fixed-effects (within) regression | Number of obs = | 325 |
Group variable: code_pays | Number of groups = | 21 |
R-sq: | Obs per group: | |
within = 0.3381 | min = | 11 |
between = 0.2567 | avg = | 15.5 |
overall = 0.2605 | max = | 16 |
| F(8,296) = | 18.90 |
corr(u_i, Xb) = 0.1488 | Prob > F = | 0.0000 |
pauv | Coef. | Std. Err. | t P>|t| | | [95% Conf. | Interval] |
invp | -.2800396 | .1701427 | -1.65 0.101 | | -.6148822 | .054803 |
ch | -4.762802 | 7.433244 | -0.64 0.522 | | -19.39151 | 9.865902 |
agr | .0034846 | .1267648 | 0.03 0.978 | | -.2459899 | .2529592 |
ntic | -.0894068 | .0190091 | -4.70 0.000 | | -.126817 | -.0519967 |
infl | -.1242657 | .0471379 | -2.64 0.009 | | -.2170336 | -.0314977 |
ide | -.1785839 | .087549 | -2.04 0.042 | | -.3508813 | -.0062866 |
ouv | -.1179122 | .0381298 | -3.09 0.002 | | -.192952 | -.0428723 |
t_chomag | -.0766695 | .2191145 | -0.35 0.727 | | -.5078892 | .3545501 |
_cons | 62.97037 | 13.45547 | 4.68 0.000 | | 36.48986 | 89.45087 |
sigma_u | 17.231486 | | | | | |
sigma_e | 6.4377322 | | | | | |
rho | .87751698 | (fraction of | variance due | to | u_i) | |
F test that all u_i=0: F(20, 296) = 86.72 Prob > F = 0.0000
. xttest3
Modified Wald test for groupwise heteroskedasticity in fixed effect regression model
H0: sigma(i)^2 = sigma^2 for all i
chi2 (21) = 1262.14
Prob>chi2 = 0.0000
Appendix III: Autocorrelation Test
Model 1
. xtserial ICI1 invp ch agr ntic infl ide ouv t_chomag
Wooldridge test for autocorrelation in panel data H0: no first order autocorrelation
F( 1, 20) = 3.190
Prob > F = 0.0893
Model 2
. xtserial pauv invp ch agr ntic infl ide ouv t_chomag
Wooldridge test for autocorrelation in panel data H0: no first order autocorrelation
F( 1, 20) = 1.672
Prob > F = 0.2107
Model 3
. xtserial empl invp ch agr ntic infl ide ouv t_chomag
Wooldridge test for autocorrelation in panel data H0: no first order autocorrelation
F(1, 20) = 84.719 Prob > F = 0.0000
Appendix IV: White Test for Model 2
. xtreg pauv invp ch agr ntic infl ide ouv t_chomag, fe ro
Fixed-effects (within) regression | Number of obs = | 325 |
Group variable: code_pays | Number of groups = | 21 |
R-sq: | Obs per group: | |
within = 0.3381 | min = | 11 |
between = 0.2567 | avg = | 15.5 |
overall = 0.2605 | max = | 16 |
| F(8,20) = | 4.14 |
corr(u_i, Xb) = 0.1488 | Prob > F = | 0.0047 |
(Std. Err. adjusted for 21 clusters in code_pays)
pauv | Coef. | Robust Std. Err. | t P>|t| | | [95% Conf. | Interval] |
invp | -.2800396 | .3210122 | -0.87 0.393 | | -.9496593 | .3895801 |
ch | -4.762802 | 23.25321 | -0.20 0.840 | | -53.26816 | 43.74255 |
agr | .0034846 | .216731 | 0.02 0.987 | | -.4486083 | .4555776 |
ntic | -.0894068 | .0466463 | -1.92 0.070 | | -.1867092 | .0078955 |
infl | -.1242657 | .0971445 | -1.28 0.215 | | -.3269055 | .0783742 |
ide | -.1785839 | .1301953 | -1.37 0.185 | | -.4501665 | .0929986 |
ouv | -.1179122 | .0759396 | -1.55 0.136 | | -.2763194 | .0404951 |
t_chomag | -.0766695 | .3763016 | -0.20 0.841 | | -.8616209 | .7082818 |
_cons | 62.97037 | 41.815 | 1.51 0.148 | | -24.25419 | 150.1949 |
sigma_u | 17.231486 | | | | | |
sigma_e | 6.4377322 | | | | | |
rho | .87751698 | (fraction of | variance due | to | u_i) | |
. xtreg pauv invp ch agr ntic infl ide ouv t_chomag, re ro
Random-effects GLS regression | Number of obs = | 325 |
Group variable: code_pays | Number of groups = | 21 |
R-sq: | Obs per group: | |
within = 0.3371 | min = | 11 |
between = 0.2781 | avg = | 15.5 |
overall = 0.2802 | max = | 16 |
| Wald chi2(8) = | 30.22 |
corr(u_i, X) = 0 (assumed) | Prob > chi2 = | 0.0002 |
(Std. Err. adjusted for 21 clusters in code_pays)
pauv | Coef. | Robust Std. Err. | z | P>|z| | | [95% Conf. | Interval] |
invp | -.2500849 | .2826247 | -0.88 | 0.376 | | -.8040191 | .3038493 |
ch | -8.112412 | 13.18376 | -0.62 | 0.538 | -33.95211 | 17.72728 |
agr | .0250373 | .1927184 | 0.13 | 0.897 | -.3526839 | .4027585 |
ntic | -.0856408 | .0337379 | -2.54 | 0.011 | -.1517659 | -.0195158 |
infl | -.1250017 | .0933294 | -1.34 | 0.180 | -.3079239 | .0579205 |
ide | -.1624392 | .1221235 | -1.33 | 0.183 | -.4017969 | .0769185 |
ouv | -.1204598 | .0719817 | -1.67 | 0.094 | -.2615413 | .0206217 |
t_chomag | -.1625837 | .3619183 | -0.45 | 0.653 | -.8719306 | .5467632 |
_cons | 69.31697 | 24.60628 | 2.82 | 0.005 | 21.08954 | 117.5444 |
sigma_u | 14.782392 | | | | | |
sigma_e | 6.4377322 | | | | |
rho | .8405761 | (fraction of | variance due | to | u_i) |
Appendix V: Results of Regressions with Driscoll-Kraay Standard Errors for Model 1 and Model 3
Model 1
. xtscc ICI1 invp ch agr ntic infl ide ouv t_chomag, fe lag (9)
Regression with Driscoll-Kraay standard errors | Number of obs | = | 325 |
Method: Fixed-effects regression | Number of groups | = | 21 |
Group variable (i): code_pays | F( 8, 15) | = | 30.29 |
maximum lag: 9 | Prob > F | = | 0.0000 |
| within R-squared | = | 0.0129 |
ICI1 | Coef. | Drisc/Kraay Std. Err. | t | P>|t| | [95% Conf. | Interval] |
invp | -.3303691 | .137919 | -2.40 | 0.030 | -.6243365 | -.0364016 |
ch | .6741914 | 4.566054 | 0.15 | 0.885 | -9.058121 | 10.4065 |
agr | .0239239 | .0642475 | 0.37 | 0.715 | -.1130165 | .1608643 |
ntic | .0090873 | .0070439 | 1.29 | 0.217 | -.0059264 | .024101 |
infl | -.0200584 | .0441814 | -0.45 | 0.656 | -.1142289 | .074112 |
ide | -.0469072 | .0361515 | -1.30 | 0.214 | -.1239623 | .0301478 |
ouv | .0033041 | .0323993 | 0.10 | 0.920 | -.0657534 | .0723616 |
t_chomag | -.3220458 | .1777778 | -1.81 | 0.090 | -.7009702 | .0568785 |
_cons | 5.101697 | 9.68467 | 0.53 | 0.606 | -15.54069 | 25.74408 |
. xtscc ICI1 invp ch agr ntic infl ide ouv t_chomag, re lag (9) (11 missing values generated)
Regression with Driscoll-Kraay standard errors Number of obs = 325
Method: Random-effects GLS regression Number of groups = 21
Group variable (i): code_pays Wald chi2(8) = 233.77
maximum lag: 9 Prob > chi2 = 0.0000
corr(u_i, Xb) = 0 (assumed) overall R-squared = 0.0051
ICI1 | Coef. | Drisc/Kraay Std. Err. | t | P>|t| | | [95% Conf. | Interval] |
invp | .0028386 | .0626287 | 0.05 | 0.964 | | -.1306514 | .1363286 |
ch | -.7979938 | .6286704 | -1.27 | 0.224 | -2.137973 | .5419855 |
agr | .0092814 | .017681 | 0.52 | 0.607 | -.0284047 | .0469675 |
ntic | .0107438 | .0058565 | 1.83 | 0.086 | -.0017391 | .0232267 |
infl | .0367799 | .0153867 | 2.39 | 0.030 | .0039839 | .0695759 |
ide | -.0423772 | .0342356 | -1.24 | 0.235 | -.1153487 | .0305943 |
ouv | -.0041524 | .0047595 | -0.87 | 0.397 | -.014297 | .0059921 |
t_chomag | .0017432 | .0377107 | 0.05 | 0.964 | -.0786353 | .0821218 |
_cons | 3.849667 | 1.42147 | 2.71 | 0.016 | .8198753 | 6.879459 |
sigma_u | .27056513 | | | | | |
sigma_e | 8.197656 | | | | |
rho | .00108816 | (fraction of | variance due | to | u_i) |
Model 3
. xtscc empl invp ch agr ntic infl ide ouv t_chomag, fe lag (2)
Regression with Driscoll-Kraay standard errors Number of obs = 325
Method: Fixed-effects regression Number of groups = 21
Group variable (i): code_pays F( 8, 15) = 145.40
maximum lag: 2 Prob > F = 0.0000
within R-squared = 0.1320
empl | Coef. | Drisc/Kraay Std. Err. | t | P>|t| | [95% Conf. | Interval] |
invp | -.0318392 | .0280531 | -1.13 | 0.274 | -.091633 | .0279546 |
ch | -5.18495 | .8869237 | -5.85 | 0.000 | -7.075383 | -3.294517 |
agr | -.1258575 | .0521021 | -2.42 | 0.029 | -.2369106 | -.0148044 |
ntic | .0182534 | .0057887 | 3.15 | 0.007 | .0059151 | .0305916 |
infl | .0055363 | .009036 | 0.61 | 0.549 | -.0137234 | .0247959 |
ide | .009925 | .0129745 | 0.76 | 0.456 | -.0177294 | .0375794 |
ouv | .0406291 | .0124893 | 3.25 | 0.005 | .0140087 | .0672495 |
t_chomag | .3609517 | .1047231 | 3.45 | 0.004 | .1377397 | .5841636 |
_cons | 18.23148 | 1.757972 | 10.37 | 0.000 | 14.48446 | 21.97851 |
. xtscc empl invp ch agr ntic infl ide ouv t_chomag, re lag (2) (11 missing values generated)
Regression with Driscoll-Kraay standard errors Number of obs = 325
Method: Random-effects GLS regression Number of groups = 21
Group variable (i): code_pays Wald chi2(8) = 782.41
maximum lag: 2 Prob > chi2 = 0.0000
corr(u_i, Xb) = 0 (assumed) overall R-squared = 0.4371
empl | Coef. | Drisc/Kraay Std. Err. | t | P>|t| | | [95% Conf. | Interval] |
invp | -.0568664 | .0258058 | -2.20 | 0.044 | | -.1118702 | -.0018627 |
ch | -1.906428 | 3.551738 | -0.54 | 0.599 | -9.476778 | 5.663922 |
agr | -.1296336 | .0417633 | -3.10 | 0.007 | -.21865 | -.0406173 |
ntic | .0126009 | .012344 | 1.02 | 0.324 | -.0137096 | .0389114 |
infl | .0037798 | .0146706 | 0.26 | 0.800 | -.0274898 | .0350495 |
ide | .0093416 | .0166659 | 0.56 | 0.583 | -.0261809 | .0448641 |
ouv | .0435586 | .0177804 | 2.45 | 0.027 | .0056607 | .0814565 |
t_chomag | .3842972 | .0780637 | 4.92 | 0.000 | .2179084 | .5506861 |
_cons | 12.20217 | 7.318198 | 1.67 | 0.116 | -3.3962 | 27.80054 |
sigma_u | 5.158641 | | | | | |
sigma_e | 2.2459527 | | | | |
rho | .84065192 | (fraction of | variance due | to | u_i) |
References
| [1] |
Adams, C. A. (2004), «The Ethical, Social and Environmental Reporting-Performance Portrayal Gap». Accounting, Auditing & Accountability Journal, 17, 731-757.
http://dx.doi.org/10.1108/09513570410567791
|
| [2] |
Adeosun, O. A., Olomola, P. A., Adedokun, A., Ayodele, O. S. (2020), Public investment and inclusive growth in Africa. International Journal of Social Economics, 47(12), 1669-1691.
|
| [3] |
Apetun A. (2016), «Nigria’s ICT contribution to GDP nears 11%», The Gardian. 30 Septembre 2016.
https://guardian.ng/technology/nigerias-ict-contribution-to-gdp-nears-11/
|
| [4] |
Alfaro, S. C. and Gomes, L. (2001), «Modelling Mineral Aerosol Production by Wind Erosion: Emission Intensities and Aerosol Distributions in Source Areas». Journal of Geophysical Research, 106, 18075-18084.
https://doi.org/10.1029/2000JD900339
|
| [5] |
Ali, I. (2007), «Pro-Poor to Inclusive Growth: Asian Prescriptions». ERD Policy Briefs, Manila: Asian Development Bank, No. 48.
|
| [6] |
Ali, I., & Son, H. H. (2007a), «Measuring inclusive growth». Asian Development Review, 24(1), 11-31.
|
| [7] |
Ali, I., & Son, H. H. (2007b), «Defining and measuring Inclusive Growth: application to the philippines». ERD working paper series, No. 98 Asian Development Bank ADB.
|
| [8] |
Altinok, N. (2007), ‘Human capital and growth: the contribution of international surveys of student achievement’. Public economic, 18-19/ 2006/1-2.
|
| [9] |
Anand, R., Mishra, S., & Peiris, S. J. (2013), «Inclusive Growth: measurements and determinants. International Monetary Fund, Washington, DC, Vol. 13.
|
| [10] |
Aoyagi, C. & Ganneli, G. (2015), «Asia’s quest for inclusive growth revisited». Journal of Asian Economics, 40, 29-46.
|
| [11] |
Berg, A. & Ostry, D. J. (2011), «Equality and efficiency». Finance et Développement, International Monetary Fund, 48(3).
|
| [12] |
Boccanfuso, D., Savard, L., Savy, B. (2009), ‘Human capital and growth: evidence from African countries’. Groupe de recherche en Economie et Développement International. Working paper, 09-15.
|
| [13] |
Bourguignon, F. 2004), «The Social Consequences of economic Growth» Forthcoming in the Handbook of Economic Growth, Aghion and Durlauf, editors, Amsterdam. Elsevier.
|
| [14] |
Brenneman, A., and M, Kerf, (2002), “Infrastructure and Poverty Linkages: A Literature Review”. The World Bank, Mimeo.
|
| [15] |
Calderón, C. and Chong, A. (2004), "Volume and Quality of Infrastructure and the Distribution of Income: An Empirical Investigation." Review of Income and Wealth. 50, 87-105.
|
| [16] |
Calderón, C., & Servén, L. (2008), «Infrastructure and Economic Development in Sub-Saharan Africa». Policy Research Working Paper (4712).
|
| [17] |
Cha’Ngom, N. & Tamokwe, P. G. B. (2019), «Do migrant remittances contribute to inclusive growth in Sub-Saharan Africa?’ Munich Personal RePEc Archive, No. 91321.
|
| [18] |
Commission on Growth and Development (2008), «Rapport sur la croissance: stratégie pour une croissance durable et un développement inclusif». Washington, DC, Banque mondiale.
|
| [19] |
Datt, G. & Ravallion, M. (1992), Growth and Redistribution Components of Changes in Poverty Measures: A decomposition with applications to Brasil and India in 1980s. Journal of Development Economics, 38 (1992) 275-295.
|
| [20] |
Dollar, D. & Kraay, A. (2002), «Growth is good for the poor». Journal of Economic Growth 7(3), 195-225.
|
| [21] |
Dormont, B. (1989), Introduction à l’économétrie des données de panel. Thérie et applications à des échantillons d’entreprises, Paris: CNRS Editions, 125 P.
|
| [22] |
Fan, S. (2004), ‘Public investment and poverty: initial evidence from East Africa and policy implications for West Africa’. Institut d'Economie Rurale (IER), Bamoko.
|
| [23] |
Galor, O. & Zeira, J. (1993), «Income Distribution and Macroeconomics». Review of Economic Study, 60(1), 35-52.
|
| [24] |
Gleizes, J. (2000), «human capital». Multitudes, 111-112.
|
| [25] |
Hussein, K., Mukungu, A., & Awel, Y. (2018), Drivers of inclusive growth in Africa: project United Nations. Economic Commission for Africa; Addis Ababa. © NAKED CEA.
|
| [26] |
ILO (2019), International Labour Organization.
https://www.ilo.org/dyn/normlex/en/f?p=NORMLEXPUB:12100:0::NO::P12100_ILO_CODE:C107
|
| [27] |
ILO (2012), World of Work Report. Geneva: International Labour Office.
|
| [28] |
International Monetary Fund (2007). «Globalization and inequality». World Economic Outlook, Chapter 4, October, washington DC.
|
| [29] |
Jalles, J. T., de Mello, L. (2019), «Cross-country evidence of the determinants of inclusive growth episodes ». Review of Development Economics 23(4) 1818-1839.
|
| [30] |
Kakwani, N., & Pernia, E. (2000), «What is Pro-poor Growth?». Asian Development Review, 18(1), 1–16.
|
| [31] |
Kamanzi, P. C. (2006), ‘Influence of human capital and social capital on employment characteristics among postsecondary graduates in Canada’.
|
| [32] |
Khan, M. S., Senhadji, A. S. (2000), Threshold effects in the relationship between inflation and growth, IMF Working Paper, WP/00/110.
|
| [33] |
Khandker, S., Bakht, Z., & Koolwal, G. (2006), «The Poverty Impact of Rural Roads: The Poverty Impact of Rural Roads: Evidence from Bangladesh». World Bank Policy Research Working Paper3875, 1–34.
|
| [34] |
Kolawole, B., O. (2016), «Government spending and inclusive growth relationship in Nigeria: An empirical investigation». Zagreb International Review of Economics and Business, 19 (2), 33-56.
|
| [35] |
Kraay, A. (2004), «When is growth pro-poor?». Cross-Country Evidence. IMF working paper No. 04/47.
|
| [36] |
Kuznets, S. (1955), «Economic growth and income inequality». American Economic Review, 65(1): 1-28.
|
| [37] |
Lopez, H. (2004), «Macroeconomics and Inequality». The World Bank Research Workshop, Macroeconomic Challenges in Low Income Countries, Washington, DC.
|
| [38] |
Mc Culloch, N. and Baulch, B. (1999). «Assessing the poverty bias of economic growth: Methodology and an application to andhra pradesh and uttar pradesh». Institute of development studies working paper, University of sussex, United Kingdom draft.
|
| [39] |
McKinley, T. (2010), «Inclusive growth criteria and indicators: an inclusive growth index for diagnosis of country progress». ADB Sustainable Development Working Paper, No. 14, Banque asiatique de développement, Mandaluyong City (Philippines).
|
| [40] |
Muhammad, L. (2017), «Health care spending and inclusive growth in India: An empirical investigation». Advances in Economics and Business Management, 4 (3), 160-163.
|
| [41] |
Ndiaye, A., Dieye, A. & Coly, S. (2020), ‘Public investment, inclusive growth and well-being in Senegal’, Working Paper.
https://doi.org/10.13140/RG.2.2.34314.29127
|
| [42] |
Ningaye, P. (2017), «Role of microfinance in financing inclusive growth in Africa- case of Cameroon». Proceedings of the Fifth Congress of African Economists, Vol. 2, 166-181.
|
| [43] |
Njong, A. M. (2010), «The effects of educational attainment on poverty reduction in Cameroon». Journal of Education Administration and Policy Studies, 2(1), 1–8.
|
| [44] |
Organisation for Economic Co-operation and Development (2007), «Vers une croissance pro-pauvre: orientation à l’intention des donneurs» ISBN 978-92-64-02479-3.
|
| [45] |
Organisation for Economic Co-operation and Development (2018), ‘Effective public investment for inclusive and sustainable territorial development’ in Morocco-OECD dialogue on territorial development policies: Issues and Recommendations for Coordinated Public Action, OECD Publishing, Paris.
|
| [46] |
Osmani, C. (2005), «Defening pro-poor growth». Washington One pager 9, january, International Poverty Center, UNDP.
|
| [47] |
Oyinlola, M. A., Adedeji, A. (2015), «Human capital, financial sector development and inclusive growth in sub-saharan Africa». Econ Change Restruct 52, 43-66.
|
| [48] |
Oyinlola, M. A., Adedeji, A., Bolarinwa, M. O., Olabisi, N. (2019). «Governance, domestic resource mobilization, and inclusive growth in Sub-saharan Africa». Economic Analysis and Policy. 65.
https://doi.org/10.1016/j.eap.2019.11.006
|
| [49] |
Oyinlola, M. A., Adedeji, A. A., & Onitekun, O. (2021). Human capital, innovation, and inclusive growth in Sub-Saharan African Region. Economic Analysis and Policy, 72, 609-625.
|
| [50] |
Perotti, R. (1993), «Political Equilibrium, Icome Distribution and Growth». Review of Economic Studies, 60 (4), 755-776.
|
| [51] |
Prud’Homme, R. (2004), «Infrastructure et développement ». Washington, DC: banque mondiale.
|
| [52] |
Raheem, I. D., Isah, K. O. & Adedeji, A. A. (2018), « Inclusive growth, human capital development and natural resource rent in SSA». Econ Change Restruct 51, 29-48.
|
| [53] |
Ramos, R. A., Ranieri, R., Lammens, J. W. (2013), «Mapping Inclusive Growth». IPC-IG Working Paper, N°105. International Policy Centre for Inclusive Growth, Brasília.
|
| [54] |
Ravallion, M. & Chen, S. (2003). «Measuring pro-poor growth». Economics Letters, 78(1), 93–99.
|
| [55] |
Sanjaya, I. M. & Nursechafia (2016), «Financial inclusion and inclusive growth: A cross- province analysis in Indonesia ». Buletin of Monetary, Economics Banking, vol 18, No. 3.
|
| [56] |
Sarma, M. (2012), Index of financial inclusion: A measure of financial sector inclusiveness, Working Paper No. 07/2012. Berlin Working Papers on Money, Finance, Trade and Development, Berlin.
|
| [57] |
Suhrcke, M., McKee, M., Stuckler, D., Sauto Arce, R., Tsolova, S., & Mortensen, J. (2005), «The contribution of health to the economy in the European Union». Office for Official Publications of the European Communities.
|
| [58] |
Tella, S. A. & Alimi, O. Y. (2016), «Determinants of inclusive growth in Africa: Role of health and demographic changes». African Journal of Economic, Review 4(2), 138-146.
|
| [59] |
Ullah and Munir (2018). «Inclusive Growth in Pakistan: Measurement and Determinants» The Pakistan Journal Of Social Issues, Special Issue (June 2018) 24 September 2018, 150-162.
|
| [60] |
UN (2000). United Nations Millennium Declaration. 55/2 (PDF). United Nations General Assembly.
|
| [61] |
World Bank (2018). ‘Poverty and shared prosperity report 2018: completing the poverty puzzle’.
|
| [62] |
Zulfiqar, k. (2018). «Fiscal policy for inclusive growth: A case study of Pakistan». Pakistan Economic and Social Review, 56(1), 21-4.
|
Cite This Article
-
-
@article{10.11648/j.jwer.20251401.17,
  author = {Gildas Boris Dudjo Yen and Armel Ndolembaye},
  title = {Public Investment and Inclusive Growth in Sub-saharan Africa
},
  journal = {Journal of World Economic Research},
  volume = {14},
  number = {1},
  pages = {80-98},
  doi = {10.11648/j.jwer.20251401.17},
  url = {https://doi.org/10.11648/j.jwer.20251401.17},
  eprint = {https://article.sciencepublishinggroup.com/pdf/10.11648.j.jwer.20251401.17},
  abstract = {The objective of this work is to study the effects of public investments on the inclusiveness of growth in Sub-Saharan Africa. The question of the inclusiveness of growth is rekindling the debate around economic policies aimed at reducing inequalities, combating poverty and promoting sustainable development. To lift the majority of Africans out of poverty, growth must be more inclusive. Job opportunities must be created by improving the business environment and the investment climate that will allow the private sector to flourish. Most importantly, landlocked areas must be linked to growth poles through better infrastructure and greater regional integration, both within countries and across national borders. Inclusive growth will also require the effective transformation of the continent's natural wealth into created wealth, in particular by strengthening human capital. Wise, efficient and sustainable management of natural resources that benefits all Africans. The data used in this research are from secondary sources and cover 21 SSA countries over the period 2000-2020. With reference to the existing literature, three indicators have been used to capture inclusive growth. We used an indicator called the inclusive growth index, which has two dimensions: income growth and income distribution. The other two indicators are poverty and productive employment. Public investment is measured by general government gross fixed capital formation as a percentage of GDP. The econometric approach is based on panel regressions. The results of the various estimates show that public investments have a significant and negative impact on the inclusive growth index and on productive employment. Furthermore, no significant effect of public investments was found on poverty. This research thus shows that public investments have a negative impact on inclusive growth in SSA.
},
 year = {2025}
}
 Copy
|
 Download
-
TY  - JOUR
T1  - Public Investment and Inclusive Growth in Sub-saharan Africa

AU  - Gildas Boris Dudjo Yen
AU  - Armel Ndolembaye
Y1  - 2025/05/29
PY  - 2025
N1  - https://doi.org/10.11648/j.jwer.20251401.17
DO  - 10.11648/j.jwer.20251401.17
T2  - Journal of World Economic Research
JF  - Journal of World Economic Research
JO  - Journal of World Economic Research
SP  - 80
EP  - 98
PB  - Science Publishing Group
SN  - 2328-7748
UR  - https://doi.org/10.11648/j.jwer.20251401.17
AB  - The objective of this work is to study the effects of public investments on the inclusiveness of growth in Sub-Saharan Africa. The question of the inclusiveness of growth is rekindling the debate around economic policies aimed at reducing inequalities, combating poverty and promoting sustainable development. To lift the majority of Africans out of poverty, growth must be more inclusive. Job opportunities must be created by improving the business environment and the investment climate that will allow the private sector to flourish. Most importantly, landlocked areas must be linked to growth poles through better infrastructure and greater regional integration, both within countries and across national borders. Inclusive growth will also require the effective transformation of the continent's natural wealth into created wealth, in particular by strengthening human capital. Wise, efficient and sustainable management of natural resources that benefits all Africans. The data used in this research are from secondary sources and cover 21 SSA countries over the period 2000-2020. With reference to the existing literature, three indicators have been used to capture inclusive growth. We used an indicator called the inclusive growth index, which has two dimensions: income growth and income distribution. The other two indicators are poverty and productive employment. Public investment is measured by general government gross fixed capital formation as a percentage of GDP. The econometric approach is based on panel regressions. The results of the various estimates show that public investments have a significant and negative impact on the inclusive growth index and on productive employment. Furthermore, no significant effect of public investments was found on poverty. This research thus shows that public investments have a negative impact on inclusive growth in SSA.

VL  - 14
IS  - 1
ER  -
Copy
|
Download

 Share This Article
 Twitter
 Linked In
 Facebook