Research Article | | Peer-Reviewed

Assessing Tomato Market Outlets Efficiency in Andhra Pradesh, India - Evidence from PCA-DEA Analysis

Received: 30 September 2025     Accepted: 14 October 2025     Published: 31 October 2025
Views:       Downloads:
Abstract

The study aims to evaluate and compare the marketing efficiency of five tomato marketing channels—local wholesalers, Rythu Bazars, processors, retail malls, and restaurants—in terms of net price realization for smallholder farmers in Andhra Pradesh. A two-stage sampling framework was employed, selecting Ananthapuramu district due to its prominence in tomato cultivation and further narrowing the focus to Kalyanadurgam and Settur mandals. A total of 300 smallholder tomato farmers (each with landholding ≤2 hectares) were selected, with 60 farmers representing each marketing channel. Data are collected through structured surveys and official secondary sources. Principal Component Analysis findings reveal distinct structural patterns across channels, with the number of significant principal components varying accordingly. Local wholesalers and processors exhibit ten principal components, capturing 70.66% and 70.95% of variance, respectively, indicating structured market behaviour. Rythu Bazars, characterized by direct producer-to-consumer transactions, demonstrate eleven principal components explaining 76.39% of variance, suggesting greater heterogeneity in pricing mechanisms and operational dynamics. Retail malls and restaurants, with ten principal components each, account for 71.09% and 70.56% of variance, respectively, reflecting structured market behaviour and dominant procurement strategies. Findings from Data Envelopment Analysis revealed significant efficiency disparities among the five marketing channels. Retail malls (Channel 4) emerge as the most efficient channel, with a mean Variable Returns to Scale Technical Efficiency score of 0.982, while local wholesalers (Channel 1) register the lowest efficiency (0.918) due to resource misallocation and intermediary costs. Scale efficiency analysis indicates that Channels 1 and 2 (local wholesalers and Rythu Bazars) exhibit increasing returns to scale, suggesting potential efficiency gains through capacity expansion. Overall, retail malls and Rythu Bazars demonstrate higher efficiency scores, ensuring better price transparency and reduced intermediary costs. The study underscores the need for enhanced infrastructure, digital market integration, producer cooperatives, and cold storage facilities to improve market access and efficiency.

Published in International Journal of Agricultural Economics (Volume 10, Issue 6)
DOI 10.11648/j.ijae.20251006.12
Page(s) 343-364
Creative Commons

This is an Open Access article, distributed under the terms of the Creative Commons Attribution 4.0 International License (http://creativecommons.org/licenses/by/4.0/), which permits unrestricted use, distribution and reproduction in any medium or format, provided the original work is properly cited.

Copyright

Copyright © The Author(s), 2025. Published by Science Publishing Group

Keywords

Smallholders, Market Channels, Factor Loadings, Scale Efficiency, Digital Inclusion, Price Realization

1. Introduction
Tomatoes remain a vital crop globally, playing an essential role in food security, enhancing nutritional value, and supporting rural economies. Grown extensively across various nations, including China, India, Turkey, United States, Egypt, Italy, and Mexico, tomatoes are integral to both domestic consumption and international trade. India, in particular, stands as the second-largest producer, producing over 20 million tonnes of tomatoes in TE 2023. India's tomato cultivation spanned an area of 0.85 million hectares with an average yield of 24.56 tonnes per hectare . Within India, Madhya Pradesh emerges as the leading tomato producer, contributing 16.4 per cent to national production in 2023-24. Andhra Pradesh follows closely, securing second place with 11.4 per cent of India's total tomato output during the same period .
Market dynamics governing vegetable distribution are undergoing profound transformations worldwide, propelled by the emergence of innovative linkages connecting farmers with processors, retail establishments, and institutional buyers. In the United States, digital platforms are fundamentally altering conventional sales structures, fostering direct interactions between producers and consumers. Advanced technologies like big data analytics, blockchain applications and Internet of Things are improving supply chain efficiency, improving transparency and strengthening traceability mechanisms. Europe is witnessing a surge in digital integration within agricultural commerce, enabling producers to access sophisticated market systems. Accelerated adoption of digital platforms facilitates seamless supply chain optimization, fortifies market linkages, and augments competitive positioning. Meanwhile, China is experiencing an unprecedented expansion in e-commerce applications within vegetable trade, with online-to-offline food delivery models rapidly capturing market share. Increasing consumer inclination toward digital purchasing is amplifying demand for direct farm-to-household supply chains. Within Andhra Pradesh, India particularly in Ananthapuramu district, smallholder farmers are actively engaged with direct marketing avenues, circumventing conventional intermediaries. Processors, retail outlets, and restaurants are demonstrating heightened interest in procuring locally sourced produce, thereby diversifying sales opportunities for small-scale cultivators. Despite the momentum gained by modernized marketing strategies, traditional sales channels continue to dominate transactions, reflecting an ongoing coexistence between legacy distribution networks and contemporary commercial models.
Smallholders encounter formidable constraints when attempting to access remunerative markets, consequently restricting income potential and long-term economic viability. Substantial transaction costs—including expenses associated with transportation, buyer identification, and price negotiations—coupled with logistical inefficiencies and inadequate storage infrastructure, significantly diminish net earnings . Limited asset endowments, characterized by constrained land holdings, insufficient irrigation facilities, and inadequate post-harvest management, further impede productivity and market competitiveness . Infrastructural deficiencies exacerbate these challenges, exacerbating post-harvest losses and heightening dependency on intermediaries who frequently dictate unfavourable pricing structures . Information asymmetry further weakens bargaining power, rendering producers vulnerable to income volatility. Consequently, market channel selection assumes strategic importance in ensuring profitability and resilience. Given the perishable nature of tomatoes, logistical considerations, fluctuating demand patterns, and prevailing pricing structures must be meticulously evaluated before determining optimal marketing avenues.
Local wholesale markets enable rapid disposal of produce, yet farmers often encounter exploitative pricing mechanisms imposed by intermediaries. Prices tend to be suppressed under presumptions of inferior quality, limiting profit margins and financial security. Although Rythu Bazars provide direct marketing avenues, several structural and operational constraints hinder their efficacy. Limited market infrastructure, inadequate storage facilities, and price fluctuations pose challenges, while logistical bottlenecks and inconsistent consumer footfall restrict sales volumes . Additionally, farmers navigating these platforms often struggle with price volatility, lack of institutional support, and insufficient market intelligence, affecting decision-making and income stability. Within this evolving landscape, Farmer Producer Organizations (FPOs) emerge as pivotal institutions fostering collective empowerment, cost efficiencies, and enhanced price realization. By consolidating production and streamlining distribution, these entities enable smallholders to negotiate better terms, access modern value chains, and secure remunerative returns. Strengthened market positioning facilitates seamless integration with processors, retail malls, and restaurant chains, mitigating risks associated with dependence on singular distribution networks. Expanding engagement with contemporary marketing frameworks fosters broader economic participation, promoting financial viability and sectoral competitiveness. By leveraging institutional support, infrastructure enhancements, and digital market linkages, smallholder cultivators can transcend traditional constraints, unlocking pathways to sustainable growth and long-term economic prosperity.
Existing research had extensively explored factors influencing farmers’ market channel choices, primarily focusing on socio-economic determinants, access to market information, and infrastructural constraints. Studies have predominantly examined parameters such as education levels, landholding size, institutional support, and transaction costs that influence selection patterns. However, these studies often overlook a critical dimension—marketing efficiency. A substantial research gap exists in evaluating the comparative marketing efficiency of different marketing channels in terms of price realization. Solely identifying determinants of market channels participation does not sufficiently inform strategies for maximizing profitability. Analyzing marketing efficiency across different marketing channels provides deeper insights and enables identification of optimal pathways that yield superior economic outcomes for producers. Given rising integration with modern retail systems, processors, and restaurants, comprehensive framework assessing marketing efficiency is essential.
In this context, the present study was undertaken to conduct a comparative evaluation of marketing efficiency across various distribution channels, including local wholesalers, Rythu Bazars, processors, retail malls, and restaurants. The primary objective is to systematically assess the relative effectiveness of these channels in terms of net price realization of smallholder tomato farmers. Findings from this research will contribute to strategic interventions that enhance farmer participation in remunerative markets, promote sustainable commercialization, and strengthen supply chain efficiencies. Ultimately, the study aspires to guide stakeholders in fostering a more equitable, transparent, and economically viable marketing landscape for agricultural producers.
2. Review of Literature
Recent studies have provided in-depth insights into the efficiency of agricultural marketing channels, highlighting key determinants of farmer profitability, supply chain performance, and market integration. conducted an empirical study on marketing efficiency in Kolar, India, across four major farming systems—Crop + Sheep, Crop + Dairy, Crop + Dairy + Horticulture, and Crop + Dairy + Sericulture—using Shepherd's and Acharya's methods. Their findings indicated that government procurement through Agricultural Produce Market Committees (APMCs) was the most efficient channel for selling finger millet, whereas direct farmer-to-consumer transactions played a dominant role in sheep marketing. The study also identified price fluctuations, inadequate market information, and high transportation costs as critical challenges, emphasizing the need for infrastructural improvements and intermediary reductions to enhance farmer profitability and income stability. Similarly, examined institutional reforms in India's agricultural supply chains, focusing on the revisions to the APMC Act, including the Model APMC Act of 2003, which introduced private markets, direct purchase centers, contract farming, and public–private partnerships. The study demonstrated that these reforms significantly enhanced spatial efficiency in staple crop markets, particularly for rice and wheat, and recommended further infrastructural developments to improve market integration and supply chain performance. Expanding on marketing structures, conducted a comparative analysis of organized retail collection centers versus traditional marketing channels for vegetable farmers in Ranga Reddy district, Telangana. The study revealed organized collection centers provided greater marketing efficiency, reinforcing the importance of improved post-harvest management strategies to enhance farmer income in contrast to traditional markets. Similarly, further exploring price variations across marketing channels, analyzed the impact of different sales outlets on the prices received by farmers, utilizing farm-level data. The study found that selling through mandis allowed local crop producers to secure price premiums ranging from 13 per cent to 73 per cent compared to private traders. However, high-value crop producers received lower prices in mandis, illustrating need for differentiated marketing strategies rather than one-size-fits-all approach. Complementing these findings, examined factors influencing farmers’ selection of agricultural marketing channels, particularly among garden pea producers in India. The research identified household characteristics such as education, income, farming experience, access to storage facilities, and market information as significant determinants in marketing channel choices. The study also highlighted that direct marketing channels provided higher gross and net marketing margins for farmers, reinforcing their economic advantage over intermediary-heavy alternatives. Recognizing the complexity of agricultural marketing, proposed an innovative methodology to assess marketing efficiency by incorporating all stakeholders within the marketing system. Using primary data from Delhi’s agricultural markets, the study emphasized the necessity of a comprehensive evaluation framework that accounts for cooperative societies, intermediaries, processing units, and consumers. The results demonstrated the importance of an integrative approach in assessing and improving marketing channel efficiency.
Beyond India, highlighted about optimizing production and distribution of fresh food that presents a complex challenge due to its perishability and numerous factors influencing efficiency. This study examines 15 prefecture-level cities in China from 2008 to 2020, compiling data on rural economic development and agricultural ecological recovery. Findings indicate a pattern of linear economic growth with regional disparities, as evidenced by the rural economy’s composite index, which ranges from 0.422 to 0.622. A mixed-integer programming model is proposed to integrate various constraints, demonstrating that the collaborative planning framework can improve farmers’ distribution revenues by 7.98 per cent compared to independent decision-making. Based on multiple decision scenarios, strategic recommendations are provided, emphasizing the need for careful product sorting and bundling, partnerships with reliable logistics services, and timely deliveries. analyzed the distribution channels used by small farms in Eastern Europe, particularly in Moldova, Romania, and Serbia. The study found that smallholder farmers faced considerable marketing constraints due to limited infrastructure and policy support, which significantly impacted market efficiency. The comparative analysis revealed that access to well-integrated supply chains was a crucial determinant of profitability and sustainability for small farms. extended this research by examining pressures on agricultural distribution channels in Europe, identifying a growing shift toward direct sales models. Their study estimated that approximately 15 per cent of European farms now sell over half of their produce through short distribution channels, reflecting a growing producer preference for minimizing intermediary involvement to maximize efficiency and revenue. provided a historical perspective on transformative role of digital technologies in agricultural marketing. Their research, focusing on West Africa and India, analyzed how mobile phone coverage and e-commerce platforms enhanced producer market access, reduced market failures, and lowered transaction costs by improving price transparency and weakening the monopsony power of traders. The study underscored the revolutionary impact of digital agriculture in enhancing marketing efficiency and farmer profitability.
Collectively, these studies underscore the critical role of institutional reforms, infrastructure enhancement, direct-sales models, and digital integration in improving agricultural marketing efficiency. They emphasize the necessity for targeted policy interventions that consider regional disparities, crop-specific market dynamics, and the transformative influence of technology in agricultural trade. However, despite extensive research on agricultural marketing efficiency, no study has specifically employed the Principal Component Analysis-Data Envelopment Analysis (PCA-DEA) approach to systematically evaluate and compare efficiency levels across diverse marketing channels. Given the complexity and heterogeneity of agricultural markets, a robust methodological framework that integrates dimensionality reduction with efficiency measurement is essential for drawing precise and actionable insights. In this context, the present study fills a critical research gap by leveraging PCA-DEA to assess marketing efficiency across selected channels, offering a more comprehensive and data-driven perspective on performance variations and optimization strategies within the agricultural marketing landscape.
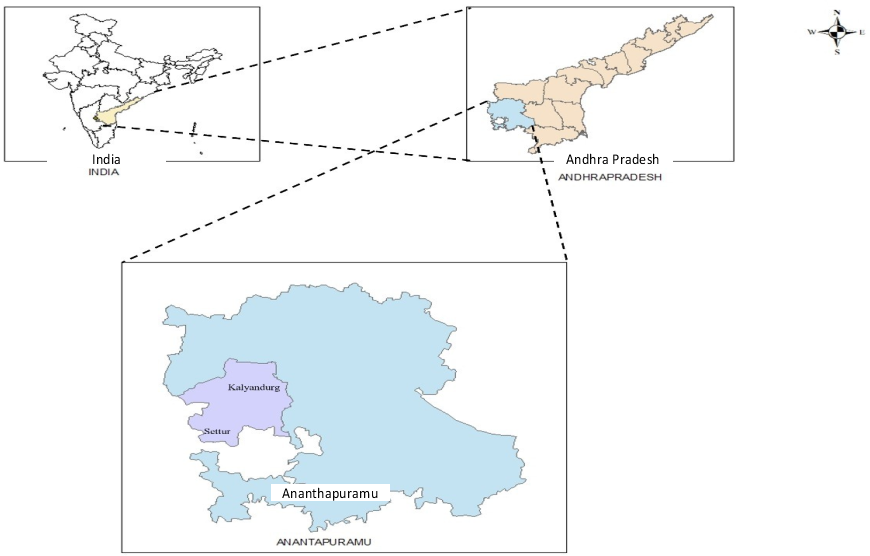
Figure 1. Location Map of selected mandals in Ananthapuramu, Andhra Pradesh
3. Methodology
Andhra Pradesh exhibits exceptional potential in tomato cultivation, with several districts maintaining a strong presence in both cultivated area and output. Among the leading regions, Ananthapuramu, Annamayya, and Sri Satya Sai have emerged as significant contributors, particularly following the administrative reorganization and formation of new districts in 2022. Collectively, these districts contribute significantly to market supply, ensuring steady availability while supporting economic sustainability in horticultural development.
3.1. Selection of Sample
Ananthapuramu emerges as a dominant contributor, covering an extensive 0.17 lakh ha hectares in the 2023-24 season, surpassing its five-year average of 0.11 lakh hectares . This district also leads in production, achieving an impressive output of 7.33 lakh tonnes. Annamayya follows closely, cultivating 0.09 lakh hectares during the same period, a figure slightly below its five-year average of 0.13 lakh hectares. Nevertheless, its production remains substantial, reaching 5.13 lakh tonnes. Sri Satya Sai district, occupying 0.08 lakh hectares, records a total output of 4.39 lakh tonnes, reflecting significant agricultural activity. These three districts, long established as pivotal centers of tomato production, highlight the substantial economic significance of this crop. Historical data further highlights Chittoor’s past prominence, maintaining an average cultivation of 0.06 lakh hectares over five years. To ensure a methodologically robust and representative selection of smallholder tomato farmers, a two-stage sampling framework was employed. In the initial phase, Ananthapuramu was purposefully selected for the study considering its prominence in tomato cultivation. Within this district, Kalyanadurgam and Settur mandals, exhibiting the most extensive cultivation areas, were identified as focal study sites. Further refinement led to the selection of two villages per mandal—Palavoy and Kodipalli from Kalyanadurgam, alongside Chintarlapalli and Ayyagarlapalli from Settur (Figure 1). The subsequent stage involved compiling a comprehensive registry of smallholder tomato farmers, specifically those with a landholding size of two hectares or less, derived from official records maintained by the Department of Horticulture in the designated villages. Extensive consultations with local Horticulture Officers indicated that 3,740 smallholder farmers were actively engaged in tomato cultivation and marketing across these locations in 2024. To determine an optimal sample size, formula was applied as follows:
n=N1+N(e)2
where n= sample size, N= target population(3740)and e= margin of error(7%)
n=37401+3740(0.07)2=259
Accordingly, a representative sample size of 300 was established, rounded to the nearest hundred for methodological rigor. Tomato cultivation remains instrumental in rural development, fostering employment generation and ensuring a stable income for farming households. However, multiple constraints persist, including escalating transaction costs, volatile pricing dynamics, infrastructural inadequacies, inefficient storage systems, and restricted access to timely and accurate market intelligence, collectively undermining profitability and sustainability . Identifying marketing channels with optimal efficiency becomes imperative to mitigate these challenges and enhance farmer resilience within competitive agricultural markets. In this context, five predominant distribution channels have been identified to analyze smallholder tomato farmers' participation in diverse marketing networks. First, local wholesalers function as intermediaries, procure produce directly from farmers at farm gates, transact in Madanapalle market (Asia's largest tomato market) and Bangalore and ensuring immediate liquidity but often yielding lower margins due to intermediary costs. Second, Rythu Bazars, serve as government-facilitated marketplaces, eliminate middlemen, fostering direct transactions between producers and consumers while enhancing price transparency and ensuring competitive rates. Third, processors (located in Ananthapuramu and Bangalore) represent another critical avenue, converting fresh tomatoes into value-added products such as puree, sauces, and dehydrated goods, stabilizing demand and mitigating post-harvest losses through structured procurement systems. Fourth, retail malls provide an organized marketing framework where farmers establish direct supply relationships with supermarket chains, benefiting from premium pricing and assured procurement while meeting stringent quality and grading standards. Lastly, restaurants offer a direct market through collaborations with farmer collectives, facilitating bulk sales and enhancing traceability—an increasingly valued aspect within hospitality sectors . Sixty farmers from each channel are randomly selected to prioritize efficient channels in transacting tomato . However, due to variations across multiple parameters, these marketing channels require a standardized set of criteria for meaningful comparison. Based on preliminary discussions with local horticultural farmers, 23 common indicators have been identified (Table 1). Each channel is assessed according to these predefined criteria, incorporating both quantitative and qualitative variables. Qualitative variables are ranked on a scale from 0 to 1, where a higher value signifies greater intensity of the respective attribute. These assigned values serve as foundational inputs for evaluating the proposed methodology.
Table 1. Names and definitions of selected variables.

Factor

Abbreviation

Description

Unit of measurement

Net Price Received

NPR

Net Price Received by the farmer in transacting produce

Rs/qtl

Land Holding Size

LHS

Land holding under tomato cultivation

Acreage

Distance

DIST

Physical distance from farm to transaction point

Kilometers

Marketable Surplus

MBLS

Actual quantity sold in the market by the farmer

Quintals

Cold Storage Cost

CSC

Cost incurred for storing tomatoes in cold storage facilities

Rs/qtl

Transaction Cost

TC

Expenses related to selling, such as transportation, handling, loading and unloading etc

Rs/qtl

Quality & Grading of Produce

QP

Extent of sorting, grading, and quality control measures applied before sale

0 – 1 scale*

Market Linkages & Contract Farming

ML

Farmer's access to organized market channels and contract farming agreements

0 – 1 scale

Access to Market Information

AMI

Availability and utilization of market-related data for pricing and demand trends

0 – 1 scale

Prompt Payment of Sales Proceeds

PPSP

Timeliness of payments received from buyers after selling produce

0 – 1 scale

Storage Facility

SF

Availability and adequacy of on-farm or off-farm storage structures

0 – 1 scale

FPO Membership

FPOM

Farmer’s membership in a FPO for collective benefits

0 – 1 scale

Delivery Time

DT

Time taken from harvesting to final delivery at the market or buyer

0 – 1 scale

Consumer Preferences for Organic Food

CP

Influence of consumer demand for organic tomatoes on farmer’s sales

0 – 1 scale

Price Volatility

PV

Degree of fluctuation in market prices affecting farmer earnings

0 – 1 scale

Inventory Costs

IC

Costs associated with holding unsold stock, including wastage

0 – 1 scale

Quantity Loss

QL

Loss of tomatoes due to spoilage, mishandling, or delayed sales

0 – 1 scale

Quality of Roads Infrastructure

RI

Condition and accessibility of roads affecting transportation efficiency

0 – 1 scale

Bargaining Power

BP

Farmer’s ability to negotiate better prices and terms with buyers

0 – 1 scale

Digital Integration

DI

Use of digital platforms and mobile applications for trading and market access

0 – 1 scale

Market Financing

MF

Availability of credit, loans, and financial support for production and marketing

0 – 1 scale

Intermediary Influence

II

Extent of dependence on middlemen in the supply chain and their impact on profits

0 – 1 scale

Climate-Resilient Practices

CRP

Adoption of techniques that enhance resilience to climate variability and risks

0 – 1 scale

Changing Retail Structures

CR

Impact of evolving retail trends, such as supermarkets and e-commerce, on sales

0 – 1 scale

Note: - *values represent scores for each channel according each indicators (parameters) on 0-1 scale
3.2. Data
This research relied on both primary and secondary data sources. Primary data collection involved administering a pre-tested survey schedule through face-to-face interviews with smallholder tomato farmers across selected locations. To ensure relevance, validity, and reliability, an initial pilot survey was conducted with 30 respondents in Settur mandal of Ananthapuramu. Insights derived from this preliminary exercise facilitated necessary refinements, enhancing the overall effectiveness of the structured schedule. Secondary data was sourced from official records, including publications from Directorate of Economics and Statistics of Andhra Pradesh, and statistical handbooks specific to Ananthapuramu.
3.3. Analytical Framework
3.3.1. Descriptive Statistics
These were utilized to summarize and elucidate the characteristics of household attributes marketing facilities and services. Key indicators included percentages, means and Coefficient of Variation (CV).
3.3.2. Principal Component Analysis (PCA)
This was employed to mitigate multicollinearity among determinants shaping smallholder farmers' selection of tomato marketing channels. Multiple variables under consideration are consolidated into a reduced set of principal components, capturing essential patterns while enhancing analytical precision. Let X=X1,X2,,Xp' represent variables under discussion, while F=F1,F2,,Fm' denote extracted primary components or factors,ε=ε1,ε2,,εp' signifies residual items. The factor loading matrix, denoted as A, where aij represents individual factor loads, establishes the connection between observed variables and underlying factors. This relationship can be formally expressed through Equation (1), providing a structured representation of how factors influence variables of interest:
X1=a11F1+a12F2++a1mFm+ε1X2=a21F1+a22F2++a2mFm+ε2Xp=ap1F1+ap2F2++apmFm+εp,A=a11a12a1ma21a22a2map1ap2apm(1)
Through PCA, the 23 variables listed in Table 1 are transformed into a smaller set of Principal Components (PCs), each capturing distinct dimensions of influence. These components are categorized as different factors reflecting key determinants in DEA to ascertain marketing efficiency in terms of NPR by sample farmers across different marketing channels. PCs represent uncorrelated linear combinations, ordered by variance in descending magnitude. introduced additional constraints, ensuring that weight assigned to PC1 is no less than that of PC2, weight of PC2 is no less than that of PC3, and so forth .
3.3.3. Data Envelopment Analysis (DEA)
The component scores obtained from PCA (market channel-wise) are considered as inputs in DEA model to analyze and prioritize marketing channels based on marketing (technical) efficiency (TE) scores. So, PCA - DEA model for Decision-Making Unit (DMUa) has the following form :
maxUIC,VNCUPCYPCa(2)
Subject to:
VPCXPCa=1(3)
VPCXPC-UPCYPC0(4)
VPCi-VPCi+10, fori=1,m-1, wheremPCsare analyzed(5)
UPCi-UPCi+10, fori=1,m-1, wheremPCsare analyzed(6)
VPCtLx0(7)
UPCtLy0(8)
VPC,UPC(9)
VPC and UPC are vector of weights assigned to inputs and outputs PCs,XPC and YpC indicate input and output matrix, while Lx and Ly relate to matrix of PCA linear coefficients of input and output data .
4. Results and Discussion
4.1. Descriptive Statistics
The marketing of tomatoes across various distribution channels—Local Wholesales, Rythu Bazar, Processors, Retail Malls, and Restaurants—exhibits notable differences due to variations in infrastructure, transaction costs, storage facilities, and market structures (Table 2). The NPR is highest in Channel 4 (Rs. 5022.50) and Channel 5 (Rs. 4400.83), indicating better price realization, while Channel 1 (Rs. 3088.33) has the lowest due to intermediary costs. CV is lowest for Channel 5 (0.08) and Channel 4 (0.13), reflecting stable pricing, whereas Channel 1 (3.19) shows high price volatility. This suggests that structured and direct marketing channels offer higher and more stable returns to farmers compared to local wholesalers. Local wholesale markets primarily serve as intermediaries between farmers and bulk buyers, handling large volumes of produce. However, farmers operating in this channel often experience lower bargaining power and are susceptible to price fluctuations dictated by middlemen. Additionally, lack of organized storage and direct consumer access increases inventory costs and potential losses due to spoilage. In contrast, Rythu Bazar offers farmers a direct-to-consumer platform, reducing intermediary influence and ensuring relatively lower transaction costs. Farmers benefit from immediate payments and greater control over pricing, but demand fluctuations and perishable nature of tomatoes contribute to higher price volatility, requiring efficient inventory management . Processors, who require a steady and high-quality supply, mitigate market fluctuations by engaging in contract farming and offering stable prices. This provides farmers with a sense of security, though they must meet stringent quality and grading standards. Cold storage costs are high in this channel, given the need to maintain quality during transportation and processing. Delivery time also becomes a critical factor, as delays could impact the quality of tomatoes used in processed products. Retail malls and restaurants, catering to urban consumers, emphasize superior quality, consistency, and extended shelf life. Consequently, these channels incur higher transaction and inventory costs due to stricter grading requirements, storage facilities, and logistical challenges. However, they compensate farmers with premium pricing and reliable payments. Access to market information plays a crucial role in all channels, with structured markets such as processors, malls, and restaurants providing better price predictability. Digital integration is increasingly transforming urban markets, offering farmers direct linkages with buyers through online platforms, thereby reducing intermediary influence. The availability of storage facilities and FPO membership enhances farmers’ ability to manage supply fluctuations, particularly in organized markets where large-scale operations demand consistent supply. Consumer preferences for organic food are significantly shaping retail and restaurant demand, prompting farmers to adopt better quality control measures. Price volatility remains a persistent challenge, particularly in small, unstructured markets like local wholesales and Rythu Bazar, where seasonal oversupply can lead to drastic price drops. Conversely, processors and retail malls experience relatively stable pricing due to longer-term contracts and structured procurement. Inventory costs and quantity loss further highlight inefficiencies in supply chains, with better infrastructure in structured markets helping minimize post-harvest losses. Transportation efficiency, influenced by road infrastructure quality, plays a key role in determining delivery time and product freshness. Bargaining power varies across channels, with farmers in direct-selling markets like Rythu Bazar exercising more control over prices, whereas those in traditional wholesale markets often face unfavorable pricing due to middlemen’s dominance. Market financing, including access to credit and investment opportunities, impacts farmers’ ability to scale operations, with organized channels offering better financial support. Climate-resilient practices and evolving retail structures, such as supermarkets and e-commerce, are shaping long-term trends by offering structured pricing, reduced wastage, and direct farm-to-consumer linkages. Thus, while structured channels like processors, retail malls, and restaurants provide stability and higher returns, direct-selling markets such as Rythu Bazar and Local Wholesales remain vital for small farmers despite challenges related to price volatility, infrastructure constraints, and market power dynamics.
Table 2. Descriptive statistics of variables among selected marketing channels.

Variables

Channel 1

Channel 2

Channel 3

Channel 4

Channel 5

Mean

CV

Mean

CV

Mean

CV

Mean

CV

Mean

CV

NPR

3088.33

3.19

3937.50

1.33

4540.83

0.21

5022.50

0.13

4600.83

0.08

DIST

17.47

0.47

3.80

0.23

40.33

0.67

51.18

0.39

30.68

0.12

LHS

1.71

0.58

2.16

0.47

3.55

0.48

3.76

0.50

3.98

0.50

MBLS

25120.92

0.57

29106.18

0.47

35029.00

0.50

39637.61

0.51

38170.60

0.51

CSC

4.64

0.57

6.65

0.33

12.67

0.38

15.03

0.44

9.06

0.27

TC

19.72

0.27

11.23

0.26

9.10

0.17

61.88

0.12

73.04

0.30

QP

0.25

0.43

0.58

0.21

0.89

0.21

0.84

0.18

0.81

0.24

ML

0.22

0.48

0.29

0.28

0.68

0.19

0.78

0.20

0.75

0.26

AMI

0.24

0.47

0.30

0.26

0.67

0.20

0.77

0.21

0.74

0.27

PPSP

0.37

0.45

0.93

0.28

0.84

0.19

0.91

0.19

0.88

0.28

SF

0.35

0.54

0.20

0.43

0.69

0.22

0.71

0.19

0.64

0.27

FPOM

0.39

0.43

0.20

0.41

0.73

0.21

0.77

0.20

0.76

0.26

DT

0.38

0.44

0.46

0.26

0.77

0.20

0.83

0.21

0.86

0.40

CP

0.27

0.43

0.31

0.25

0.72

0.18

0.77

0.22

0.81

0.21

PV

0.64

1.56

0.74

1.45

0.48

0.27

0.53

0.29

0.50

0.29

IC

0.30

0.47

0.44

0.38

0.56

0.27

0.65

0.27

0.69

0.25

QL

0.30

0.48

0.54

0.30

0.35

0.34

0.45

0.29

0.34

0.30

RI

0.28

0.54

0.48

0.31

0.64

0.27

0.65

0.25

0.51

0.25

BP

0.30

0.48

0.24

0.46

0.62

0.27

0.71

0.26

0.74

0.26

DI

0.29

0.49

0.57

0.32

0.66

0.27

0.65

0.26

0.70

0.24

MF

0.30

0.46

0.35

0.32

0.55

0.33

0.65

0.43

0.81

0.41

II

0.70

0.21

0.11

0.45

0.35

0.30

0.25

0.47

0.20

0.43

CRP

0.27

0.40

0.19

0.40

0.77

0.22

0.81

0.17

0.85

0.13

CR

0.23

0.53

0.20

0.43

0.19

0.40

0.83

0.18

0.25

0.42

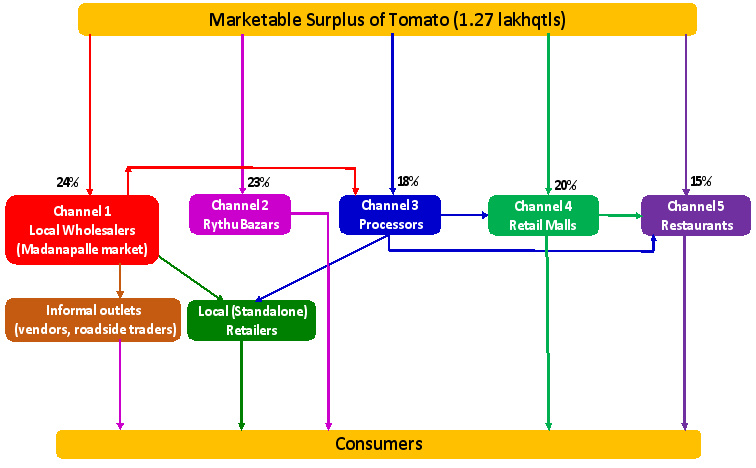
Figure 2. Market channel choices for transacting tomato in Chittoor.
Figure 2 encapsulates the intricate network of market channels facilitating tomato transactions in Ananthapuramu, delineating the allocation of 1.27 lakh quintals of marketable surplus across various intermediaries. Multiple interconnected pathways define the transition of produce from cultivators to end consumers, each exhibiting distinct roles and proportional contributions. Local wholesalers absorb a substantial 24 percent share, serving as pivotal intermediaries by redistributing produce to processors and informal vendors, including roadside traders. Rythu Bazaars account for 23 percent, offering a direct interface between farmers and consumers, thereby fostering accessibility and price efficiency. Processors handle 18 percent of the supply, channelling output towards retail malls and retailers, ensuring further distribution within the market. Retail malls, commanding 20 percent of the total supply, cater to both consumers and restaurants, the latter independently securing 15 percent to maintain a steady influx of high-quality produce. Informal vendors, operating as crucial conduits, enhance consumer accessibility, enabling the last-mile reach of fresh produce. Thus, marketable surplus traverses multiple pathways, illustrating strategic sales optimization by farmers who navigate price differentials, established trade relationships, and shifting demand dynamics. Transactions with processors, retail malls and restaurants reflect efforts to maximize revenue, leveraging price fluctuations and supply chain efficiencies. Procurement by these three agencies directly from producers ensures consistency in quality, volume, and cost-effectiveness. These well-entrenched linkages, reinforced by mutual trust, underpin seamless transactions, timely payments, and an uninterrupted supply chain. Logistical efficiency, storage infrastructure, and processing imperatives significantly shape channel selection, contributing to a flexible and adaptive market framework. The co-existence of formal and informal actors underscores the dynamic nature of tomato marketing, where multiple stakeholders collaboratively optimize distribution while catering to diverse consumer preferences. This inter-connected structure reflects the evolving complexity of market mechanisms, balancing producer interests with consumer demand through strategic trade engagements and well-established supply networks.
4.2. PCA
A comprehensive examination of Appendices 1 and 2 uncovers substantial correlations among selected independent variables, accompanied by elevated Uncentered Variance Inflation Factor (VIF) and Centered VIF values for specific predictors, indicating a pronounced degree of multicollinearity. This statistical challenge necessitated the application of PCA to transform highly collinear variables into a set of orthogonal components while retaining critical informational attributes (Table 3). So, PCA was implemented to generate a factor loading matrix, ensuring that the underlying patterns within the data remain preserved despite the reduction in dimensionality. By leveraging covariance characteristic roots, market channel-wise factors were systematically extracted (Tables 4 to 8), capturing essential structural variations within each distribution channel. This methodological approach enhances interpretability and mitigates distortions arising from multicollinearity, thereby reinforcing the reliability of subsequent econometric modelling and inferential analysis .
Table 3. Channel-wise Number of Significant Components and Variance Explained.

Market channel

No of Components with Eigen value > 1

Cumulative proportion of Variance explained (%)

Local Wholesaler

10

70.66

Rythu Bazar

11

76.39

Processor

10

70.95

Retail mall

10

71.09

Restaurant

10

70.56

Table 3 highlight the number of significant principal components—those with eigenvalues exceeding unity—identified for each market channel, along with the cumulative proportion of variance they account for in the respective datasets. These findings indicate that the number of significant components varies across different market channels, with eigenvalues surpassing the conventional threshold of one. Local wholesalers exhibit ten principal components, cumulatively capturing 70.66 per cent of total variance, thereby suggesting that a substantial portion of data variability is explained by these extracted dimensions . Similarly, the processor channel also registers ten principal components, explaining 70.95 per cent of variance, reinforcing the effectiveness of dimensionality reduction in capturing influential data patterns within this segment. Rythu Bazar, a distinct marketplace characterized by direct producer-to-consumer transactions, demonstrates the presence of eleven principal components, cumulatively explaining 76.39 per cent of total variance. This relatively higher proportion suggests that a broader range of latent factors significantly influences structural variations within this channel, possibly due to greater heterogeneity in operational dynamics, pricing mechanisms, and producer-consumer interactions. Retail malls, integral to modern supply chains, manifest ten principal components, explaining 71.09 per cent of variance. The relatively high explanatory power of extracted components within this channel suggests a structured and streamlined market behaviour, where fewer latent dimensions encapsulate complex interrelationships between economic variables. Restaurants, another key market outlet, exhibit a similar pattern, with ten principal components collectively accounting for 70.56 per cent of variance, indicating the presence of dominant factors influencing procurement strategies, cost structures, and consumer preferences within food service operations. The cumulative variance explained across market channels underscores the effectiveness of PCA in transforming multidimensional datasets into interpretable structures while preserving substantial informational content. By systematically reducing data dimensionality while retaining core informational attributes, the extracted components serve as valuable inputs for further empirical investigation and decision-making frameworks across distinct market structures .
Marketing Channel I (Farmer-to-Local Wholesaler) operates through distinct structural patterns shaping producer-market interactions (Table 4). Factor analysis highlights the influence of farm scale and market transition, strongly correlated with DIST, LHS, and CR, emphasizing spatial and operational dynamics in market linkages. Consumer choice, aligned with CP, reflects buyer preference-driven demand variations. Supply chain mediation, represented by II, ensures seamless procurement logistics, while inventory and quality control, captured by QP and IC, reinforce product standards. Collective action, indicated by FPOM and BP, strengthens producer bargaining power, while market access and negotiation disparities, correlated with ML, influence price-setting power. Climate-smart adaptation, reflected in CRP, highlights resilience strategies against environmental uncertainties. Supply chain stability, shaped by SF and PV, ensures market continuity, whereas market readiness and post-harvest financial efficiency, signified by PPOS and MBLS, reinforce commercialization preparedness and fiscal prudence .
Marketing Channel II (Farmer-to-Rythu Bazar) exhibits structural dimensions centered on farm scale and market supply, with strong correlations to LHS, MBLS, and II, indicating the influence of farm size, marketable surplus, and intermediary mediation (Table 5). Market accessibility and trade efficiency, represented by AMI, INFRA, and RISK, highlight the role of market information, infrastructure constraints, and risk perceptions. Post-harvest losses, shaped by FPOM and CP, emphasize the impact of producer organizations and consumer preferences. Information asymmetry and trade costs, signified by TC, reflect barriers in price transparency and transaction inefficiencies. Sustainable market linkages, structured by PV and CR, underscore resilience amid price volatility. Market dynamics, captured by DI, showcase digital integration's role in improving efficiency, while market reach and inventory costs, linked to DIST and IC, highlight spatial logistics and cost implications. Financial leverage, represented by MF and BP, indicates disparities in access to financing and bargaining power. Storage infrastructure, reflected by SF and CSC, mitigates perishability risks, and trade facilitation, symbolized by ML, strengthens structured market linkages. Revenue generation, signified by PPOS, sustains farmer incomes through prompt sales proceeds .
Table 4. Factor analysis results of variables of Marketing Channel I (Farmer to Local Wholesalers).

Variables

Factors

Farm Scale & Market Transition

Consumer Choice

Supply Chain Mediation

Inventory & Quality Control

Collective Action

Market Access & Negotiations

Climate Smart Adaptation

Supply Chain Stability

Market Readiness

Post-Harvest Financial Efficiency

DIST

0.6514

LHS

0.6502

MBLS

-0.4213

CSC

-0.4661

QP

0.6259

ML

-0.4724

PPOS

0.7165

SF

0.5805

FPOM

-0.6698

CP

-0.6600

PV

-0.5218

IC

0.5453

BP

0.6562

II

0.6440

CRP

0.6919

CR

0.6514

Table 5. Factor analysis results of variables of Marketing Channel II (Farmer to Rythu Bazar).

Variables

Factors

Farm Scale & Market Supply

Market Accessibility & Trade Mediation

Post-Harvest Losses

Information Asymmetry & Trade Costs

Sustainable Market Linkages

Market Dynamics

Market Reach & Inventory Overheads

Financial Leverage

Storage

Trade Facilitation

Revenue

DIST

0.4204

LHS

0.6603

MBLS

0.6634

CSC

0.8076

TC

-0.5305

ML

0.4412

AMI

0.6602

PPOS

0.837

SF

0.8743

FPOM

0.4970

CP

-0.7041

PV

-0.5547

IC

0.7937

RISK

0.8311

INFRA

-0.5106

BP

0.6647

DI

0.5531

MF

-0.5079

II

0.6951

CR

0.4730

Table 6. Factor analysis results of variables of Marketing Channel III (Farmer to Processors).

Variables

Factors

Farm Scale & Market Supply

Eco-Driven Distribution

Information-Driven Bargaining

Cash-Flow Efficiency

FPO-Driven Linkages

Quality

Delivery

Logistics & Warehousing

Risk & Smart Supply Chain

Market Adaptability

DIST

0.5461

LHS

0.6240

MBLS

0.6310

CSC

0.5973

TC

0.4042

QP

0.6418

ML

-0.4834

AMI

0.5869

PPOS

0.5763

SF

0.4426

-0.4309

FPOM

0.6906

DT

0.6492

CP

0.4933

PV

0.7075

IC

0.4997

RISK

0.6654

BP

0.5574

DI

0.4154

CR

0.4759

Table 7. Factor analysis results of variables of Marketing Channel IV (Farmer to Retail malls).

Variables

Factors

Farm Scale & Market Supply

Eco-Driven Inventory Dynamics

Climate Adaptive Cold Chain

Institutional Financial Access

Market Access

Transport Efficiency

Cash Flow Sensitivity

Retail Logistics & Dynamics

Trade Efficiency

Quality Storage & Management

DIST

-0.4766

LHS

0.6229

MBLS

0.6277

CSC

-0.5523

TC

0.5993

QP

0.5251

ML

0.6962

AMI

0.4494

PPOS

0.6938

FPOM

0.5940

DT

-0.4054

CP

0.5909

PV

0.5217

IC

-0.5411

RISK

0.5713

INFRA

0.6769

MF

-0.5875

CRP

0.6488

CR

0.7030

Table 8. Factor analysis results of variables of Marketing Channel V (Farmer to Restaurants).

Variables

Factors

Farm Scale & Market Supply

Eco-Market Trade

Transactions Overhead

Financial & Quality Assurance

Digital Retail Dynamics

Collective Climate Resilience

Transport Efficiency

Logistics Efficiency

Storage Infrastructure

Market Accessibility

DIST

0.7520

LHS

0.6546

MBLS

0.6566

CSC

-0.5737

TC

0.6652

QP

0.4004

PPOS

0.6234

SF

0.6503

FPOM

0.5457

DT

0.7475

CP

-0.4393

IC

0.5051

INFRA

0.7065

BP

0.5115

DI

0.4042

MF

0.5049

CRP

0.6342

CR

0.6864

Marketing Channel III (Farmer-to-Processor) is shaped by farm scale and market supply, with strong associations to LHS, MBLS, and CP, emphasizing farm size, surplus, and consumer-driven production (Table 6). Eco-driven distribution, structured by AMI, BP, and DIST, underscores market accessibility and producer-buyer relationships. Information-driven bargaining, represented by IC, PPOS, and FPOM, highlights trade optimization through price negotiation and producer organizations. Cash-flow efficiency, signified by ML and DT, ensures financial fluidity in farmer-processor linkages. FPO-driven linkages, captured by QP and FPOM, reinforce collective action in market stability. Quality control, shaped by CSC and TC, emphasizes adherence to processing standards, while delivery logistics, represented by SF, addresses storage challenges and perishability concerns. Logistics and warehousing, correlated with PV and CR, optimize procurement and supply chain management. Risk mitigation and smart supply chain adaptation, indicated by RISK, enhance resilience against market uncertainties, while market adaptability, captured by DI, highlights digital integration in responding to demand shifts .
Marketing Channel IV (Farmer-to-Retail Malls) reflects structural patterns where farm scale and market supply, signified by LHS, MBLS, and CP, align farm outputs with retail demand (Table 7). Eco-driven inventory dynamics, structured by CRP and CSC, emphasize climate-adaptive procurement and storage strategies. Cold chain infrastructure resilience, captured by INFRA, minimizes wastage and ensures supply chain efficiency. Institutional financial access, represented by MF and FPOM, facilitates stable trade engagements with retail malls, while market access, shaped by ML, supports direct farmer integration into organized retail chains. Transport efficiency, indicated by DIST and DT, influences supply chain continuity and delivery timelines. Cash flow sensitivity, reflected by PPOS and PV, ensures liquidity and smooth financial management. Retail logistics, captured by CR, coordinates procurement, inventory, and product replenishment, while trade efficiency, indicated by TC, minimizes transaction costs. Quality storage and management, represented by QP and RISK, reinforce product quality and market stability through robust storage solutions and risk mitigation strategies .
Marketing Channel V (Farmer-to-Restaurants) exhibits structural dimensions where farm scale and market supply, strongly associated with LHS and MBLS, sustain stable supply arrangements (Table 8). Eco-market trade, represented by TC, highlights sustainable procurement and environmentally conscious trade practices. Transaction overhead, captured by PPOS and QP, reflects price negotiations, order fulfilment, and quality compliance. Financial and quality assurance, signified by FPOM and CR, ensure trade stability and adherence to quality standards. Digital retail dynamics, structured by MF and DI, enhance transparency, direct transactions, and supply chain efficiency. Collective climate resilience, captured by CRP, mitigates climate-induced disruptions, ensuring consistent produce availability. Transport efficiency, represented by DT, addresses logistical constraints in delivery cycles, while logistics efficiency, indicated by SF and DIST, ensures uninterrupted supply. Storage infrastructure, reflected by INFRA, maintains freshness and minimizes food wastage. Market accessibility, captured by CSC, highlights procurement challenges, regulatory constraints, and urban market penetration strategies in restaurant supply chains .
Thus, the structural components shaping each marketing channel underscore key factors influencing farmer-market linkages, trade efficiency, and market resilience . In the Farmer-to-Local wholesaler channel, farm scale, market transition, and consumer choice play a crucial role, with strong correlations to spatial and operational dynamics (DIST, LHS, CR) and demand variations (CP). Supply chain mediation (II), inventory control (QP, IC), and collective action (FPOM, BP) enhance producer leverage, while market access disparities (ML) and climate adaptation (CRP) shape price-setting power and resilience . The Farmer-to-Rythu Bazar channel emphasizes farm scale and marketable surplus (LHS, MBLS, II), with accessibility (AMI, INFRA) and risk perceptions (RISK) affecting trade efficiency. Post-harvest losses (FPOM, CP), trade costs (TC), and sustainable linkages (PV, CR) highlight challenges in transparent pricing, while digital integration (DI) and financial leverage (MF, BP) support revenue stability. The Farmer-to-Processor channel focuses on structured supply arrangements, emphasizing consumer-driven production (LHS, MBLS, CP), eco-driven distribution (AMI, BP, DIST), and bargaining power (IC, PPOS, FPOM). Quality control (CSC, TC), logistics efficiency (SF, PV, CR), and risk adaptation (RISK) ensure market continuity, while financial flows (ML, DT) sustain cash flow efficiency. The Farmer-to-Retail Malls channel highlights climate-adaptive procurement (CRP, CSC), cold chain resilience (INFRA), and financial access (MF, FPOM) in facilitating structured trade. Market access (ML), transport efficiency (DIST, DT), and liquidity management (PPOS, PV) ensure smooth financial transactions, while storage solutions (QP, RISK) support quality assurance. The Farmer-to-Restaurants channel emphasizes marketable surplus (LHS, MBLS), eco-market trade (TC), and transaction overheads (PPOS, QP), with financial stability (FPOM, CR) and digital platforms (MF, DI) streamlining trade. Climate resilience (CRP), logistics coordination (SF, DIST), and storage infrastructure (INFRA) ensure supply reliability, while accessibility constraints (CSC) impact procurement policies. Comparing these channels, Farmer-to-Local Wholesaler and Farmer-to-Rythu Bazar focus more on direct trade and collective bargaining, while Farmer-to-Processor and Farmer-to-Retail Malls emphasize quality compliance, structured financing, and logistics. Farmer-to-Restaurants, though market-driven, integrates digital efficiency and eco-friendly trade .
4.3. DEA
In the second phase of DEA, efficiency assessment of marketing channels relies on component scores obtained from first phase of PCA as inputs, with NPR serving as the output . However, certain predicted component scores derived through PCA exhibit negative values across selected channels, complicating direct DEA implementation. Since DEA estimation necessitates covariates that maintain both interpretability and non-negativity, a Min-Max normalization approach—specifically, the Shifting by Absolute Minimum method—is employed to address this challenge. This transformation reconfigures component scores within a standardized range, enhancing coherence and analytical stability. By preserving relative variations inherent in PCA-derived scores while eliminating negative values, this approach ensures their compatibility with DEA, thereby facilitating robust efficiency estimation across marketing channels .
Findings from DEA (Table 9) underscore substantial disparities in efficiency across marketing channels, revealing variations in both technical and scale efficiency . Among the evaluated channels, Channel 4 emerges as the most efficient, exhibiting the highest mean Variable Returns to Scale – Technical Efficiency (VRS-TE) score (0.982), which signifies optimal utilization of available resources to generate maximum output. Conversely, Channel 1 records the lowest mean efficiency score (0.918), indicating suboptimal performance in resource allocation and operational execution. Scale efficiency trends align closely with these results, with Channel 4 maintaining superior performance, while Channel 1 demonstrates inefficiencies in scaling operations effectively. Disparities in efficiency levels stem from several underlying structural and operational factors unique to each marketing channel. Channels 1 and 2 exhibit a predominant presence of increasing returns to scale (IRS), suggesting that expanding operational capacity could lead to enhanced efficiency by leveraging economies of scale. This trend suggests that these channels currently operate below their optimal scale and could benefit from further growth to maximize efficiency. In contrast, Channels 3, 4, and 5 display significant instances of decreasing returns to scale (DRS), implying inefficiencies arising from excessive scaling, which may result in diminishing marginal returns due to rising operational complexities, coordination challenges, or resource misallocation. Furthermore, efficiency variations may also be attributed to differences in marketing strategies, infrastructure availability, supply chain integration, and transaction costs. Channels with higher efficiency scores likely benefit from well-structured distribution networks, streamlined logistical frameworks, and cost-effective transaction mechanisms, whereas those with lower efficiency may experience bottlenecks such as fragmented supply chains, inadequate infrastructure, or higher operational expenditures. These distinctions highlight the necessity of customized strategic interventions tailored to each channel’s specific inefficiencies. For channels exhibiting IRS, targeted investments in capacity expansion and technological advancements could enhance efficiency, whereas for those with DRS, refining operational processes, optimizing scale, and minimizing excess capacity could yield better outcomes. By understanding these efficiency patterns, decision-makers can implement precise policy measures and structural reforms to enhance overall marketing channel performance .
Table 9. Scale and Efficiency measures across selected marketing channels.

Efficiency Scores

Channel 1

Channel 2

Channel 3

Channel 4

Channel 5

VRS-TE

Scale

VRS-TE

Scale

VRS-TE

Scale

VRS-TE

Scale

VRS-TE

Scale

1.000

49

26

48

39

48

44

48

45

47

36

0.999 - 0.900

1

14

3

16

3

8

7

11

3

16

0.899 - 0.800

--

9

2

2

4

7

5

3

6

4

0.799 - 0.700

1

2

--

2

2

1

--

1

1

4

0.699 - 0.600

1

4

3

1

3

--

--

--

3

--

0.599 - 0.500

4

3

4

--

--

--

--

--

--

--

0.499 - 0.400

1

2

--

--

--

--

--

--

--

--

0.399 - 0.300

3

--

--

--

--

--

--

--

--

--

Mean

0.918

0.893

0.943

0.973

0.963

0.974

0.982

0.979

0.963

0.967

Constant Returns to Scale (CRS)

26

39

44

45

36

IRS

27

15

5

2

13

DRS

7

6

11

13

11

5. Summary and Conclusions
This study conducted a comparative evaluation of marketing efficiency across five distinct tomato marketing channels—local wholesalers, Rythu Bazars, processors, retail malls, and restaurants—to assess their effectiveness in terms of net price realization for smallholder farmers in Ananthapuramu district, Andhra Pradesh. This research aimed to bridge gap in existing literature to focus on determinants of market channel choices rather than their relative marketing efficiency. A two-stage sampling framework was employed, selecting Ananthapuramu district based on its prominence in tomato cultivation and further narrowing the focus to Kalyanadurgam and Settur mandals. A sample of 300 smallholder tomato farmers (each with landholding ≤2 hectares) was selected, with 60 farmers representing each marketing channel. Both primary and secondary data are employed in this study.
PCA identifies key determinants influencing market efficiency, with the number of significant principal components varying across channels, reflecting distinct structural patterns. Local wholesalers and processors exhibit ten principal components, capturing 70.66 per cent and 70.95 per cent of variance, respectively, indicating substantial data variability. Rythu Bazars, characterized by direct producer-to-consumer transactions, demonstrate eleven components, explaining 76.39 per cent of variance, suggesting greater heterogeneity in pricing mechanisms and operational dynamics. Retail malls and restaurants, with ten principal components each, account for 71.09 per cent and 70.56 per cent of variance, respectively, reflecting structured market behavior and dominant procurement strategies.
Findings from DEA revealed significant efficiency disparities, with Channel 4 (retail malls) emerging as the most efficient (mean VRS-TE score: 0.982), while Channel 1 (local wholesalers) records the lowest efficiency (0.918), highlighting resource misallocation and operational constraints. Scale efficiency trends align closely, with Channels 1 and 2 exhibiting increasing returns to scale (IRS), suggesting efficiency gains through capacity expansion, while Channels 3, 4, and 5 display decreasing returns to scale (DRS), indicating inefficiencies due to excessive scaling and coordination challenges. These findings underscore the need for tailored interventions—capacity expansion and technological investments for IRS channels, and process optimization for DRS channels—to enhance marketing efficiency. The study confirms that marketing efficiency varies significantly across channels, with some offering better price realization and reduced transaction costs. Among the five channels, retail malls and Rythu Bazars exhibited higher efficiency scores, ensuring better price transparency and minimal intermediary costs. Processors and restaurants provided relatively stable pricing, though stringent quality requirements acted as a barrier to farmer participation. Local wholesalers, despite ensuring liquidity, yielded the lowest margins due to intermediary costs and price-setting asymmetries.
So, farmers aiming to maximize profitability should prioritize direct marketing channels such as Rythu Bazars and retail malls, which offer competitive pricing and direct consumer access. Strengthening linkages with processors and restaurants can further enhance market stability, provided farmers meet the necessary quality standards. These findings highlight the need for enhanced infrastructure, digital market integration, and producer cooperatives to improve market access and efficiency. Expanding cold storage facilities, transparent pricing mechanisms, and farmer training programs will further enable smallholder farmers to participate in high-value markets.
While this study provides valuable insights into price realization across different tomato marketing channels, it has certain limitations that warrant further investigation. First, the analysis primarily focuses on efficiency and price realization without considering the impact of seasonality and price volatility, which significantly influence market performance and farmer earnings. Second, the study does not account for farmers’ bargaining power, TCs, and institutional constraints, all of which exert a significant influence on profitability dynamics. Third, the findings are based on data from a specific geographic region (Ananthapuramu district), limiting their generalizability to other markets with different structural and operational characteristics. Additionally, while the study employs PCA and DEA to assess market efficiency, it does not integrate qualitative factors such as farmer perceptions, consumer demand shifts, or policy interventions that might affect market outcomes. Future research could address these gaps by incorporating dynamic pricing models, assessing supply chain resilience, and analyzing the role of digital market platforms in enhancing efficiency. Examining contractual agreements with organized retail players and the impact of sustainability and climate risks on marketing efficiency would further enrich the understanding of market stability and farmer resilience. Ultimately, the study underscores the critical role of marketing efficiency in enhancing farmer incomes and promoting sustainable commercialization, offering a roadmap for policymakers and agribusiness stakeholders to optimize tomato marketing channels.
Abbreviations

APMCs

Agricultural Produce Market Committees

CRS

Constant Returns to Scale

CV

Coefficient of Variation

DEA

Data Envelopment Analysis

DMU

Decision-Making Unit

DRS

Decreasing Returns to Scale

FPOs

Farmer Producer Organizations

IRS

Increasing Returns to Scale

PCA

Principal Component Analysis

PCs

Principal Components

TE

Technical Efficiency

VIF

Variance Inflation Factor

VRS-TE

Variable Returns to Scale – Technical Efficiency

Acknowledgments
The authors are grateful to data enumerators who has contributed greatly to the successful completion of the study.
Author Contributions
Kotamraju Nirmal Ravi Kumar is the sole author. The author read and approved the final manuscript.
Conflicts of Interest
No potential conflict of interest was reported by the author(s).
Funding
This study was wholly funded by the author of this research
Public Interest Statement
This study evaluates the efficiency of different tomato marketing channels in Ananthapuramu district, Andhra Pradesh, focusing on their impact on smallholder farmers' earnings. It highlights how direct-to-consumer platforms like Rythu Bazars and retail malls offer better price realization and transparency compared to traditional wholesale markets. Using advanced analytical methods, the research identifies efficiency gaps and areas for improvement in marketing structures. Findings suggest that farmers can boost profitability by engaging with high-efficiency channels while strengthening ties with processors and restaurants for price stability. The study also emphasizes the need for better infrastructure, digital market integration, and cold storage facilities to minimize losses and improve access. These findings provide valuable guidance for improving farmer incomes and optimizing tomato market operations. Policymakers and agribusiness stakeholders can use these insights to design more efficient and farmer-friendly market systems. Future research could explore supply chain resilience and innovative pricing strategies to strengthen agricultural marketing.
Data Availability Statement
The data for the study is available upon request
Appendix
Appendix I: Uncentered VIF

Channel 1: Local Wholesalers

Channel 2: Rythu Bazars

Channel 3: Processors

Channel 4: Retail malls

Channel 5: Restaurants

Variable

VIF

1/VIF

Variable

VIF

1/VIF

Variable

VIF

1/VIF

Variable

VIF

1/VIF

Variable

VIF

1/VIF

MBLS

1192.52

0.0008

LHS

3660.37

0.0003

DIST

547.38

0.0018

DIST

559.69

0.0018

LHS

452.88

0.0022

LHS

1167.15

0.0009

MBLS

3596.52

0.0003

MBLS

426.19

0.0023

LHS

369.40

0.0027

MBLS

442.17

0.0023

DIST

299.42

0.0033

DIST

561.34

0.0018

LHS

417.36

0.0024

MBLS

364.60

0.0027

DIST

370.04

0.0027

II

40.75

0.0245

PV

85.70

0.0117

TC

53.14

0.0188

TC

114.37

0.0087

CRP

77.58

0.0129

PV

29.09

0.0344

QP

39.58

0.0253

AMI

52.84

0.0189

CRP

56.99

0.0175

CP

39.70

0.0252

TC

20.96

0.0477

TC

32.47

0.0308

PPSP

49.85

0.0201

CR

55.30

0.0181

IC

35.06

0.0285

CRP

12.67

0.0789

CP

29.71

0.0337

CP

43.01

0.0232

SF

51.38

0.0195

BP

28.72

0.0348

CP

12.14

0.0824

DT

29.46

0.0339

QP

41.61

0.0240

PPSP

45.22

0.0221

QP

28.61

0.0350

FPOM

10.73

0.0932

AMI

25.87

0.0386

FPOM

41.11

0.0243

QP

42.30

0.0236

RI

27.93

0.0358

DT

10.06

0.0994

RI

21.11

0.0474

ML

40.28

0.0248

ML

42.04

0.0238

DI

27.09

0.0369

PPSP

9.48

0.1055

PPSP

20.50

0.0488

SF

39.75

0.0252

FPOM

41.60

0.0240

FPOM

26.79

0.0373

IC

8.88

0.1126

QL

19.76

0.0506

DT

38.80

0.0258

DT

40.95

0.0244

SF

23.83

0.0420

QL

8.42

0.1188

ML

18.83

0.0531

CRP

34.44

0.0290

CP

35.80

0.0279

QL

23.15

0.0432

QP

8.40

0.1190

CRP

16.33

0.0612

BP

27.76

0.0360

AMI

31.73

0.0315

AMI

21.81

0.0458

ML

8.32

0.1201

MF

16.24

0.0616

IC

24.72

0.0405

RI

24.10

0.0415

PPSP

21.11

0.0474

MF

8.14

0.1229

CSC

15.50

0.0645

DI

23.71

0.0422

PV

23.38

0.0428

TC

20.70

0.0483

DI

8.13

0.1230

DI

14.48

0.0691

II

22.27

0.0449

BP

23.33

0.0429

CSC

20.41

0.0490

AMI

7.86

0.1272

IC

12.28

0.0814

RI

21.28

0.0470

IC

23.00

0.0435

PV

18.59

0.0538

CR

7.77

0.1287

FPOM

12.08

0.0828

PV

19.16

0.0522

DI

22.73

0.0440

ML

18.27

0.0547

BP

7.34

0.1362

BP

10.67

0.0938

MF

15.48

0.0646

QL

18.32

0.0546

DT

12.06

0.0829

CSC

7.22

0.1386

II

10.49

0.0953

QL

13.22

0.0756

CSC

10.67

0.0938

MF

10.91

0.0917

RI

5.85

0.1709

CR

10.10

0.0990

CSC

12.44

0.0804

MF

8.93

0.1120

II

10.26

0.0975

sf

4.99

0.2003

SF

8.29

0.1206

CR

10.65

0.0939

II

8.16

0.1225

CR

9.90

0.1010

Mean VIF

125.93

Mean VIF

359.46

Mean VIF

87.67

Mean VIF

87.56

Mean VIF

76.85

Appendix II: Centered VIF

Channel 1: Local Wholesalers

Channel 2: Rythu Bazars

Channel 3: Processors

Channel 4: Retail malls

Channel 5: Restaurants

Variable

VIF

1/VIF

Variable

VIF

1/VIF

Variable

VIF

1/VIF

Variable

VIF

1/VIF

Variable

VIF

1/VIF

MBLS

290.69

0.0034

LHS

655.77

0.0015

MBLS

82.84

0.0121

MBLS

75.14

0.0133

LHS

90.72

0.0110

LHS

286.97

0.0035

MBLS

652.67

0.0015

LHS

77.77

0.0129

LHS

73.19

0.0137

MBLS

89.58

0.0112

PV

1.85

0.5405

CRP

2.24

0.4464

AMI

2.03

0.4926

SF

1.82

0.5495

IC

1.99

0.5025

CP

1.85

0.5405

TC

2.02

0.4950

II

1.84

0.5435

PV

1.8

0.5556

QL

1.89

0.5291

CSC

1.76

0.5682

RI

1.87

0.5348

BP

1.84

0.5435

CSC

1.71

0.5848

BP

1.81

0.5525

II

1.73

0.5780

DT

1.83

0.5464

PPSP

1.79

0.5587

DT

1.67

0.5988

FPOM

1.72

0.5814

CRP

1.73

0.5780

BP

1.83

0.5464

SF

1.78

0.5618

ML

1.67

0.5988

TC

1.68

0.5952

FPOM

1.66

0.6024

PV

1.79

0.5587

QP

1.75

0.5714

DIST

1.67

0.5988

RI

1.67

0.5988

CR

1.66

0.6024

II

1.75

0.5714

FPOM

1.68

0.5952

CR

1.65

0.6061

DT

1.63

0.6135

DT

1.61

0.6211

FPOM

1.74

0.5747

CRP

1.63

0.6135

CP

1.63

0.6135

SF

1.61

0.6211

IC

1.59

0.6289

CP

1.7

0.5882

DI

1.63

0.6135

CRP

1.55

0.6452

CP

1.6

0.6250

PPSP

1.56

0.6410

AMI

1.66

0.6024

DIST

1.63

0.6135

TC

1.55

0.6452

MF

1.57

0.6369

QL

1.56

0.6410

QP

1.57

0.6369

IC

1.62

0.6173

FPOM

1.54

0.6494

QP

1.57

0.6369

DIST

1.56

0.6410

QL

1.56

0.6410

CSC

1.57

0.6369

IC

1.53

0.6536

II

1.56

0.6410

DI

1.56

0.6410

CR

1.53

0.6536

MF

1.49

0.6711

PPSP

1.5

0.6667

PPSP

1.5

0.6667

ML

1.54

0.6494

CSC

1.53

0.6536

TC

1.46

0.6849

II

1.44

0.6944

AMI

1.48

0.6757

TC

1.43

0.6993

IC

1.53

0.6536

CR

1.45

0.6897

DI

1.43

0.6993

DI

1.47

0.6803

AMI

1.42

0.7042

DIST

1.53

0.6536

ML

1.45

0.6897

BP

1.42

0.7042

CR

1.45

0.6897

MF

1.4

0.7143

PPSP

1.49

0.6711

RI

1.45

0.6897

QL

1.38

0.7246

PV

1.4

0.7143

BP

1.38

0.7246

MF

1.45

0.6897

DT

1.43

0.6993

RI

1.37

0.7299

CRP

1.36

0.7353

QP

1.31

0.7634

DI

1.36

0.7353

QL

1.36

0.7353

MF

1.36

0.7353

DIST

1.36

0.7353

RI

1.31

0.7634

ML

1.35

0.7407

CP

1.33

0.7519

AMI

1.32

0.7576

CSC

1.34

0.7463

SF

1.12

0.8929

SF

1.3

0.7692

PV

1.28

0.7813

QP

1.28

0.7813

ML

1.14

0.8772

Mean VIF

26.53

Mean VIF

58.39

Mean VIF

8.44

Mean VIF

7.85

Mean VIF

9.27

References
[1] FAO. (2023). FAOSTAT Statistical Database. Food and Agriculture Organization of the United Nations. Retrieved from
[2] Ministry of Agriculture and Farmers’ Welfare. (2024). Agricultural Statistics at a Glance 2024. Government of India.
[3] Arias, P., Hallam, D., Krivonos, E., and Morrison, J. (2013). Smallholder Integration in Changing Food Markets. Rome: Food and Agriculture Organization of the United Nations.
[4] Barrett, C. B. (2008). Smallholder Market Participation: Concepts and Evidence from Eastern and Southern Africa. Food Policy, 33(4): 299–317.
[5] Sisay, M. A. (2018). Assessment of Challenges in Export Marketing: The Case of Ethiopian Vegetable and Fruit Commercial Growers. IBusiness, 10(1): 1–20,
[6] Abera, S. (2016). Econometric Analysis of Factors Affecting Haricot Bean Market Outlet Choices in Misrak Badawacho District, Ethiopia. International Journal of Research Studies in Agricultural Sciences, 2(9),
[7] Shubha, M., Girish, M., Girish, M. R., and Manish, K. L. (2024). Evaluating the Efficiency of Marketing Channels of Farm Enterprises: A Study in Kolar District. International Journal of Agriculture Extension and Social Development, 7(8): 596–603,
[8] Ghosh, M. (2024). Institutional Reforms and Spatial Efficiency in Agricultural Supply Chains in India. Journal of Asian and African Studies,
[9] Chowdary, V. R., Nedumaran, G., and Barwal, S. (2023). A Comparative Analysis of Marketing Efficiency of Vegetables in Organized Collection Centres and Traditional Channels in Ranga Reddy District of Telangana. Biological Forum – An International Journal, 15(2): 46–51.
[10] Villacis, A. H., Kopp, T., and Mishra, A. K. (2024). Agricultural Marketing Channels and Market Prices: Evidence from High-Value Crop Producers in India. Economic Analysis and Policy, 81: 1308–1321,
[11] Thakur, P., Mehta, P., Devi, C., Sharma, P., Singh, K. K., Yadav, S., Lal, P., Raghav, Y. S., Kapoor, P., and Mishra, P. (2023). Marketing Performance and Factors Influencing Farmers’ Choice for Agricultural Output Marketing Channels: The Case of Garden Pea (Pisum sativum) in India. Frontiers in Sustainable Food Systems, 7: 1270121,
[12] Abad, M., Kumar, R., and Sharma, P. (2023). An Integrative Framework for Assessing Marketing Efficiency in Agricultural Supply Chains: Evidence from Delhi’s Agricultural Markets. Journal of Agricultural Economics and Policy, 15(2): 120–138.
[13] Zhai, T., Liu, J., and Wang, D. (2023). Optimization Path of Agricultural Products Marketing Channel Based on Innovative Industrial Chain. Economic Change and Restructuring, 56: 3949–3977,
[14] Möllers, J., Fritzsch, J., and Buchenrieder, G. (2022). Analyzing Distribution Channels and Market Constraints for Small Farms in Eastern Europe: Evidence from Moldova, Romania, and Serbia. Journal of Agricultural Economics and Development, 15(3): 210–228.
[15] Enthoven, M., and Van den Broeck, G. (2024). The Evolution of Agricultural Distribution Channels in Europe: Assessing the Shift Toward Direct Sales Models. European Journal of Agricultural Economics, 29(1): 45–63.
[16] Fafchamps, M., and Aker, J. C. (2015). How Digital Technologies Are Transforming Agricultural Markets: Evidence from West Africa and India. World Development, 67: 28–42.
[17] Directorate of Economics and Statistics. (2024). Season and Crop Report – 2024. Government of Andhra Pradesh.
[18] Yamane, T. (1967). Elementary Sampling Theory. Englewood Cliffs: Prentice-Hall, Inc.
[19] Mgale, Y. J., and Yunxian, Y. (2020). Marketing Efficiency and Determinants of Marketing Channel Choice by Rice Farmers in Rural Tanzania: Evidence from Mbeya Region. Australian Journal of Agricultural and Resource Economics, 64(4): 1239–1259,
[20] Blandon, J., Henson, S., and Islam, T. (2010). The Importance of Assessing Marketing Preferences of Small-Scale Farmers: A Latent Segment Approach. European Journal of Development Research, 22: 494–509.
[21] Mmbando, F. E., Wale, E. Z., and Baiyegunhi, L. J. S. (2015). Determinants of Smallholder Farmers’ Participation in Maize and Pigeonpea Markets in Tanzania. Agrekon, 54(1): 96–119,
[22] Adler, N., and Golany, B. (2002). Including Principal Component Weights to Improve Discrimination in Data Envelopment Analysis. Journal of Operations Research Society of Japan, 46: 66–73.
[23] Pedersen, S. G., Zachariassen, F., and Arlbjorn, S. J. (2012). Centralization vs. De-Centralization of Warehousing: A Small and Medium-Sized Enterprise Perspective. Journal of Small Business and Enterprise Development, 19(2): 352–369,
[24] Sharma, S. (1996). Applied Multivariate Techniques. New York: John Wiley & Sons, Inc.
[25] Adler, N., and Yazhemsky, E. (2010). Improving Discrimination in Data Envelopment Analysis: PCA–DEA or Variable Reduction. European Journal of Operational Research, 202(1): 273–284,
[26] Andrejić, M., Bojović, N., and Kilibarda, M. (2013). Benchmarking Distribution Centers Using Principal Component Analysis and Data Envelopment Analysis: A Case Study of Serbia. Expert Systems with Applications, 40(10): 3926–3933,
[27] Tadie, M. A., Taye, M. M., and Abebe, B. D. (2019). Determinants of Market Outlet Choices by Smallholder Teff Farmers in Dera District, South Gondar Zone, Amhara Region, Ethiopia: A Multivariate Probit Approach. Journal of Economic Structures, 8: 39,
[28] Mauki, J., Jeckoniah, N., and Massawe, S. (2023). Determinants of Smallholder Rice Farmers’ Market Outlet Selection in Mbarali and Mvomero Districts, Tanzania. Tanzania Journal of Agricultural Sciences, 22(2, Special Issue): 169–179.
[29] Milan, A., and Kilibarda, M. (2015). Distribution Channels Selection Using PCA–DEA Approach. International Journal for Traffic and Transport Engineering, 5(1): 74–81,
[30] Thomas Kwadwo Ntowa, Camillus Abawiera Wongnaaa, Ralph Nyadu-Addob, Monica Addisonc, Dadson Awunyo-Vitora, and Emmanuel Abokyi. (2023). Effects of Entrepreneurial Behaviour on Market Outlets Choice: Evidence from Rice Producers in Ashanti Region, Ghana. Sustainable Technology and Entrepreneurship, 2: 100037,
[31] Zhu, M., Shen, C., Tian, Y., Wu, J., and Mu, Y. (2022). Factors Affecting Smallholder Farmers’ Marketing Channel Choice in China with Multivariate Logit Model. Agriculture, 12: 1441,
[32] Oliyad, S., and Megersa, A. (2022). Determinants of Groundnut Producers’ Market Channel Choice in Western Oromia Region, Ethiopia. Journal of Agriculture and Food Research, 7: 100277,
[33] Mary, S. M., and Nirmal, R. K. K. (2024). Marketing Channel Choice of Vegetable Farmers in Guntur District of Andhra Pradesh. International Journal of Agriculture Extension and Social Development, 7(5): 168–175,
[34] Pingali, P., Aiyar, A., Abraham, M., and Rahman, A. (2019). Linking Farms to Markets: Reducing Transaction Costs and Enhancing Bargaining Power. In Transforming Food Systems for a Rising India, Palgrave Studies in Agricultural Economics and Food Policy. Palgrave Macmillan, Cham,
[35] Yohana James Mgale and Yan Yunxian. (2020). Marketing Efficiency and Determinants of Marketing Channel Choice by Rice Farmers in Rural Tanzania: Evidence from Mbeya Region. Australian Journal of Agricultural and Resource Economics, 64: 1239–1259,
[36] Syahrul Ganda Sukmaya and Ulpah Jakiyah. (2021). Marketing Efficiency and Marketing Channel Choice Assessment of Mango Fruit. E3S Web of Conferences, 232: 02014,
[37] Benmehaia, A. M., Samoggia, A., Benharrat, O., Benziouche, S. E., and Ayfantopoulou, G. (2024). Fairness and Contractual Performance in Vertical Linkages Within an Uncertain Environment: A Case of a Tomato Value Chain. Foods, 13: 3819,
[38] Anika Trebbin. (2014). Linking Small Farmers to Modern Retail Through Producer Organizations – Experiences with Producer Companies in India. Food Policy, 45: 35–44,
[39] Hernández, R., Reardon, T., Natawidjaja, R., and Shetty, S. (2015). Tomato Farmers and Modernising Value Chains in Indonesia. Bulletin of Indonesian Economic Studies, 51(3): 425–444,
[40] Gizachew Wosene and Wubalem Gobie. (2022). Value Chain Analysis of Tomato: The Case of Bure, Jabitehinan and North Mecha Districts of Amhara Regional State, Ethiopia. Journal of Agriculture and Food Research, 7: 100272,
[41] Gulati, A., Wardhan, H., and Sharma, P. (2022). Tomato, Onion and Potato (TOP) Value Chains. In Gulati, A., Ganguly, K., and Wardhan, H. (eds.), Agricultural Value Chains in India. India Studies in Business and Economics. Springer, Singapore,
[42] Sharma, D., Alam, M. J., Begum, I. A., Ding, S., and McKenzie, A. M. (2023). A Value Chain Analysis of Cauliflower and Tomato in Bangladesh. Sustainability, 15: 11395,
[43] Dessie, A. B., Abate, T. M., and Mekie, T. M. (2018). Factors Affecting Market Outlet Choice of Wheat Producers in North Gondar Zone, Ethiopia. Agriculture & Food Security, 7: 91,
[44] Taye Melese, Degye Goshu, and Assefa Tilahun. (2018). Determinants of Outlet Choices by Smallholder Onion Farmers in Fogera District Amhara Region, Northwestern Ethiopia. Journal of Horticulture and Forestry, 10(3): 27–35,
[45] Nelson Mango, Mark Lundy, Clifton Makate, Matthias Jager, and Nicola Francesconi. (2018). Determinants of Market Participation and Marketing Channels in Smallholder Groundnut Farming: A Case of Mudzi District, Zimbabwe. African Journal of Science, Technology, Innovation and Development, 10(3),
[46] Fernie, J., and Sparks, L. (2009). Logistics and Retail Management: Emerging Issues and New Challenges in the Retail Supply Chain. Philadelphia: Kogan Page Limited.
[47] Rushton, A., Croucher, P., and Baker, P. (2006). The Handbook of Logistics and Distribution Management. 3rd Edition. London and Philadelphia: Kogan Page.
[48] Wanke, P., and Zinn, W. (2004). Strategic Logistics Decision Making. International Journal of Physical Distribution & Logistics Management, 34(6): 466–478,
[49] Laurens, Cherchye, Bram De Rock, Bart Dierynck, Pieter Jan Kerstens, and Filip Roodhooft. “A DEA-Based Approach to Customer Value Analysis.” European Journal of Operational Research 308 (No. 3 2023): 1319–1331.
[50] Panda, R. K., and Sreekumar. (2012). Marketing Channel Choice and Marketing Efficiency Assessment in Agribusiness. Journal of International Food & Agribusiness Marketing, 24(3): 213–230,
Cite This Article
  • APA Style

    Kumar, K. N. R. (2025). Assessing Tomato Market Outlets Efficiency in Andhra Pradesh, India - Evidence from PCA-DEA Analysis. International Journal of Agricultural Economics, 10(6), 343-364. https://doi.org/10.11648/j.ijae.20251006.12

    Copy | Download

    ACS Style

    Kumar, K. N. R. Assessing Tomato Market Outlets Efficiency in Andhra Pradesh, India - Evidence from PCA-DEA Analysis. Int. J. Agric. Econ. 2025, 10(6), 343-364. doi: 10.11648/j.ijae.20251006.12

    Copy | Download

    AMA Style

    Kumar KNR. Assessing Tomato Market Outlets Efficiency in Andhra Pradesh, India - Evidence from PCA-DEA Analysis. Int J Agric Econ. 2025;10(6):343-364. doi: 10.11648/j.ijae.20251006.12

    Copy | Download

  • @article{10.11648/j.ijae.20251006.12,
      author = {Kotamraju Nirmal Ravi Kumar},
      title = {Assessing Tomato Market Outlets Efficiency in Andhra Pradesh, India - Evidence from PCA-DEA Analysis
    },
      journal = {International Journal of Agricultural Economics},
      volume = {10},
      number = {6},
      pages = {343-364},
      doi = {10.11648/j.ijae.20251006.12},
      url = {https://doi.org/10.11648/j.ijae.20251006.12},
      eprint = {https://article.sciencepublishinggroup.com/pdf/10.11648.j.ijae.20251006.12},
      abstract = {The study aims to evaluate and compare the marketing efficiency of five tomato marketing channels—local wholesalers, Rythu Bazars, processors, retail malls, and restaurants—in terms of net price realization for smallholder farmers in Andhra Pradesh. A two-stage sampling framework was employed, selecting Ananthapuramu district due to its prominence in tomato cultivation and further narrowing the focus to Kalyanadurgam and Settur mandals. A total of 300 smallholder tomato farmers (each with landholding ≤2 hectares) were selected, with 60 farmers representing each marketing channel. Data are collected through structured surveys and official secondary sources. Principal Component Analysis findings reveal distinct structural patterns across channels, with the number of significant principal components varying accordingly. Local wholesalers and processors exhibit ten principal components, capturing 70.66% and 70.95% of variance, respectively, indicating structured market behaviour. Rythu Bazars, characterized by direct producer-to-consumer transactions, demonstrate eleven principal components explaining 76.39% of variance, suggesting greater heterogeneity in pricing mechanisms and operational dynamics. Retail malls and restaurants, with ten principal components each, account for 71.09% and 70.56% of variance, respectively, reflecting structured market behaviour and dominant procurement strategies. Findings from Data Envelopment Analysis revealed significant efficiency disparities among the five marketing channels. Retail malls (Channel 4) emerge as the most efficient channel, with a mean Variable Returns to Scale Technical Efficiency score of 0.982, while local wholesalers (Channel 1) register the lowest efficiency (0.918) due to resource misallocation and intermediary costs. Scale efficiency analysis indicates that Channels 1 and 2 (local wholesalers and Rythu Bazars) exhibit increasing returns to scale, suggesting potential efficiency gains through capacity expansion. Overall, retail malls and Rythu Bazars demonstrate higher efficiency scores, ensuring better price transparency and reduced intermediary costs. The study underscores the need for enhanced infrastructure, digital market integration, producer cooperatives, and cold storage facilities to improve market access and efficiency.
    },
     year = {2025}
    }
    

    Copy | Download

  • TY  - JOUR
    T1  - Assessing Tomato Market Outlets Efficiency in Andhra Pradesh, India - Evidence from PCA-DEA Analysis
    
    AU  - Kotamraju Nirmal Ravi Kumar
    Y1  - 2025/10/31
    PY  - 2025
    N1  - https://doi.org/10.11648/j.ijae.20251006.12
    DO  - 10.11648/j.ijae.20251006.12
    T2  - International Journal of Agricultural Economics
    JF  - International Journal of Agricultural Economics
    JO  - International Journal of Agricultural Economics
    SP  - 343
    EP  - 364
    PB  - Science Publishing Group
    SN  - 2575-3843
    UR  - https://doi.org/10.11648/j.ijae.20251006.12
    AB  - The study aims to evaluate and compare the marketing efficiency of five tomato marketing channels—local wholesalers, Rythu Bazars, processors, retail malls, and restaurants—in terms of net price realization for smallholder farmers in Andhra Pradesh. A two-stage sampling framework was employed, selecting Ananthapuramu district due to its prominence in tomato cultivation and further narrowing the focus to Kalyanadurgam and Settur mandals. A total of 300 smallholder tomato farmers (each with landholding ≤2 hectares) were selected, with 60 farmers representing each marketing channel. Data are collected through structured surveys and official secondary sources. Principal Component Analysis findings reveal distinct structural patterns across channels, with the number of significant principal components varying accordingly. Local wholesalers and processors exhibit ten principal components, capturing 70.66% and 70.95% of variance, respectively, indicating structured market behaviour. Rythu Bazars, characterized by direct producer-to-consumer transactions, demonstrate eleven principal components explaining 76.39% of variance, suggesting greater heterogeneity in pricing mechanisms and operational dynamics. Retail malls and restaurants, with ten principal components each, account for 71.09% and 70.56% of variance, respectively, reflecting structured market behaviour and dominant procurement strategies. Findings from Data Envelopment Analysis revealed significant efficiency disparities among the five marketing channels. Retail malls (Channel 4) emerge as the most efficient channel, with a mean Variable Returns to Scale Technical Efficiency score of 0.982, while local wholesalers (Channel 1) register the lowest efficiency (0.918) due to resource misallocation and intermediary costs. Scale efficiency analysis indicates that Channels 1 and 2 (local wholesalers and Rythu Bazars) exhibit increasing returns to scale, suggesting potential efficiency gains through capacity expansion. Overall, retail malls and Rythu Bazars demonstrate higher efficiency scores, ensuring better price transparency and reduced intermediary costs. The study underscores the need for enhanced infrastructure, digital market integration, producer cooperatives, and cold storage facilities to improve market access and efficiency.
    
    VL  - 10
    IS  - 6
    ER  - 

    Copy | Download

Author Information