Abstract
Financial performance plays a central and decisive role in the survival, development, and competitiveness of a business. Factors affecting financial performance can be divided into internal and external groups. This article examines how internal factors affect business performance, based on an empirical study of a non-state-owned enterprise in Hanoi, Vietnam. The article was conducted to study the factors of enterprises affecting the performance of non-state enterprises in Hanoi, Vietnam. The article was conducted in the period from 2019 to 2023 using the quantile regression method according to the linear regression model. The research results on the model for ROE, ROA show that the factors of financial leverage, asset turnover, and net profit margin have a positive impact on the performance of non-state enterprises in Hanoi, Vietnam. Factors such as number of years of operation, enterprise size, growth rate, current ratio, have no statistical evidence of impact on the performance of non-stated enterprises in Hanoi, Vietnam in all quantiles. Therefore, to improve financial performance, the management board needs to accelerate asset turnover and make rational use of business leverage – these are the driving forces behind improved financial performance. The number of years in operation or the size of the enterprise are not indicators for investors about whether an enterprise will be successful.
Keywords
Internal Factors, Non-State Enterprises, Performance, Vietnam
1. Introduction
Many domestic and foreign studies on non-state enterprises in Vietnam show that the contribution of these economic sectors to the current economy is very large. Non-state enterprises contribute to increasing the efficiency and competitiveness of the economy. With many enterprises operating in the same industry, enterprises are forced to accept competition to survive and develop. Many non-state enterprises act as satellites for large state corporations, promoting the process of specialization and division of labor in production. However, there are also non-state enterprises that operate more effectively than large state economic corporations in specific fields and industries. However, there are still many challenges for this economic sector to develop effectively, integrate more deeply and successfully integrate into the digital economy
.
For Hanoi, issues related to development potential, development status, and development orientations for the non-state economic sector have not been studied much. According to a report by the Hanoi Department of Planning and Investment, non-state enterprises in the capital are still facing many difficulties in terms of capital, production and business premises, limited management skills, slow innovation in production technology, etc. This shows the need to study the current business performance of non-state enterprises in Hanoi. In addition, identifying development trends and factors affecting the development trends of the non-state economic sector in the coming time will contribute to finding policies and solutions to promote the development of non-state enterprises in Hanoi in the coming time.
In
Table 1 Number of acting enterprises as of annual 31 December by type of enterprise 2019-2023, it reveals that The majority of enterprises registered to operate in Hanoi are non-state enterprises. As of 31 December, 2023, the number of actual enterprises which gained revenue was 150,509 enterprises, increasing by 0.8% compared to that in 2022. Of which, the state-owned sector possessed 355 enterprises, accounting for 0.2%, and dropped by 11%; the non-state sector reached 146,295 enterises, accounting for 97.2%, and grew by 1%; the FDI sector had 3,859 enterprises, making up 2.6%, and dropped by 5%.
Table 1. Number of enterprises classified by type in Hanoi City Period 2019-2023.
Year | Stated owner enterprise | Non-state enterprise | Foreign investment enterprise | Total enterprises |
Number | Percentage | Number | Percentage | Number | Percentage |
2019 | 435 | 0.3 | 126 157 | 97.4 | 2 969 | 2.3 | 129 561 |
2020 | 418 | 0.3 | 137 265 | 97.1 | 3 756 | 2.6 | 141 439 |
2021 | 395 | 0.3 | 140 158 | 96.9 | 4 139 | 2.8 | 144 692 |
2022 | 399 | 0.3 | 144 821 | 97 | 4 063 | 2.7 | 149 283 |
2023 | 355 | 0.2 | 146 295 | 97.2 | 3 859 | 2.6 | 150 509 |
Source: Hanoi Statistical Yearbook 2023
In
Table 1 State-owned enterprises sector includes following types of enterprises: Enterprises with 100% of state capital; Limited liability companies and joint stock companies where the State holds more than 50% of charter capital.
Non-State enterprises sector includes domestic capital enterprises. whose capital is under private ownership of one person or group or where the State holds 50% and less than of their charter capital. There are following types of non-state enterprises: Private enterprises; Partnership companies; Private limited liability companies; Limited liability companies with 50% and less than of charter capital shared by the State; Joint-stock companies without State capital; Joint-stock companies with 50% and less than of charter capital shared by the State.
Foreign direct investment sector includes enterprises with capital directly invested by foreigners, irrespective of the proportion of foreign capital. This sector comprises following types of enterprises: 100% foreign invested enterprises; State enterprises joint venture with foreign parties; Joint ventures between foreign parties and other domestic partners.
In
Table 2 Annual average capital of enterprises by type of enterprises 2019-2023 in billion Vietnamese Dong, it reveals that the majority of capital of enterprises registered to operate in Hanoi are non-state enterprises.
Table 2 shows that up to 76% of annual average capital of enterprises operating in Hanoi city are non-state enterprises, more than 13% are foreign-invested enterprises, and the remaining less than 19% are state-owned enterprises
.
Table 2. Annual average capital of enterprises by type of enterprises 2019-2023.Unit: billion Vietnamese Dong.
Year | Stated owner enterprise | Non-state enterprise | Foreign investment enterprise | Total |
Value | % | Value | % | Value | % |
2019 | 1 227 650 | 19.4 | 4 263 928 | 67.3 | 840 948 | 13.3 | 6 332 526 |
2020 | 1 158 239 | 15.9 | 4 908 706 | 67.2 | 1 232 391 | 16.9 | 7 299 336 |
2021 | 1 215 389 | 15.4 | 5 409 571 | 68.5 | 1 273 064 | 16.1 | 7 898 024 |
2022 | 525 810 | 6.8 | 5 922 084 | 76 | 1 340 040 | 17.2 | 7 787 934 |
2023 | 1 232 637 | 13.2 | 6 826 280 | 73.1 | 1 279 890 | 13.7 | 9 338 907 |
Source: Hanoi Statistical Yearbook 2023
In 2023, the average business capital of the enterprises gained 933.9 trillion VND, increasing by 19.9% compared to that in 2022. Of which, the state-owned enterprises recorded 1,233 trillion VND, increasing by 134.4%: the non-state enterprises reached 6,826 trillion VND. increasing by 15.3%; the FDI enterprises recorded 1,280 trillion VND, a rise of 4.5%
.
The above data shows the important role of non-state enterprises in the socio-economic life of Hanoi. Therefore, it is necessary to study the business performance of non-state enterprises in Hanoi and the influencing factors to have appropriate policies. The research questions are:
1) What is the current status of business performance of non-state enterprises in Hanoi in recent times?
2) What internal factors affect the business performance of non-state enterprises in Hanoi?
3) What solutions are there to develop non-state enterprises in Hanoi in the coming time?
The general objective of this article is to analyze the internal factors affecting the business performance of non-state enterprises. The specific objectives include:
1) Assess the current status of business performance of non-state enterprises in Hanoi.
2) Identify internal factors affecting the business performance of the non-state economic sector in Hanoi.
3) Propose solutions and policies to support the development of non-state enterprises in Hanoi.
The article is designed into 6 parts as follows: Following the introduction, Section 2 describes the literature review. Sections 3 reviews the hypotheses, research model and the data collection. Section 4 presents empirical results and discussion. Finally, Section 5 provides some policy implications and concluding remarks.
2. Literature Review
The issue of studying factors affecting the performance of enterprises is not a new topic, but each country and each territory always has its own characteristics, making the research results have practical value. In the world, there have been many studies posing similar issues in other territories or countries and achieving meaningful analytical results.
Kripa and Ajasllari analyzed the impact of growth rate, liabilities, liquidity, fixed assets, capital size and company size on the profitability of companies in the period 2008-2013
| [19] | Kripa, D., & Ajasllari, D. (2016). Factors affecting the profitability of insurance companies in Albania. European Journal of Multidisciplinary Studies, 1(1), 352-360.
https://doi.org/10.26417/ejms.v1i1.p352-360 |
[19]
. The results of data processing showed that factors such as growth rate, liabilities, liquidity and fixed assets are the main factors affecting the profitability of the company. In which, growth rate has a positive correlation with profitability, while liabilities, liquidity and fixed assets have a negative correlation. Company size has a positive linear correlation with the profitability of companies.
Rashid and Kemal conducted a study on the impact of internal and external factors on the profitability of insurance companies using three indicators: total profitability (ROA), insurance profitability (UP), and investment income (INI)
| [24] | Rashid, A., & Kemal, M. U. (2018). Impact of internal (micro) and external (macro) factors on profitability of insurance companies. Journal of Economic Policy Researches, 5(1), 35-57. |
[24]
. The internal factors in the study include gross written premium, claims, size, leverage, and administrative expenses, while the external factors include interest rates and GDP. Gross written premium was found to have a significant impact on all three profitability indicators, while claims had no significant impact on performance. Administrative expenses significantly affected the profitability of insurance companies, while leverage negatively affected UP and INI, except ROA. The size of the company also significantly affects all the performance indicators, expanding the branch network and adopting new technologies can improve the performance of life insurance companies.
In the study of Jerene, the author focused on examining the determinants of profitability in the non-life insurance industry in India
| [16] | Jerene, W. (2016). Factors affecting general insurance companies’ profi tability: Empirical study in India. International Journal of Marketing, Financial Services & Management, 5, 1-8. |
[16]
. The study used ROE (return on equity) as the dependent variable and the independent variables included size, premium growth, capital adequacy, liquidity, GDP and inflation. The data was taken from the financial statements of 10 non-life insurance companies (including 4 public companies and 6 private insurance companies) from 2006 to 2016. The results of the regression analysis showed that capital adequacy and GDP have a positive impact on profitability, while liquidity and inflation have a negative impact on the profitability of non-life insurance in India. Based on the research results, the author suggests that managers need to focus on ensuring adequate capital and managing current debt to maintain financial strength in the industry
| [11] | Ha, T. P. D., & Tran, M. D. (2025). AN ANALYSIS OF INVESTMENT DEMAND AND THE DEVELOPMENT TREND OF NON-STATE ENTERPRISES IN VIETNAM. Financial and Credit Activity Problems of Theory and Practice, 1(60), 273-287. https://doi.org/10.55643/fcaptp.1.60.2025.4564 |
[11]
.
Berhe and Kaur conducted a study on the factors affecting the profitability of insurance companies in Ethiopia
| [4] | Berhe, T. A., & Kaur, J. (2017). Determinants of insurance companies’ profitability Analysis of insurance sector in Ethiopia. International Journal of Research in Finance and Marketing (IJRFM), 7(4), 124-137. |
[4]
. ROA was used as the dependent variable, while the independent variables included capital adequacy, leverage ratio, liquidity ratio, and loss ratio, along with external variables such as market share, GDP growth rate, and inflation rate. Data were collected from the annual reports of the National Bank of Ethiopia and insurance companies for the period from 2005-06 to 2014-15. The results of the study showed that the size of insurance business, capital adequacy, liquidity ratio, and GDP growth rate were the major factors affecting the profitability of insurance companies in Ethiopia. However, factors such as leverage ratio, loss ratio, market share, and inflation rate did not have a significant impact on profitability. Therefore, insurance company managers need to focus on increasing leverage, equity capital and improving the quality of employees to achieve better business performance.
The study by Haque et al. focused on the impact of the Covid-19 pandemic on the insurance industry in Bangladesh
| [15] | Haque, A., Mohona, N. T., Sultana, S., & Kulsum, U. (2021). The impact of COVID-19 on the insurance industry of Bangladesh. Indian Journal of Finance and Banking, 6(1), 73-85. https://doi.org/10.46281/ijfb.v6i1.1243. |
[15]
. The independent variables used for assessment were quarterly premium growth (QPG), insurance density (INSD) and insurance penetration (INSP), while external variables such as Covid cases, consumer price index (CPI), producer price index (PPI) and GDP per capita were used to enter the model in the study. The data were collected from the top 20 insurance companies in Bangladesh, using quarterly panel data from 2018 to the first quarter of 2021. The results of the study showed that the Covid-19 pandemic has significantly contributed to the decline of the insurance industry in Bangladesh. The regression model also shows the negative impact of the Covid-19 pandemic on the insurance industry in this country. This negative impact is reflected in the decline in premium growth, insurance density and insurance penetration. This result is statistically more robust and clear than other measures
| [12] | Ha, T. P. D., Tran, M. D., Duong, T. V. A., Pham, X. K., Dao, T. H., Phi, V. T., Nguyen, T. L. A., Truong, V. T., Nguyen, T. T. D. (2024). FACTORS AFFECTING ENERGY ENTERPRISE INVESTMENT DEMAND FOR MACHINERY AND EQUIPMENT. International Journal of Business, Economics and Law (IJBEL), 32(1), 151-161.
https://ijbel.com/previous-issues/august-2024/vol-32-august-2024-issue-1/ |
[12]
.
For domestic studies, Nam evaluated the factors affecting the business performance of enterprises in Vietnam in 2020
| [21] | Nam, N. H. (2021). Factors affecting the business performance of insurance enterprises in Vietnam in 2020. Impact of Covid-19, Insurtech, Market and Policy (CVII 2021). Ho Chi Minh City Economic Publishing House, 193-213. |
[21]
. The data in the article was collected from 10 insurance enterprises in Vietnam in that year. The results show that there is a positive relationship between "Business size" and the business performance of enterprises in Vietnam. On the contrary, the factors "Market price to income index" and "Average customer collection period" have a negative relationship with business performance. Of which, the factor "Business size" has the strongest impact on business performance.
Ari and Fredrik conducted a study on the development and business performance of small and medium enterprises in Vietnam. Using micro data from three surveys of small and medium enterprises in Vietnam in 1990, 1996, and 2002, the study results showed that very few small and medium enterprises successfully integrated internationally although the development of this economic sector is an important driving force contributing to economic growth. The study results suggest that the challenges ahead are enormous. To maintain the high growth rate of recent years in the context of current international economic integration, small and medium enterprises need to do more to enhance their capabilities
.
Dung conducted an overview of the listed companies in Vietnam
. The author identified the characteristics of the private economy, its role in the multi-sector economy in Vietnam, and its international economic integration factors. The private economy develops objectively and naturally. The market mechanism is the natural form of regulation of the activities of the private economic sector. The author points out that the private economic sector has the following basic characteristics: (1) spontaneous and strong vitality, (2) the ability to choose the appropriate scale and organize optimal production, and (3) diversity in scale (however, most are still small and medium scale). The author also points out the barriers that hinder the development of the private economic sector in Vietnam. Lack of capital and weak access to capital markets, low labor quality, low level of application of technical advances, low business efficiency, and lack of support from the state are the main limitations for the development of the private economic sector. In particular, the author also presents a number of basic solutions to develop the private economic sector in Vietnam. According to this author, innovation in management mechanisms and policies is an important premise for the development of the private economy in Vietnam.
Hue shows the great role of the small and medium-sized enterprise economic sector in Vietnam's economic growth in recent times
| [6] | Hue, D.V (2006). Capital efficiency in small and medium enterprises. National Economics University Publishing House. 159 pages. |
[6]
. Small and medium-sized enterprises account for 31% of total annual industrial output and 78% of retail enterprises in commerce. Small and medium-sized enterprises contribute up to 51.7% of Vietnam's economic growth rate; 88.5% of new jobs created for the economy, contribute up to 83.2% of the dynamism and efficiency of the economy, and contribute 63.2% of the number of trained entrepreneurs in the economy. Regarding the issue of economic efficiency of small and medium enterprises, due to low investment costs, it can easily convert production and business plans as well as business types to quickly recover capital and bring high economic efficiency. The study also shows the need to understand the internal factors that promote the effective operation of small and medium enterprises.
3. Research Hypothesis
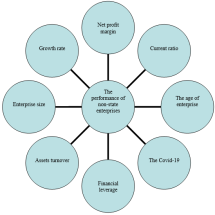
Based on the theoretical content and research on the same topic, hypotheses on internal factors affecting the performance of non-state enterprises in Hanoi are proposed, including: financial leverage, asset turnover, company size, growth rate, net profit margin, current ratio, time of operation of the enterprise since its establishment, Covid-19. Details of the hypotheses are presented as follows:
Hypothesis H1: Financial leverage is expected to have an impact on the performance of non-state enterprises.
Financial leverage is a means for enterprises to increase their profit margin by combining equity and debt capital, also known as using debt. This is a tool with both good and bad qualities. When used properly, financial leverage can bring huge profits to enterprises. However, if financial leverage is abused without good business results, the enterprise may face heavy debt and even bankruptcy. For non-state enterprises, financial leverage can have positive or negative effects depending on how it is used and the business plan of the enterprise. If the enterprise uses financial leverage to expand its business operations and increase sales, it will have a positive effect. On the contrary, if the enterprise uses financial leverage to pay off debt without a business plan to increase sales, it will have a negative impact
| [1] | Ari Kokko and Fredrik Sjöholm (2004). The Internationalization of Vietnamese SMEs. Stockholm School of Economics. http://www.fetp.edu.vn/events/theFilename/E040429E.pdf |
| [4] | Berhe, T. A., & Kaur, J. (2017). Determinants of insurance companies’ profitability Analysis of insurance sector in Ethiopia. International Journal of Research in Finance and Marketing (IJRFM), 7(4), 124-137. |
[1, 4]
.
Hypothesis H2: Asset turnover is expected to have a positive impact on the performance of non-state enterprises.
Asset turnover is a financial indicator used to evaluate the efficiency of using assets of an enterprise. This indicator is considered a tool to evaluate the potential and performance of an enterprise, which is of interest to investors and business leaders. It shows the extent to which each asset generates revenue for the enterprise, and helps them make better decisions about the development potential and stability of the company's operations. The higher the value of asset turnover, the more efficient and profitable the company is. Therefore, this factor is expected to have a positive impact on the performance of non-state enterprises
| [8] | Dung, T. M. (2017). The impact of working capital management on profitability: Evidence from listed companies on the Ho Chi Minh Stock Exchange. Journal of Economics & Development. No. 235. January 2017. pp. 71-78 |
| [19] | Kripa, D., & Ajasllari, D. (2016). Factors affecting the profitability of insurance companies in Albania. European Journal of Multidisciplinary Studies, 1(1), 352-360.
https://doi.org/10.26417/ejms.v1i1.p352-360 |
[8, 19]
.
Hypothesis H3: Enterprise size is expected to have a positive impact on the performance of non-state enterprises.
Firm size is one of the important factors in considering performance. A large-scale enterprise has more advantages than small-scale enterprises. When a business has a large asset size, it can respond to market fluctuations better. In addition, large size also helps businesses take advantage of economies of scale in labor costs when the size of the business is difficult to assess accurately. The logarithm of total assets with a base of 1 billion is used to represent the size of non-state enterprises. Therefore, the factor of firm size is expected to have a positive impact on the performance of non-state enterprises
| [16] | Jerene, W. (2016). Factors affecting general insurance companies’ profi tability: Empirical study in India. International Journal of Marketing, Financial Services & Management, 5, 1-8. |
| [17] | Kartikasari, D., & Merianti, M. (2016). The effect of leverage and firm size to profitability of public manufacturing companies in Indonesia. International Journal of Economics and Financial Issues, 6(2), 409-413. |
[16, 17]
.
Hypothesis H4: Growth rate is expected to have a positive impact on the performance of non-state enterprises.
Growth rate is an indicator that shows the percentage change in a business's revenue over a period of time; it shows the development or decline of a company over time. The growth rate helps us know whether a business has grown in revenue compared to the past. From there, decisions are made to improve revenue in the future. The growth rate factor is expected to have a positive impact on the performance of non-state enterprises
| [3] | Balestra, Pietro; Nerlove, Marc (July 1966). Pooling Cross Section and Time Series Data in the Estimation of a Dynamic Model: The Demand for Natural Gas. Econometrica. 34 (3): 585-612. https://doi.org/10.2307/1909771 JSTOR 1909771. Retrieved February 8, 2022. |
| [15] | Haque, A., Mohona, N. T., Sultana, S., & Kulsum, U. (2021). The impact of COVID-19 on the insurance industry of Bangladesh. Indian Journal of Finance and Banking, 6(1), 73-85. https://doi.org/10.46281/ijfb.v6i1.1243. |
| [16] | Jerene, W. (2016). Factors affecting general insurance companies’ profi tability: Empirical study in India. International Journal of Marketing, Financial Services & Management, 5, 1-8. |
[3, 15, 16]
.
Hypothesis H5: Net profit margin is expected to have a positive impact on the performance of non-state enterprises.
Net profit margin is a financial indicator that shows the ratio of net income (profit after tax) of a business compared to revenue. In other words, it is the percentage of after-tax profit that a business receives from each dollar of revenue. Through this index, investors can see how much money the business earns from total revenue. When a business has a net profit margin higher than the average net profit margin of the industry, it has more advantages than other businesses. In addition, a business with a high net profit margin and growth over many years is a business that investors pay attention to. On the contrary, businesses with negative net profit margins are ignored by investors. Therefore, the net profit margin factor is expected to have a positive impact on the performance of non-state enterprises
| [20] | Loderer, C. F., & Waelchli, U. (2011). Firm Age and Governance. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.1938635 |
| [26] | Ullah, G. M., Faisal, M. N., & Zuhra, S. T. (2016). Factors determining profitability of the insurance industry of Bangladesh. International Finance and Banking, 3(2), 138-147.
https://doi.org/10.5296/ifb.v3i2.9954 |
[20, 26]
.
Hypothesis H6: The current ratio has a positive impact on the performance of non-state enterprises.
The current ratio is a financial index used to measure the short-term debt payment capacity of a business. The current ratio helps businesses assess their ability to use their short-term assets to pay off short-term debts. The current ratio should be greater than 1, and the larger it is, the safer the business is. When this ratio is closer to 0, it shows that the business is financially exhausted in the short term and is no longer able to pay off short-term debts. That has a negative impact on business performance, and can even cause the business to go bankrupt. Therefore, the current ratio factor is expected to have a positive impact on the performance of non-state enterprises
| [2] | Arora, Parvinder Kumar and Chakraborty, Sandip (2012). An analysis of factors affecting private equity investment decision: evidence from Singapore. International Journal of Business Research. Singapore. 12: 104-114. |
| [5] | Coad, A., Segarra, A., & Teruel, M. (2013). Like milk or wine: Does firm performance improve with age? Structural Change and Economic Dynamics, 24, 173-189.
https://doi.org/10,1016/j.strueco.2012.07.002 |
| [25] | Shehata, N., Salhin, A., & El-Helaly, M. (2017). Board diversity and firm performance: evidence from the UK SMEs. Applied Economics, 49(48), 4817-4832.
https://doi.org/10.1080/00036846.2017.1293796 |
[2, 5, 25]
.
Hypothesis H7: The age of the enterprise is expected to have a positive impact on the performance of non-state enterprises.
The time the business has been in operation since its establishment is the age of the business. A business with a long operating age has many advantages, more experience in management and more comprehensive development in all aspects. Such experiences help businesses respond promptly to problems that may arise at any time. In addition, long-standing non-state enterprises can also create trust with customers. Therefore, the factor of the time of operation of the enterprise since its establishment is expected to have a positive impact on the performance of non-state enterprises
| [22] | Olabisi, Sherifat Yusuff (2014). Gender differentials in factors affecting performance of small-scale enterprises in Lagos State, Nigeria. Innovative Issues and Approaches in Social Sciences 6(2), 21-39 |
| [23] | Osunsan, O. K., Nowak, J., Mabonga, E., & Pule, S. (2015). Firm Age and Performance in Kampala, Uganda: A Selection of Small Business Enterprises. International Journal of Academic Research in Business and Social Sciences, 5(4), 412-422. https://doi.org/10.6007/IJARBSS/v5-i4/1582 |
[22, 23]
.
Hypothesis H8: Covid-19 has a negative impact on the performance of non-state enterprises.
The emergence of Covid-19 has severely affected the world economy. The Covid-19 pandemic has greatly affected the trade and investment activities of countries around the world. Covid-19 has significantly affected the business performance of non-state enterprises in Hanoi. When the Covid-19 pandemic occurred, customers tended to keep money in their pockets instead of spending or investing in production and business. That makes the revenue of non-state enterprises tend to decrease sharply. Therefore, the Covid-19 factor is expected to negatively impact the performance of non-state enterprises
| [7] | Doku, J. N., Dzokoto, E., & Kudolo, A. (2021). The Impact of COVID-19 on Emerging Insurance Industry: The Ghanaian Evidence. Available at SSRN 3908216.
https://doi.org/10.2139/ssrn.3908216 |
| [15] | Haque, A., Mohona, N. T., Sultana, S., & Kulsum, U. (2021). The impact of COVID-19 on the insurance industry of Bangladesh. Indian Journal of Finance and Banking, 6(1), 73-85. https://doi.org/10.46281/ijfb.v6i1.1243. |
[7, 15]
.
Figure 1. Research Model (Source: Authors' own data compilation).
4. Research Model
Quantile regression is a statistical method that extends traditional linear regression models by considering the conditional quantiles of the dependent variable. Unlike ordinary least squares regression, which focuses on estimating the conditional mean, quantile regression provides a more comprehensive understanding of the relationship between the independent variables and the dependent variable at each of its quantiles.
The equation for quantile regression is as follows:
y = β₀(τ) +β₁(τ)x₁+ ... +βk(τ)xk+ u(τ)(1)
Where:
Q(y| x₁, x2,..., xk) represents the conditional quantile of the dependent variable Y according to the independent variables x
β₀(τ), β₁(τ), β₂(τ), ..., βₚ(τ) are the regression coefficients of x₁, x₂, ..., xₚ, at a given quantile τ.
The coefficients in the quantile regression model can be estimated using the linear programming method and the iterative reweighted least squares (IRLS) method.
With the above research hypotheses, the factors affecting the performance of non-state enterprises in Hanoi, Vietnam are proposed to be constructed as follows:
Y = β0(τ)+ β1X1 + β2(τ)X2 + β3(τ)X3 + β4(τ)X4 + β5(τ)X5 + β6(τ)X6 + β7(τ)X7 + β8(τ)X8 + U(2)
In which:
a) Y: Dependent variable measuring business performance. In this study, business performance is measured by ROA and ROE.
b) X1: Financial leverage
c) X2: Asset turnover
d) X3: Enterprise size
e) X4: Growth rate
f) X5: Net profit margin
g) X6: Current ratio
h) X7: Age of the enterprise
i) X8: Dummy variable taking the value of 0 for the period before Covid-19 and taking the value of 1 in the period with Covid-19.
The regression model (2) is estimated using the quantile regression method. The quantile regression method was first introduced in 1978 by Koenker and Bassett to supplement linear regression analysis
| [2] | Arora, Parvinder Kumar and Chakraborty, Sandip (2012). An analysis of factors affecting private equity investment decision: evidence from Singapore. International Journal of Business Research. Singapore. 12: 104-114. |
| [18] | Koenker, R., & Bassett Jr, G. (1978). Regression quantiles. Econometrica: journal of the Econometric Society, 33-50. https://doi.org/10.2307/1913643 |
[2, 18]
. This method is special in that instead of estimating the parameters of the mean regression function using the OLS method, it estimates the regression parameters on each quantile of the dependent variable so that the sum of the absolute differences of the regression function at the quantile τ of the dependent variable is the smallest. In other words, instead of determining the marginal impact of the independent variable on the mean value of the dependent variable, quantile regression helps determine the marginal impact of the independent variable on the dependent variable on each quantile of that dependent variable. The advantage of this method is shown in the fact that quantile regression allows a detailed representation of the relationship between the dependent variable and the independent variables on each quantile of the dependent variable with the following advantages:
Firstly, quantile regression provides a more comprehensive understanding of the relationship between the independent variables and the performance of non-state enterprises in Hanoi at many different quantiles instead of just analyzing the impact at the average value of business performance as other studies have done before.
Secondly, the quantile regression results are proven to be stable (robustness). This is a great advantage of quantile regression when unusual observations do not affect or affect the results, unlike regression by the ordinary least squares method. Therefore, in this study, the results of the analysis of the impact of independent variables on the business performance of non-state enterprises also achieved stability - which is the strength of the quantile regression method used.
Third, the statistical significance tests of the quantile regression coefficients do not rely on the normality of the error; nor do they rely on any assumptions about the distribution of the regression error.
Fourth, quantile regression also helps verify the asymmetry in the impact of the studied factors on the performance of non-state enterprises in Hanoi; specifically, the impact at different quantiles of the business performance of non-state enterprises will be different, which other studies with other regression methods cannot demonstrate.
5. Research Data
The research sample was selected based on enterprises in Hanoi listed on the Ho Chi Minh City Stock Exchange (Hose), Hanoi Stock Exchange (HNX) and enterprises listed on the stock exchange for unlisted companies (UPCOM). The data collection period was 5 years, from 2019 to 2023.
The selected enterprise sample must have a business location in 30 districts, towns and cities in Hanoi. Based on secondary data on non-state enterprises up to the time of the survey, the proportional random sampling method was used to ensure that 330 non-state enterprises were randomly selected for the survey with 1,650 observations.
As a result, a random sample was selected for this study ensuring stratification by enterprise type such as agriculture, industry, seafood processing, agricultural processing, mechanics, handicrafts, and construction in the fields of manufacturing, trade, and services.
Table 3 summarizes information on the nature of the survey sample of non-state enterprises in Hanoi. According to the survey sample structure, in the agricultural sector, there are 64.7% private enterprises, 29.4% limited liability companies, and 5.8% state-owned enterprises and joint-stock companies; in the industrial-construction sector, there are 58.5% private enterprises, 29.3% limited liability companies, and 7.3% joint-stock companies; in the trade-service sector, there are 79.4% private enterprises and 18.6% limited liability companies.
Table 3. The surey sample.
Type of enterprise | Agriculture, Forestry, Fishery | Industry, Contruction | Trading, Service | Total |
Number | % | Number | % | Number | % | Number | % |
Joint Stock Co. having capital of State | 3 | 2.8 | 1 | 0.9 | 1 | 0.9 | 5 | 1,5 |
Private | 24 | 22.2 | 28 | 24.8 | 34 | 31.2 | 86 | 26 |
Joint Stock Co. without capital of State | 45 | 41.7 | 46 | 40.7 | 30 | 27.5 | 121 | 36.7 |
Limited Co. | 33 | 30.5 | 36 | 31.9 | 41 | 37.6 | 110 | 33.3 |
Other | 3 | 2.8 | 2 | 1.7 | 3 | 2.8 | 8 | 2.5 |
Total | 108 | 100 | 113 | 100 | 109 | 100 | 330 | 100 |
Source: Author's own data compilation
6. Results and Discussion
6.1. Descriptive Statistics
Table 4 shows the descriptive statistics of variables in the model.
Table 4. Descriptive statistics of variables in the model.
Variables | Number | Mean | Standard deviation | Min | Max |
ROE | 1 650 | 0.098 | 0.054 | 0.067 | 0.303 |
ROA | 1 650 | 0.035 | 0.029 | 0.003 | 0.109 |
X1 | 1 650 | 3.127 | 1.197 | 1.770 | 7.695 |
X2 | 1 650 | 0.394 | 0.169 | 0.128 | 0.819 |
X3 | 1 650 | 1.408 | 0.057 | 1.320 | 1.581 |
X4 | 1 650 | 0.225 | 1.098 | -0.229 | 12.065 |
X5 | 1 650 | 0.109 | 0.077 | 0.005 | 0.386 |
X6 | 1 650 | 1.947 | 1.410 | 0.933 | 9.009 |
X7 | 1 650 | 20.333 | 6.085 | 11.000 | 27.000 |
X8 | 1 650 | 0.200 | 0.402 | 0.000 | 1.000 |
Source: Author's own data compilation
According to the data in
Table 4, the ROE variable has an average value of 0.098, which is about 9.8%, and has a minimum value of 0.067 (6.7%) and a maximum value of 0.303 (30.3%).
The ROA variable has an average value of 0.035, which is about 3.5%, and has a minimum value of 0.029 (2.9%) and a maximum value of 0.109 (10.9%).
The average value of financial leverage is 3.127 and the minimum values, the range of financial leverage fluctuations is also quite large with the difference between the minimum and maximum values.
The asset turnover variable has an average value of 0.394. The standard deviation and the range of variation between the smallest and largest values are relatively low, indicating that the efficiency of asset use or the potential of enterprises also has significant changes and fluctuations.
For the asset size variable measured by the logarithm of total assets, the average value of this variable is 1.408 and the standard deviation is relatively small.
The average growth rate of non-state enterprises in Hanoi is 0.225, or 22.5%. Meanwhile, there are cases of negative growth and there are also enterprises with outstanding growth, which is shown through the large range of variation of this independent variable.
Descriptive statistics of the variables net profit margin, payment index and enterprise age also have a fairly large spread among non-state enterprises in the data sample as well as during the data collection period.
Table 5 shows the correlation coefficient matrix between the independent variables and the dependent variable in the model. The correlation matrix is a useful tool to examine the relationship between independent variables in a regression model, thereby identifying potential risks of multicollinearity.
Table 5. Correlation coefficient matrix.
Variables | ROE | ROA | X1 | X2 | X3 | X4 | X5 | X6 | X7 | X8 |
ROE | 1 | | | | | | | | | |
ROA | 0.857 | 1 | | | | | | | | |
X1 | 0.148 | -0.301 | 1 | | | | | | | |
X2 | 0.119 | 0.161 | -0.118 | 1 | | | | | | |
X3 | -0.028 | -0.251 | 0.608 | -0.346 | 1 | | | | | |
X4 | -0.096 | -0.023 | -0.085 | 0.001 | -0.132 | 1 | | | | |
X5 | 0.476 | 0.567 | -0.184 | -0.603 | 0.042 | -0.056 | 1 | | | |
X6 | -0.041 | 0.073 | -0.05 | 0.056 | -0.018 | 0.058 | 0.023 | 1 | | |
X7 | -0.163 | -0.161 | 0.12 | 0.009 | 0.435 | -0.151 | 0.001 | 0.085 | 1 | |
X8 | 0.248 | 0.102 | 0.216 | 0.031 | 0.204 | -0.048 | 0.01 | -0.148 | 0.000 | 1 |
Source: Author's own data compilation
The results of calculating the regression coefficients in
Table 6 show that the correlation between the independent variables is not strong and there is no sign of strong multicollinearity in the model.
Table 6. Percentile regression results of factors affecting ROE.
Variables | ROE |
τ= 0.1 | τ = 0.25 | τ = 0.5 | τ = 0.75 | τ = 0.9 |
X1 | 0.016*** | 0.020*** | 0.026*** | 0.024*** | 0.018*** |
[0.006] | [0.005] | [0.002] | [0.004] | [0.005] |
X2 | 0.167*** | 0.184*** | 0.207*** | 0.228*** | 0.263*** |
[0.056] | [0.036] | [0.034] | [0.045] | [0.031] |
X3 | -0.033 | -0.035 | -0.161** | -0.096 | 0.037 |
[0.167] | [0.090] | [0.078] | [0.092] | [0.129] |
X4 | 0.007 | 0.003 | 0.002 | 0.002 | 0.0001 |
[0.027] | [0.021] | [0.016] | [0.014] | [0.014] |
X5 | 0.702*** | 0.749*** | 0.881*** | 1.013*** | 1.078*** |
| [0.177] | [0.143] | [0.115] | [0.158] | [0.149] |
X6 | -0.003 | -0.005* | -0.003 | -0.003 | -0.007*** |
| [0.003] | [0.002] | [0.002] | [0.002] | [0.002] |
X7 | 0.0001 | -0.0015** | -0.001*** | -0.002** | -0.003*** |
| [0.001] | [0.0006] | [0.0004] | [0.001] | [0.001] |
X8 | 0.012 | 0.007 | 0.009 | 0.008 | 0.005 |
| [0.016] | [0.013] | [0.007] | [0.014] | [0.023] |
Blocking Factor | -0.066 | -0.038 | 0.105 | 0.016 | -0.124 |
[0.233] | [0.122] | [0.116] | [0.124] | [0.170] |
*, **, ***: regression coefficients are statistically significant at the 10%, 5%, 1% levels, respectively
Table 7. Percentile regression results of factors affecting ROA.
Variables | | | ROA | | |
τ = 0.1 | τ = 0.25 | τ = 0.5 | τ = 0.75 | τ = 0.9 |
X1 | 0.0009 | 0.00056 | 0.0016 | 0.003* | 0.0027 |
[0.002] | [0.0017] | [0.0015] | [0.0016] | [0.002] |
X2 | 0.066*** | 0.059*** | 0.070*** | 0.082*** | 0.083*** |
[0.016] | [0.010] | [0.0121] | [0.013] | [0.022] |
X3 | -0.02 | 0.021 | -0.011 | -0.040 | -0.0266 |
[0.041] | [0.037] | [0.034] | [0.036] | [0.037] |
X4 | 0.003 | 0.002 | 0.002 | 0.002 | 0.001 |
[0.012] | [0.006] | [0.005] | [0.006] | [0.005] |
X5 | 0.302*** | 0.252*** | 0.329*** | 0.427*** | 0.440*** |
[0.065] | [0.052] | [0.045] | [0.044] | [0.059] |
X6 | -0.001 | -0.0066 | -0.0014 | -0.006 | -0.001 |
[0.001] | [0.001] | [0.0009] | [0.001] | [0.0015] |
X7 | -0.00014 | -0.0004** | -0.0003** | -0.0005** | -0.0009*** |
[0.0003] | [0.0002] | [0.00015] | [0.00025] | [0.00032] |
X8 | -0.003 | 0.001 | 0.0014 | 0.0014 | 0.003 |
[0.003] | [0.003] | [0.003] | [0.003] | [0.0034] |
Blocking factor | -0.0003 | -0.041 | -0.009 | 0.025 | 0.017 |
[0.052] | [0.045] | [0.044] | [0.049] | [0.051] |
*, **, ***: regression coefficients are statistically significant at the 10%, 5%, 1% levels, respectively
6.2. Quantile Regression Results
The quantile regression results performed according to model (2) with two dependent variables ROE and ROA are shown in
Table 6 and
Table 7, respectively. In this article, the quantiles selected for inclusion in the regression include quantiles 0.1, 0.25, 0.5, 0.75 and 0.9. These are quantiles that combine deciles and quartiles, just enough to consider the middle and tail quantiles of the dependent variable to be analyzed.
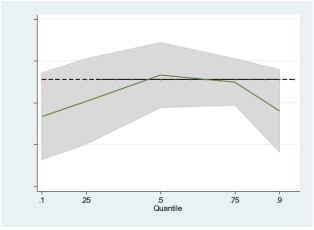
Figure 2 shows the regression coefficient of the financial leverage variable according to the considered quantiles. The broken lines show the fluctuations of the regression coefficients through each quantile and the gray blur shows the 95% confidence intervals of these quantile regression coefficients. The horizontal line represents the OLS regression results, shown in the figure for the convenience of readers when they want to compare the quantile regression and OLS regression results.
Figure 2. Regression coefficients of financial leverage by percentile.
According to the regression results in
Table 6,
Table 7 and shown in
Figure 2, financial leverage (X1) has a positive impact on both ROE and ROA variables at all quantiles and is consistent with the initial expectation. This result is consistent with the previous study
| [3] | Balestra, Pietro; Nerlove, Marc (July 1966). Pooling Cross Section and Time Series Data in the Estimation of a Dynamic Model: The Demand for Natural Gas. Econometrica. 34 (3): 585-612. https://doi.org/10.2307/1909771 JSTOR 1909771. Retrieved February 8, 2022. |
| [4] | Berhe, T. A., & Kaur, J. (2017). Determinants of insurance companies’ profitability Analysis of insurance sector in Ethiopia. International Journal of Research in Finance and Marketing (IJRFM), 7(4), 124-137. |
[3, 4]
. This impact occurs at all quantiles but the strongest impact occurs at quantile 0.5 when considering the dependent variable ROE and quantile 0.75 when considering the dependent variable ROA.
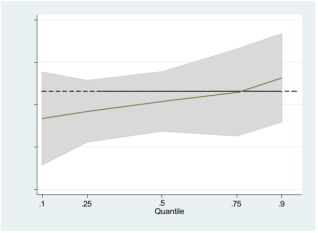
Figure 3. Regression Coefficients of Asset Turnover by Percentile.
The results in
Table 6 and
Table 7 show that the asset turnover variable (X2) in particular has a positive impact on both dependent variables and is consistent with expectations. In addition, asset turnover is statistically significant at the 1% significance level at all quantiles for both ROE and ROA. The graph above also shows that asset turnover has a steadily increasing impact from quantile 0.1 to quantile 0.75 but then the impact level increases more strongly in the quantile range from 0.75 to 0.9. The asset turnover index is more clearly seen when increasing by 1 unit, at quantiles 0.1, 0.25, 0.5, 0.75 and 0.9, the ROE index increases by 16.6%, 18.3%, 20.7%, 22.8% and 26.2% respectively. This result shows that asset turnover has a very significant impact on both ROE and ROA.
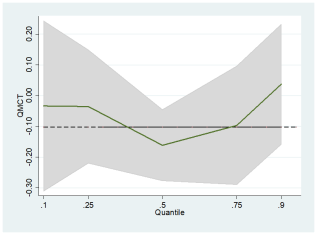
Figure 4. Regression coefficient of enterprise size by percentile.
Regarding the enterprise size variable, in general, X3 has a negative impact on ROE and ROA of non-state enterprises in Hanoi, which is different from the initial research hypothesis. In terms of the calculation formula, total assets are the denominator of ROA and large total assets are also related to large equity. Therefore, the X3 variable has a negative impact on ROA and ROE in terms of calculation. In terms of the above analysis and results in the long term, it is consistent with the research results of Kartikasari and Merianti
| [17] | Kartikasari, D., & Merianti, M. (2016). The effect of leverage and firm size to profitability of public manufacturing companies in Indonesia. International Journal of Economics and Financial Issues, 6(2), 409-413. |
[17]
, Shehata et al.
but contrary to some research results
| [4] | Berhe, T. A., & Kaur, J. (2017). Determinants of insurance companies’ profitability Analysis of insurance sector in Ethiopia. International Journal of Research in Finance and Marketing (IJRFM), 7(4), 124-137. |
| [16] | Jerene, W. (2016). Factors affecting general insurance companies’ profi tability: Empirical study in India. International Journal of Marketing, Financial Services & Management, 5, 1-8. |
[4, 16]
.
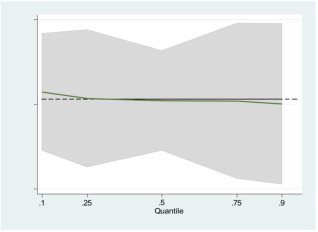
Figure 5. Regression coefficients of growth rate by percentile.
In general, the X4 (growth rate) variable has quite stable impact coefficients and there are no obvious changes across percentiles. However, the data on X4 have weak statistical significance for both ROE and ROA (p-value is greater than 10% at all quantiles). The results show that the variable X4 does not really have an impact on the performance of non-state enterprises in Hanoi. This result is somewhat similar to the impact direction of X4 on performance in the studies of
| [12] | Ha, T. P. D., Tran, M. D., Duong, T. V. A., Pham, X. K., Dao, T. H., Phi, V. T., Nguyen, T. L. A., Truong, V. T., Nguyen, T. T. D. (2024). FACTORS AFFECTING ENERGY ENTERPRISE INVESTMENT DEMAND FOR MACHINERY AND EQUIPMENT. International Journal of Business, Economics and Law (IJBEL), 32(1), 151-161.
https://ijbel.com/previous-issues/august-2024/vol-32-august-2024-issue-1/ |
| [16] | Jerene, W. (2016). Factors affecting general insurance companies’ profi tability: Empirical study in India. International Journal of Marketing, Financial Services & Management, 5, 1-8. |
[12, 16]
, but does not have a high statistical significance as in this study. On the other hand, the results of the authors' study are contrary to the study of Kripa and Ajasllari
| [19] | Kripa, D., & Ajasllari, D. (2016). Factors affecting the profitability of insurance companies in Albania. European Journal of Multidisciplinary Studies, 1(1), 352-360.
https://doi.org/10.26417/ejms.v1i1.p352-360 |
| [26] | Ullah, G. M., Faisal, M. N., & Zuhra, S. T. (2016). Factors determining profitability of the insurance industry of Bangladesh. International Finance and Banking, 3(2), 138-147.
https://doi.org/10.5296/ifb.v3i2.9954 |
[19, 26]
.
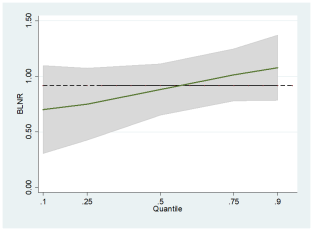
Figure 6. Regression coefficient of net profit margin by quantile.
In general, Net profit margin (X5) has a positive impact on both ROA and ROE, which is also in line with the authors' expectations. With the numerator being after-tax profit, X5 has a large statistical significance for both ROA and ROA at all quantiles (all reaching the 1% significance level). In the ROE model, X5 increases by 1 unit, at quantiles of 0.1, 0.25, 0.5, 0.75 and 0.9, the ROE index increases by 70.18%, 74.96%, 88.13%, 101.3% and 107.7%, respectively.
This result shows that X5 has a huge impact and a very large causal relationship with both ROA and ROE. The fact that only 1 unit of X5 change can change ROE by 70%-100% shows a close connection and an extremely positive impact, but in reality, for businesses to be able to increase the X5 index by 1 unit is a very big problem.
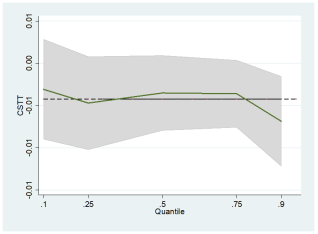
Figure 7. Regression coefficient of current ratio by percentile.
The results from
Table 6 and
Table 7 show that the coefficients of current ratio (X6) variable are all negative at all percentiles for both ROE and ROA models. On the other hand, X6 is not statistically significant at all percentiles for ROA, but is highly significant at the 0.9 percentile (1% level) for ROE. In the ROE model, when X6 increases by 1 unit, at the 0.1, 0.25, 0.5, 0.75 and 0.9 percentiles, the ROE index decreases by 0.3%, 0.4%, 0.3%, 0.3% and 0.6%, respectively.
This result shows that X6 has a negative impact on both ROE and ROA. Non-state enterprises in Hanoi may have inefficiently used idle resources, which leads to high liquidity ratios but does not bring high levels of operational efficiency. This result is also consistent with the study of
| [4] | Berhe, T. A., & Kaur, J. (2017). Determinants of insurance companies’ profitability Analysis of insurance sector in Ethiopia. International Journal of Research in Finance and Marketing (IJRFM), 7(4), 124-137. |
| [11] | Ha, T. P. D., & Tran, M. D. (2025). AN ANALYSIS OF INVESTMENT DEMAND AND THE DEVELOPMENT TREND OF NON-STATE ENTERPRISES IN VIETNAM. Financial and Credit Activity Problems of Theory and Practice, 1(60), 273-287. https://doi.org/10.55643/fcaptp.1.60.2025.4564 |
[4, 11]
.
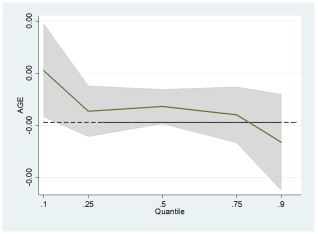
Figure 8. Regression coefficients of the enterprise age by percentile.
The age of the enterprise (X7) variable with the results in
Table 6 has a negative coefficient for all percentiles in the model for ROA. For the ROE variable, X7 only has a positive coefficient at the 0.1 percentile and a negative coefficient at the remaining percentiles. In general, X7 has strong statistical significance, but only at the 0.1 percentile, the statistical significance level is low for both models. The results show that the enterprise age variable X7 has a negative impact on both ROE and ROA. That is, as enterprises operate for a long time, their operational efficiency gradually decreases. However, this impact is insignificant and contrary to expectations. Some studies show that older businesses have better financial performance because they have more experience
| [5] | Coad, A., Segarra, A., & Teruel, M. (2013). Like milk or wine: Does firm performance improve with age? Structural Change and Economic Dynamics, 24, 173-189.
https://doi.org/10,1016/j.strueco.2012.07.002 |
| [23] | Osunsan, O. K., Nowak, J., Mabonga, E., & Pule, S. (2015). Firm Age and Performance in Kampala, Uganda: A Selection of Small Business Enterprises. International Journal of Academic Research in Business and Social Sciences, 5(4), 412-422. https://doi.org/10.6007/IJARBSS/v5-i4/1582 |
[5, 23]
. However, research by Loderer shows that the aging of businesses can negatively affect business performance, reducing indicators such as ROA and ROE
| [12] | Ha, T. P. D., Tran, M. D., Duong, T. V. A., Pham, X. K., Dao, T. H., Phi, V. T., Nguyen, T. L. A., Truong, V. T., Nguyen, T. T. D. (2024). FACTORS AFFECTING ENERGY ENTERPRISE INVESTMENT DEMAND FOR MACHINERY AND EQUIPMENT. International Journal of Business, Economics and Law (IJBEL), 32(1), 151-161.
https://ijbel.com/previous-issues/august-2024/vol-32-august-2024-issue-1/ |
| [20] | Loderer, C. F., & Waelchli, U. (2011). Firm Age and Governance. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.1938635 |
[12, 20]
. Older businesses often have difficulty accessing modern production and business technology, so their competitive advantage is lower than that of younger businesses.
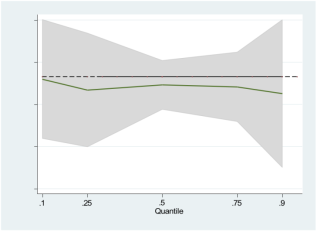
Figure 9. Regression coefficient of net profit margin by percentile.
A notable result is that the Covid-19 dummy variable (X8) has a positive coefficient, but is not statistically significant at all percentiles for ROE and ROA. This shows that in general, Covid-19 does not have a significant impact on the business performance of non-state enterprises in Hanoi. This result is quite different from the research results of Doku when these authors concluded that Covid-19 has a negative impact on the business performance of the insurance industry in Ghana
| [7] | Doku, J. N., Dzokoto, E., & Kudolo, A. (2021). The Impact of COVID-19 on Emerging Insurance Industry: The Ghanaian Evidence. Available at SSRN 3908216.
https://doi.org/10.2139/ssrn.3908216 |
[7]
.
In the context of Vietnam, there are several reasons for the dummy variable about Covid-19 is not statistically significant in the model. Firstly, some insurance companies have a diversified product portfolio, which means they offer a variety of products with different sales methods. While some large-scale, state-invested enterprises were heavily affected, non-state enterprises with more flexible management mechanisms led to increased revenue during the pandemic.
In summary, with the quantile regression results in
Table 6,
Table 7 and shown in the graphs from
Figure 2 to
Figure 9, the results of testing the research hypotheses of the article are summarized as follows:
Table 8. The research results.
Hypothesis | Percentile |
0,1 | 0,25 | 0,5 | 0,75 | 0,9 |
H1 | Support | Support | Support | Support | Support |
H2 | Support | Support | Support | Support | Support |
H3 | Not Support | Not Support | Not Support | Not Support | Not Support |
H4 | Not Support | Not Support | Not Support | Not Support | Not Support |
H5 | Support | Support | Support | Support | Support |
H6 | Not Support | Not Support | Not Support | Not Support | Not Support |
H7 | Not Support | Not Support | Not Support | Not Support | Not Support |
H8 | Not support | Not support | Not support | Not support | Not support |
Source: Author's own data compilation
7. Discussion
Factors affecting the performance of non-state enterprises in Hanoi, Vietnam in the period from 2019-2023 are analyzed in the study. The factors considered include financial leverage, asset turnover, enterprise size, growth rate, net profit margin, current ratio, number of years of operation of the enterprise using the quantile regression method. The research results show that the performance of non-state enterprises in Hanoi, Vietnam is greatly influenced by the factors included in the model. Factors such as financial leverage, asset turnover, net profit margin have a positive impact on the performance of non-state enterprises and this impact occurs in all quantiles considered. When looking specifically at each group of factors, it can be seen that financial leverage shows the role of using capital resources to generate profits in non-state enterprises in Hanoi.
When a business uses financial leverage effectively, it can increase its profitability and use resources optimally, leading to higher growth and operating efficiency.
Asset turnover, another factor, measures a business's ability to manage and utilize its assets. A high asset turnover shows that the business is able to increase the profitability of its assets and operate its business processes effectively, contributing to the overall operating efficiency of non-state enterprises in Hanoi.
Net profit margin is an important indicator that measures the profit that a non-state enterprise earns from its business activities after deducting expenses. The positive impact of net profit margin on business efficiency shows that the business is able to generate high profits from its business activities, while being stable and competitive in Hanoi.
The duration of the enterprise since its establishment, together with the business in Hanoi city, has a negative impact on the performance of non-state enterprises in Hanoi, Vietnam.
Factors such as enterprise size, growth rate, current ratio have no statistical evidence to prove their impact on the performance of non-state enterprises in Hanoi, Vietnam in all quantiles.
The research results can lead to many implications as follows:
First, to improve operational efficiency, non-state enterprises in Hanoi should increase the use of financial leverage to increase the rate of return on equity. However, increasing the debt ratio to use financial leverage needs to be carefully calculated, because excessive use can cause bankruptcy risk if the enterprise cannot repay the debt from cash flow. Therefore, enterprises need to set a reasonable level of financial leverage with an acceptable level of risk.
Second, to maximize business efficiency, non-state enterprises in Hanoi need to establish reasonable advertising policies and strategies to optimize management costs and product marketing. Moreover, network expansion needs to be carefully evaluated. In the current technological era, companies should consider conducting transactions on application platforms to reduce the operating costs of branches and travel, and increase the efficiency of employees.
Third, according to the results of the study, there is an inverse relationship between the number of years of operation of non-state enterprises in Hanoi and their operating efficiency. This shows that enterprises with a lot of experience operating in this field have difficulty in changing or updating their apparatus and products, while younger competitors may be more flexible and more competitive. To solve this problem, non-state enterprises need to continuously update technology and promote innovation to keep up with the times, organize competitions to encourage employees and outside talents to participate. They also need to regularly monitor competitors' products and models to keep up with new trends.
8. Conclusion
The study shows that the optimal use of capital and assets, together with effective financial management and advertising, can play an important role in improving the business performance of non-state enterprises in Hanoi, Vietnam. The study has shown that the operational efficiency of a business depends heavily on internal factors within that business, using empirical evidence from non-state-owned enterprises in Hanoi, Vietnam. Among the influencing factors, asset turnover has a strong, positive impact; financial leverage has a significant, negative impact. This could be an indicator for investors or funding bodies to consider when allocating capital to a business.
Further research directions of the topic can focus on examining the impact of financial and management factors on the performance of non-state enterprises in Hanoi; for example, focusing on analyzing the financial management strategies of non-state enterprises in Hanoi. This includes assessing the level of financial leverage, debt management and strategic thinking about capital to maximize profitability, maintain stable liquidity to deal with unexpected situations.
Abbreviations
ROA | Return on Assets |
ROE | Return on Equities |
Author Contributions
Thi Phuong Dung Ha is the sole author. The author read and approved the final manuscript.
Conflicts of Interest
The Author declares that there is no conflict of interest.
References
| [1] |
Ari Kokko and Fredrik Sjöholm (2004). The Internationalization of Vietnamese SMEs. Stockholm School of Economics.
http://www.fetp.edu.vn/events/theFilename/E040429E.pdf
|
| [2] |
Arora, Parvinder Kumar and Chakraborty, Sandip (2012). An analysis of factors affecting private equity investment decision: evidence from Singapore. International Journal of Business Research. Singapore. 12: 104-114.
|
| [3] |
Balestra, Pietro; Nerlove, Marc (July 1966). Pooling Cross Section and Time Series Data in the Estimation of a Dynamic Model: The Demand for Natural Gas. Econometrica. 34 (3): 585-612.
https://doi.org/10.2307/1909771
JSTOR 1909771. Retrieved February 8, 2022.
|
| [4] |
Berhe, T. A., & Kaur, J. (2017). Determinants of insurance companies’ profitability Analysis of insurance sector in Ethiopia. International Journal of Research in Finance and Marketing (IJRFM), 7(4), 124-137.
|
| [5] |
Coad, A., Segarra, A., & Teruel, M. (2013). Like milk or wine: Does firm performance improve with age? Structural Change and Economic Dynamics, 24, 173-189.
https://doi.org/10,1016/j.strueco.2012.07.002
|
| [6] |
Hue, D.V (2006). Capital efficiency in small and medium enterprises. National Economics University Publishing House. 159 pages.
|
| [7] |
Doku, J. N., Dzokoto, E., & Kudolo, A. (2021). The Impact of COVID-19 on Emerging Insurance Industry: The Ghanaian Evidence. Available at SSRN 3908216.
https://doi.org/10.2139/ssrn.3908216
|
| [8] |
Dung, T. M. (2017). The impact of working capital management on profitability: Evidence from listed companies on the Ho Chi Minh Stock Exchange. Journal of Economics & Development. No. 235. January 2017. pp. 71-78
|
| [9] |
Hanoi City Statistics Department, 2024. Hanoi Statistical Yearbook 2023. Available from HYPERLINK "
https://thongkehanoi.nso.gov.vn/nien-giam-thong-ke/9"
https://thongkehanoi.nso.gov.vn/nien-giam-thong-ke/9 (accessed 31 January 2026).
|
| [10] |
General Statistics Office of Vietnam, 2023. Statistical Yearbook 2022. Statistical Publishing House. Hanoi.
https://www.niengiamthongke.net/home/ngtk-2022/nien-giam-thong-ke-thanh-pho-ha-noi-2022(accessed
6 Feb 2026)
|
| [11] |
Ha, T. P. D., & Tran, M. D. (2025). AN ANALYSIS OF INVESTMENT DEMAND AND THE DEVELOPMENT TREND OF NON-STATE ENTERPRISES IN VIETNAM. Financial and Credit Activity Problems of Theory and Practice, 1(60), 273-287.
https://doi.org/10.55643/fcaptp.1.60.2025.4564
|
| [12] |
Ha, T. P. D., Tran, M. D., Duong, T. V. A., Pham, X. K., Dao, T. H., Phi, V. T., Nguyen, T. L. A., Truong, V. T., Nguyen, T. T. D. (2024). FACTORS AFFECTING ENERGY ENTERPRISE INVESTMENT DEMAND FOR MACHINERY AND EQUIPMENT. International Journal of Business, Economics and Law (IJBEL), 32(1), 151-161.
https://ijbel.com/previous-issues/august-2024/vol-32-august-2024-issue-1/
|
| [13] |
Statistical Publishing House. Hanoi Statistical Yearbook 2022. Available from
https://opac.nlv.gov.vn/chi-tiet-tai-lieu/nien-giam-thong-ke-thanh-pho-ha-noi-nam-2022-%28tom-tat%29-202510047970518142931
(accessed 31 January 2026).
|
| [14] |
Hanoi City Statistics Department. Hanoi Statistical Yearbook 2023. Available from
https://thongkehanoi.nso.gov.vn/nien-giam-thong-ke/9
(accessed 31 January 2026).
|
| [15] |
Haque, A., Mohona, N. T., Sultana, S., & Kulsum, U. (2021). The impact of COVID-19 on the insurance industry of Bangladesh. Indian Journal of Finance and Banking, 6(1), 73-85.
https://doi.org/10.46281/ijfb.v6i1.1243.
|
| [16] |
Jerene, W. (2016). Factors affecting general insurance companies’ profi tability: Empirical study in India. International Journal of Marketing, Financial Services & Management, 5, 1-8.
|
| [17] |
Kartikasari, D., & Merianti, M. (2016). The effect of leverage and firm size to profitability of public manufacturing companies in Indonesia. International Journal of Economics and Financial Issues, 6(2), 409-413.
|
| [18] |
Koenker, R., & Bassett Jr, G. (1978). Regression quantiles. Econometrica: journal of the Econometric Society, 33-50.
https://doi.org/10.2307/1913643
|
| [19] |
Kripa, D., & Ajasllari, D. (2016). Factors affecting the profitability of insurance companies in Albania. European Journal of Multidisciplinary Studies, 1(1), 352-360.
https://doi.org/10.26417/ejms.v1i1.p352-360
|
| [20] |
Loderer, C. F., & Waelchli, U. (2011). Firm Age and Governance. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.1938635
|
| [21] |
Nam, N. H. (2021). Factors affecting the business performance of insurance enterprises in Vietnam in 2020. Impact of Covid-19, Insurtech, Market and Policy (CVII 2021). Ho Chi Minh City Economic Publishing House, 193-213.
|
| [22] |
Olabisi, Sherifat Yusuff (2014). Gender differentials in factors affecting performance of small-scale enterprises in Lagos State, Nigeria. Innovative Issues and Approaches in Social Sciences 6(2), 21-39
|
| [23] |
Osunsan, O. K., Nowak, J., Mabonga, E., & Pule, S. (2015). Firm Age and Performance in Kampala, Uganda: A Selection of Small Business Enterprises. International Journal of Academic Research in Business and Social Sciences, 5(4), 412-422.
https://doi.org/10.6007/IJARBSS/v5-i4/1582
|
| [24] |
Rashid, A., & Kemal, M. U. (2018). Impact of internal (micro) and external (macro) factors on profitability of insurance companies. Journal of Economic Policy Researches, 5(1), 35-57.
|
| [25] |
Shehata, N., Salhin, A., & El-Helaly, M. (2017). Board diversity and firm performance: evidence from the UK SMEs. Applied Economics, 49(48), 4817-4832.
https://doi.org/10.1080/00036846.2017.1293796
|
| [26] |
Ullah, G. M., Faisal, M. N., & Zuhra, S. T. (2016). Factors determining profitability of the insurance industry of Bangladesh. International Finance and Banking, 3(2), 138-147.
https://doi.org/10.5296/ifb.v3i2.9954
|
Cite This Article
-
-
@article{10.11648/j.ijsdr.20261201.13,
  author = {Thi Phuong Dung Ha},
  title = {The Factors Affecting the Performance of Non-State Enterprises in Hanoi, Vietnam},
  journal = {International Journal of Sustainable Development Research},
  volume = {12},
  number = {1},
  pages = {36-50},
  doi = {10.11648/j.ijsdr.20261201.13},
  url = {https://doi.org/10.11648/j.ijsdr.20261201.13},
  eprint = {https://article.sciencepublishinggroup.com/pdf/10.11648.j.ijsdr.20261201.13},
  abstract = {Financial performance plays a central and decisive role in the survival, development, and competitiveness of a business. Factors affecting financial performance can be divided into internal and external groups. This article examines how internal factors affect business performance, based on an empirical study of a non-state-owned enterprise in Hanoi, Vietnam. The article was conducted to study the factors of enterprises affecting the performance of non-state enterprises in Hanoi, Vietnam. The article was conducted in the period from 2019 to 2023 using the quantile regression method according to the linear regression model. The research results on the model for ROE, ROA show that the factors of financial leverage, asset turnover, and net profit margin have a positive impact on the performance of non-state enterprises in Hanoi, Vietnam. Factors such as number of years of operation, enterprise size, growth rate, current ratio, have no statistical evidence of impact on the performance of non-stated enterprises in Hanoi, Vietnam in all quantiles. Therefore, to improve financial performance, the management board needs to accelerate asset turnover and make rational use of business leverage – these are the driving forces behind improved financial performance. The number of years in operation or the size of the enterprise are not indicators for investors about whether an enterprise will be successful.},
 year = {2026}
}
 Copy
|
 Download
-
TY  - JOUR
T1  - The Factors Affecting the Performance of Non-State Enterprises in Hanoi, Vietnam
AU  - Thi Phuong Dung Ha
Y1  - 2026/02/20
PY  - 2026
N1  - https://doi.org/10.11648/j.ijsdr.20261201.13
DO  - 10.11648/j.ijsdr.20261201.13
T2  - International Journal of Sustainable Development Research
JF  - International Journal of Sustainable Development Research
JO  - International Journal of Sustainable Development Research
SP  - 36
EP  - 50
PB  - Science Publishing Group
SN  - 2575-1832
UR  - https://doi.org/10.11648/j.ijsdr.20261201.13
AB  - Financial performance plays a central and decisive role in the survival, development, and competitiveness of a business. Factors affecting financial performance can be divided into internal and external groups. This article examines how internal factors affect business performance, based on an empirical study of a non-state-owned enterprise in Hanoi, Vietnam. The article was conducted to study the factors of enterprises affecting the performance of non-state enterprises in Hanoi, Vietnam. The article was conducted in the period from 2019 to 2023 using the quantile regression method according to the linear regression model. The research results on the model for ROE, ROA show that the factors of financial leverage, asset turnover, and net profit margin have a positive impact on the performance of non-state enterprises in Hanoi, Vietnam. Factors such as number of years of operation, enterprise size, growth rate, current ratio, have no statistical evidence of impact on the performance of non-stated enterprises in Hanoi, Vietnam in all quantiles. Therefore, to improve financial performance, the management board needs to accelerate asset turnover and make rational use of business leverage – these are the driving forces behind improved financial performance. The number of years in operation or the size of the enterprise are not indicators for investors about whether an enterprise will be successful.
VL  - 12
IS  - 1
ER  -
Copy
|
Download


 Share This Article
 Twitter
 Linked In
 Facebook
